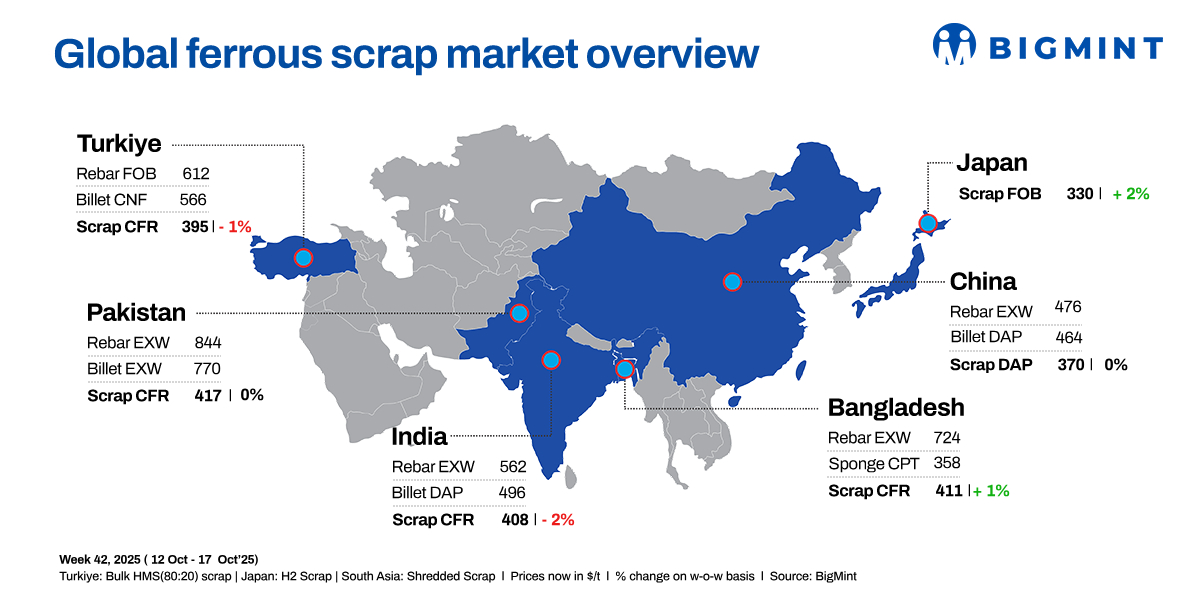
- Turkiye scrap prices weakened as rebar demand softened
- Pakistan offers rose following Strait of Hormuz disruption
Global ferrous scrap markets remained mixed during the week ending 17 October 2026, with Turkish prices under pressure, Indian imports subdued and Pakistani offers rising after shipping disruptions. Bangladesh trading improved temporarily, while Japanese prices strengthened amid domestic mill buying hikes.
Turkiye: Deep-sea scrap market weakened early in the week as falling rebar prices weighed on sentiment, with US-origin HMS 80:20 values easing from $404/t to around $398-400/t CFR. Prices subsequently stabilised, with US-origin tradable values mostly at $395-400/t and EU-origin material at $375-390/t. Limited offers from US and Baltic suppliers, coupled with elevated freight costs, restricted sellers’ flexibility. Two UK-origin HMS 80:20 cargoes were reportedly booked at $388-390/t CFR, although the deals remained unconfirmed.
Rebar export prices fell by $4-5/t d-o-d to $610-612/t FOB, following a nearly $20/t decline over two weeks. HMS 80:20 stood at $395-396/t CFR, with buyers resisting higher offers. One recycler expected a further $5/t decline, although demand could improve in the second half of October as mills secure December-shipment cargoes.
US: Ferrous scrap exports rose 4% y-o-y to 8.60 mnt in January-August 2026, driven by stronger shipments to Mexico, Canada and Peru. Domestic consumption increased 9% to 42.2 mnt, while shredded and HMS 80:20 export prices rose 9% to $375/t and $355/t FOB, respectively.
India: Imported scrap market remained subdued as falling domestic prices, weak rebar demand and cheaper alternatives limited buying. HMS 80:20 bids stayed at $355-360/t CFR Mundra, while UK shredded offers eased to $405-410/t and later $395/t CFR Nhava Sheva, with wide bid-offer gaps restricting fresh bookings.
High freight costs and cheaper domestic alternatives kept Indian import demand subdued. Australian HMS offers to Chennai stood at $360-365/t, while shredded scrap was offered at $375-380/t; Nhava Sheva offers were $385-395/t CFR. A UK-origin 750 t turnings cargo was reportedly booked at $338/t CFR Chennai.
Meanwhile, Nagpur Customs clarified PSIC exemption norms for eligible scrap imports, allowing unshredded scrap clearance through designated ports and eligible ICDs/CFSs, subject to origin verification, documentation and mandatory safety checks. Weak import economics continue to limit buying interest.
In the last seven days, a total of 2,500-3,000 t of imported scrap was tracked for India, including 1,000-1,500 t of HMS 60:40 from Costa Rica, turnings, CR busheling.
Pakistan: Imported scrap market remained subdued early in the week, with European-origin shredded offers easing to $413-415/t CFR Qasim from $420-425/t, against bids of $410-412/t. UK-origin shredded scrap remained workable around $415/t CFR Qasim, while a 2,000 t cargo was reportedly sold at $415-416/t. Trading from Malaysia remained on hold due to shipping issues, while UAE-origin purchases were limited as sellers fulfilled pending orders.
Sentiment strengthened after a Singapore-flagged container vessel carrying around 30,000 t of scrap destined for Pakistan sank in the Strait of Hormuz on 13 October, raising supply concerns. UK/EU shredded offers climbed to $416-418/t CFR Qasim, and replacement bookings reportedly exceeded 20,000 t within three days. Domestic scrap prices remained at PKR 133,000-135,000/t, while tighter availability and shipping uncertainty could place further upward pressure on imported scrap prices.
Bangladesh: Imported scrap market saw mixed activity, with high freight costs and wide bid-offer gaps initially limiting buying interest. Australia/New Zealand HMS-PNS mix offers stood at $390-400/t CFR Chattogram against bids of $380-385/t, while Singapore and Malaysian PNS offers ranged from $424-430/t. Activity later improved, with four deals totalling 10,000 t reported at $375-405/t CFR Chattogram. However, high finished steel inventories curbed demand towards the week’s end, pushing Australian shredded offers to $415/t CFR Chattogram, while domestic scrap prices stood at BDT 55,000-57,000/t.
Japan: Ferrous scrap market remained bullish, with FOB Tokyo Bay prices rising JPY 800/t to JPY 52,200/t ($330/t).
Tokyo Steel raised H2 buying prices by JPY 1,000/t across all plants, marking its third increase in October. A weaker yen and expectations of recovering demand supported sentiment, although no H2 export deals were reported.
UAE: Domestic HMS 80:20 (processed) assessment fell by AED 6/t ($2/t) w-o-w to AED 1,026/t ($279/t) as sluggish demand and lower-priced bookings weighed on the market. Imported rebar prices remained unchanged, while billet prices increased amid tighter availability of Asian material, with regional security risks disrupting trade and raising concerns over delivery timelines.
Leave a Reply