- INSG forecasts global nickel surplus of 19,000 t in 2026
- Indonesia considers curbs on new smelters amid oversupply
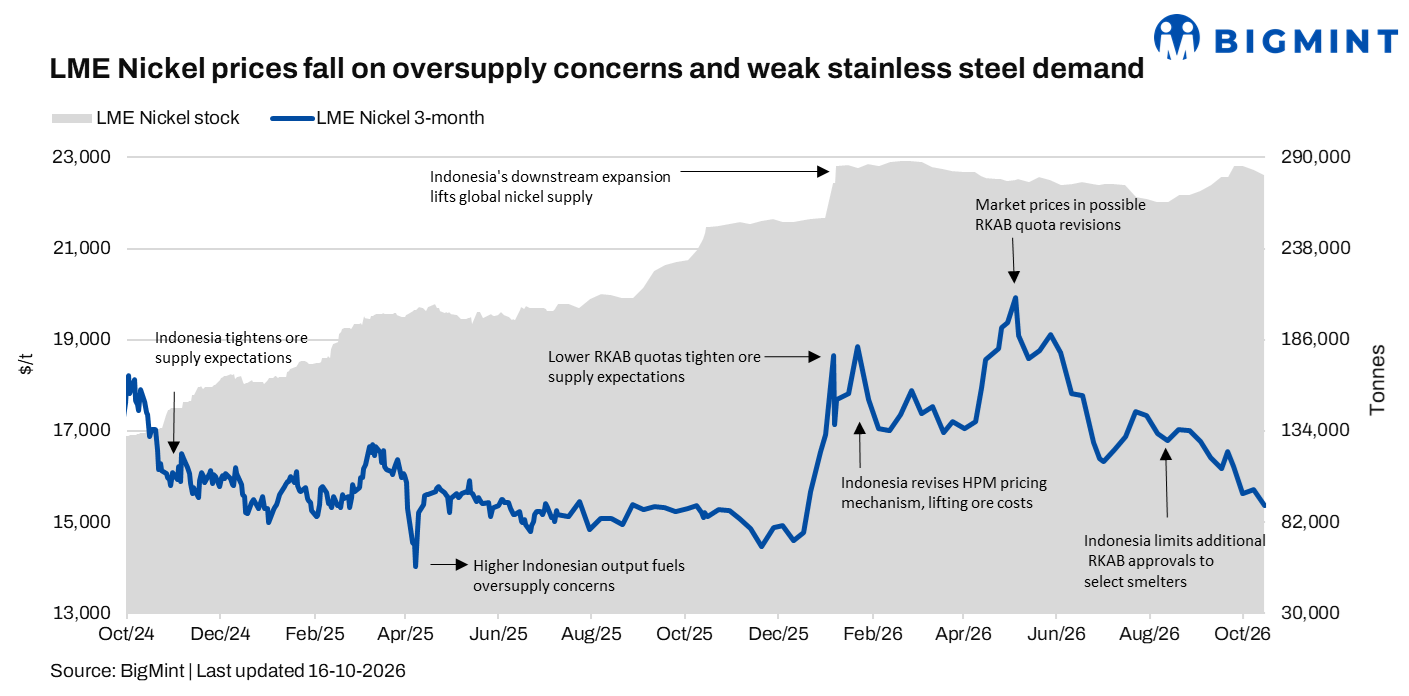
London Metal Exchange (LME) three-month nickel prices declined 2.3% week-on-week (w-o-w) to $15,355/t on 16 October 2026, from $15,720/t a week earlier. Prices remained under pressure from persistent global oversupply concerns and subdued downstream buying, despite a 1% decline in LME inventories to 279,990 t from 282,864 t.
Global surplus outlook weighs on prices
The International Nickel Study Group (INSG), following its meetings on 12-13 October, forecast the global primary nickel market to record a surplus of 19,000 t in 2026, reversing its earlier deficit forecast of 32,000 t. The surplus is expected to widen to 70,000 t in 2027, as production growth outpaces consumption. Although the projected surplus for 2026 is significantly lower than the 299,000 t recorded in 2025, expectations of renewed supply growth continue to limit price recovery.
Weak stainless steel demand pressures NPI
Downstream weakness further dampened market sentiment during the week. According to market participants, falling stainless steel product prices reduced raw material purchasing confidence, while steel mills maintained cautious procurement and pushed for lower nickel pig iron (NPI) prices. Limited buying interest and a wide gap between buyers’ expectations and sellers’ offers constrained transactions, keeping the NPI market under pressure.
Indonesia’s supply policies remain in focus
Indonesia is considering restrictions on new smelters producing semi-finished nickel products, including NPI and ferronickel, to address oversupply and encourage higher-value downstream manufacturing. However, the proposal remains under consideration, with its scope and implementation timeline yet to be confirmed. Consequently, its impact on near-term supply remains uncertain.
Meanwhile, Indonesia’s expanding high-pressure acid leaching (HPAL) capacity could increase demand for low-grade limonite ore in 2027. If mining quotas fail to keep pace with demand and allocations shift towards limonite, the availability of high-grade saprolite used in NPI production could tighten, potentially increasing raw material costs for stainless steel producers.
In the near term, nickel prices are likely to remain sensitive to global supply-demand expectations, Chinese stainless steel demand and developments in Indonesia’s mining quotas and smelter policies.
Leave a Reply