- Firm Chinese demand, supply tightness expectations support LME uptick
- Record-low treatment charges highlight concentrate supply constraints
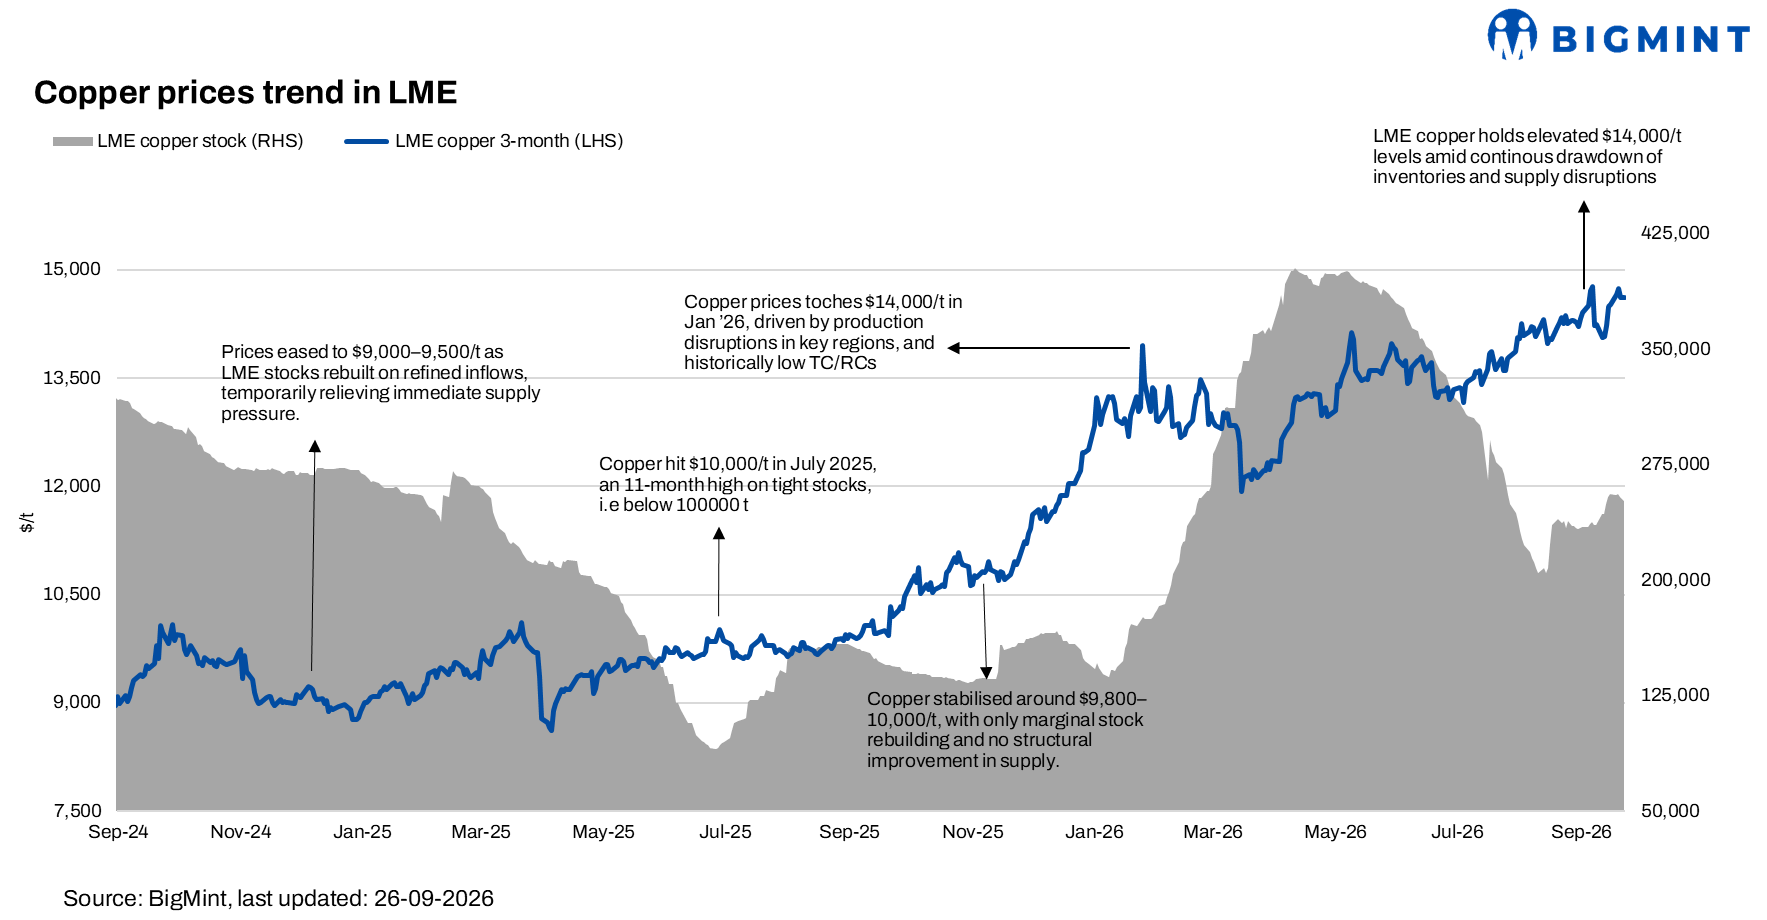
Copper prices continued to strengthen this week, supported by tightening physical availability in China and concerns over global mine supply. LME three-month copper traded around $14,623/t on 25 September, compared with $14,522/t a week earlier, up 0.7% w-o-w. Falling Chinese inventories and firm import demand supported prices.
Chinese copper premiums also remained elevated, indicating strong demand for imported metal. Several smelters have announced maintenance schedules for October-November, raising concerns over near-term supply. Despite volatility from US tariff uncertainty and a stronger dollar, copper prices remained near record levels.
Global refined copper surplus narrows sharply in Jan-Jul’26
The global refined copper market recorded a preliminary 32,000 t surplus during January-July 2026. This was sharply lower than the 157,000 t surplus recorded a year earlier, according to the International Copper Study Group (ICSG). After adjusting for estimated changes in Chinese bonded stocks, the market showed a 5,000 t deficit. This points to tighter underlying availability.
Refined copper production increased 1.7% y-o-y during the period. Higher output from China and the DRC supported growth. New refining capacity in India also contributed. However, maintenance and operational disruptions in Chile and lower output in parts of Asia limited the increase.
World apparent refined copper usage rose 2.4% y-o-y in the first seven months. Chinese apparent demand increased 3.5%, while usage outside China grew 1%. China’s net refined copper imports, however, declined 10%.
Global concentrate shortage supports copper
The global copper market remains tight as smelting capacity expands faster than mine supply. China commissioned two new copper smelters this year, with a combined capacity of 600,000 t/year. Market participants estimate a global copper concentrate deficit of more than 600,000 t in 2026.
Spot copper treatment charges remained at record-low levels during the week. China’s major smelters also did not set a Q4 benchmark, reflecting tight feedstock availability. Mine disruptions have added further pressure to the concentrate market.
India
According to BigMint’s assessment, ex-Ahmedabad cathode prices rose by INR 18,000/t, or 1.3% w-o-w, to INR 1,408,000/t from INR 1,390,000/t. Ex-Mumbai prices increased by the same amount to INR 1,406,000/t from INR 1,388,000/t.
India’s refined copper production reached a 2026 high of 72,000 t in July. Higher smelter output and Kutch Copper’s ramp-up supported the increase. Adani Enterprises reported 64,700 t of copper sales in Q1FY27, reflecting rising domestic supply.
Domestic buying remained firm ahead of the festive season. However, high prices kept buyers focused on immediate requirements. India’s reliance on imported concentrate also remains relevant amid tight global feedstock availability.
Copper prices are expected to remain firm but volatile in the near term. Tight concentrate supply should provide support. However, high prices, rising inventories and US trade-policy uncertainty could limit further gains.
Leave a Reply