- Water shortages reduce Indonesian smelter operating rates
- Weak Chinese demand limits steeper nickel price upside
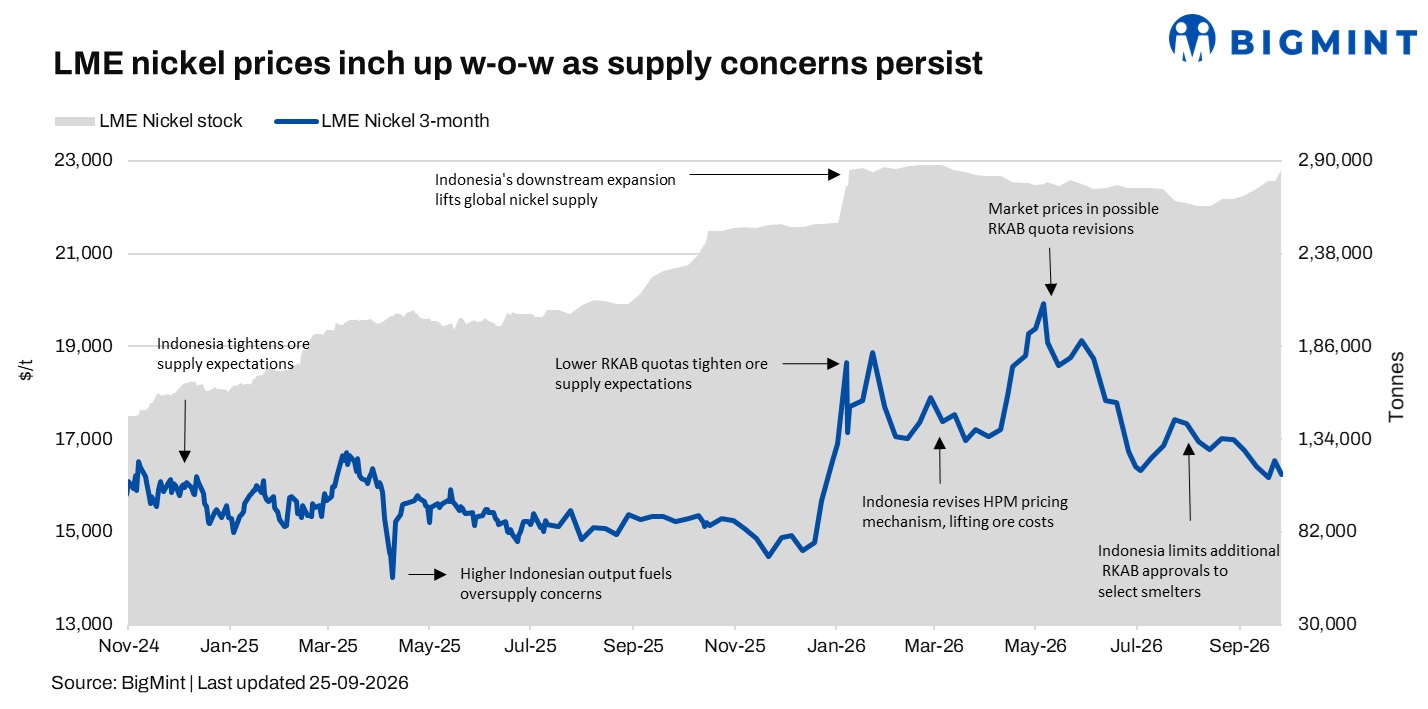
LME three-month nickel prices increased marginally to $16,230/t on 25 September 2026, compared with $16,180/t a week earlier. LME nickel inventories increased 2.1% w-o-w to 284,946 t from 278,826 t, indicating higher availability in the exchange system.
LME nickel prices could receive near-term support from production cuts at the Indonesia Morowali Industrial Park (IMIP), where water shortages have forced some nickel pig iron (NPI) smelters to reduce operating rates. However, weak Chinese stainless steel demand and elevated nickel inventories could limit the upside.
Indonesian NPI cuts tighten supply outlook
NPI plants at IMIP reportedly began reducing operating loads by around 30-40% from 22 September amid water shortages linked to dry weather conditions.
If the cuts continue for half a month, estimated NPI production losses could reach 50,000-70,000 t, equivalent to around 5,500-7,700 t of contained nickel at an 11% nickel grade.
If the disruption persists, cumulative NPI losses could exceed 100,000 t, equivalent to more than 11,000 t of contained nickel.
The potential supply reduction provides near-term support to nickel prices, particularly if water shortages persist and smelter operating rates remain constrained.
Weak stainless steel demand limits upside
The supply-side disruption comes against a backdrop of subdued Chinese stainless steel demand. October 300-series stainless steel production is expected to decline by more than 100,000 t m-o-m, as weak downstream buying and pressure on mill margins encourage production cuts.
Lower stainless output could reduce NPI consumption and partially offset the impact of Indonesian supply disruptions.
Chinese high-grade NPI prices declined to around RMB 1,039.5/mtu on 22 September, from RMB 1,114/mtu at the end of August, reflecting weak demand conditions.
Elevated inventories provide near-term cushion
Chinese port NPI inventories stood at around 53,800 t of contained nickel as of 17 September, up from 35,300 t on 3 September.
The increase provides a buffer against reduced Indonesian supply in the near term and could limit the immediate impact on physical nickel availability.
However, sustained production losses could gradually draw down inventories if Chinese stainless steel mills increase procurement.
Market outlook
The outlook for LME nickel remains balanced between Indonesian supply disruptions and weak downstream demand. Prolonged NPI production cuts at IMIP could strengthen the supply-side case and provide support to nickel prices.
However, rising LME inventories, subdued Chinese stainless steel production and weak mill margins may restrict sustained price gains.
The duration of the Indonesian disruption, IMIP operating rates, Chinese stainless steel production, and inventory movements will remain key indicators for LME nickel prices in the near term.
Leave a Reply