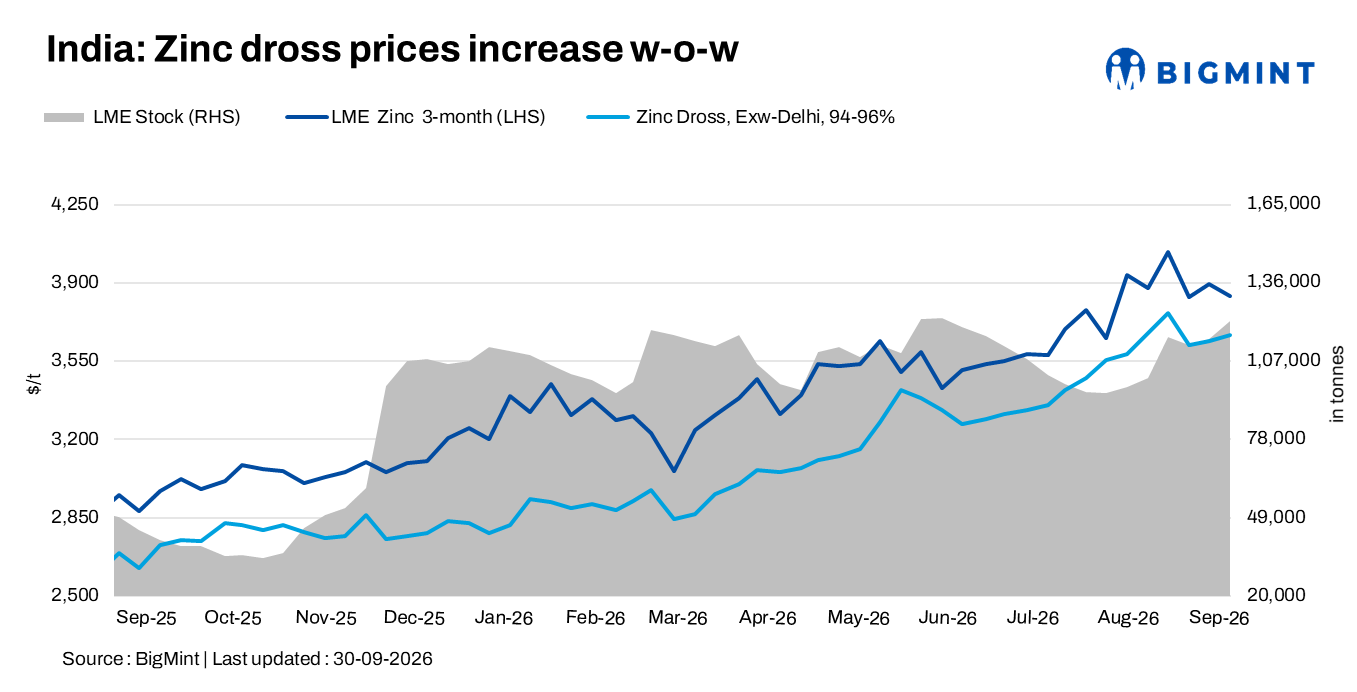
- LME zinc 3-month price declines 1.3% w-o-w; backwardation widens
- Zinc scrap prices remain broadly stable
India’s zinc dross and oxide prices increased w-o-w in the week ended 30 September, despite a decline in three-month LME zinc prices and a marginal correction in domestic SHG zinc. Zinc dross and oxide prices rose by 0.7% and 0.4%, respectively, supported by firmer secondary market replacement costs.
Three-month LME zinc declined by $51/t, or 1.3%, w-o-w to $3,842/t on 30 September from $3,893/t on 23 September. The cash-settlement price increased marginally by $5/t to $3,954/t.
The cash-to-three-month backwardation widened to $112/t from $56/t a week earlier, indicating stronger nearby tightness. Meanwhile, LME inventories increased by 6,725 t to 121,600 t from 114,875 t a week earlier.
Zinc dross, oxide prices increase
Domestic zinc dross prices increased by INR 2,500/t w-o-w to INR 351,900/t ex-Delhi on 30 September, compared with INR 349,400/t a week earlier. Zinc oxide (99% Zn) prices increased by INR 1,300/t to INR 333,000/t ex-Delhi from INR 331,700/t.
The increase in secondary zinc prices came despite a marginal decline in domestic SHG zinc and weaker three-month LME zinc. Firmer nearby LME spreads and replacement costs provided support to the secondary market.
Zinc scrap prices remain broadly stable
In the north Indian zinc scrap market, big Tukdi (97-98% Zn) was assessed at around INR 354,000/t ex-Delhi, while mid-sized Tukdi (97-98% Zn) was around INR 348,000/t. Small Tukdi was assessed at around INR 339,000/t.
The market remained relatively stable, with limited movement reported in zinc scrap prices during the week.
Domestic SHG zinc edges lower
BigMint’s assessment of domestic SHG zinc ingot prices stood at INR 438,000/t ex-Delhi on 30 September, down INR 700/t from INR 438,700/t on 23 September.
The marginal correction in domestic primary zinc values contrasted with the increase in secondary zinc prices during the week. Meanwhile, the wider cash-to-three-month backwardation on LME indicated firmer nearby market conditions despite higher exchange inventories.
LME zinc prices, exchange inventories and the cash-to-three-month spread will remain important indicators for the secondary market. Rising LME inventories may weigh on sentiment, while the wider backwardation and relatively firm domestic replacement costs could continue to provide support to secondary zinc prices.
Outlook
Zinc dross and oxide prices may remain broadly stable in the coming week, with the market balancing higher LME inventories against stronger nearby zinc market conditions.
The wider LME cash-to-three-month backwardation and relatively firm domestic secondary market could provide support to prices, while the decline in three-month LME zinc and marginally lower SHG values may limit further upside.
Further price movement in dross and oxide is likely to depend on the direction of primary zinc prices, LME inventory levels, nearby spreads and domestic demand.
Leave a Reply