- OMC’s sharp price revision strengthens pellet cost support
- Pellet offers from Raipur remained firm
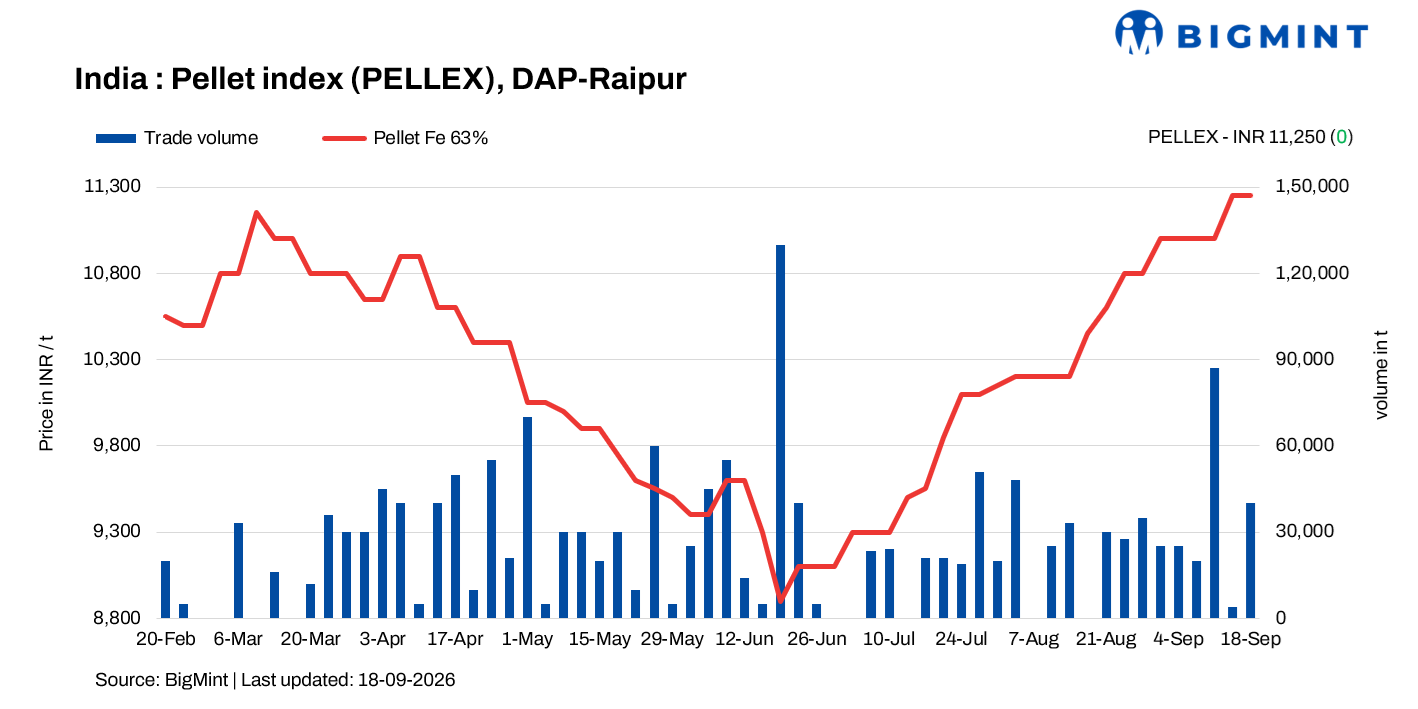
PELLEX, BigMint’s bi-weekly domestic pellet (Fe 63% +/- 0.5%) index for Raipur remained unchanged at INR 11,250/t DAP Raipur on 18 September 2026 against 15 September.
The market continued to draw support from higher iron ore costs following Odisha Mining Corporation’s (OMC) latest base-price revision, announced yesterday. OMC increased fines prices by around INR 650-750/t and lump prices by up to INR 1,200/t, significantly higher than market expectations. The sharp revision has strengthened replacement-cost concerns among pellet producers and provided further support to prevailing pellet prices.
Rationale
- PELLEX has been derived using data points, i.e., trades, offers, and bids. To download the detailed methodology, click here.
- Two (2) deals were recorded in this publishing window of which one (1) was taken for calculation. Thus, the T1 trade category was accorded a weightage of 50%.
- Thirteen (13) firm offers, bids, and indicative prices were heard, of which twelve (12) were taken for price calculation and given the balance 50% weightage.
Price movements and offers
Major pellet manufacturers in Chhattisgarh largely maintained their offers for Fe 62.5/63% (+/-0.5%) grade pellets in-line with the previous assessment. Sellers showed no inclination to reduce offers, with the market continuing to receive support from firm sponge iron and billet prices. Market participants reported selective transactions at higher price levels in neighbouring markets, further strengthening sellers’ confidence.
Around 40,000 t of pellet deals were reported during the assessment period, indicating continued procurement interest from consumers, including volumes contributing from Odisha market as well.
Market scenario
The Raipur pellet market remained firm, with sellers holding offers at elevated levels following the sharp increase in OMC’s iron ore prices. Monsoon-related disruptions to mining and dispatches in Odisha have further heightened concerns over raw-material availability, while higher coking coal and pellet costs continue to keep steelmakers under pressure.
Despite the firm price environment, buyers remained selective in fresh procurement. Market participants indicated that consumers were actively looking for material at workable levels and were comparing offers from different origins to optimise replacement costs.
Some transactions were reported from neighbouring markets, with a Raipur-based buyer indicating that material was being procured at around INR 100/t below prevailing local offers to meet immediate requirements.
On the downstream side, firm sponge iron and billet prices continue to provide support to pellet realisations. Higher raw-material costs have raised replacement values across the ferrous value chain, limiting sellers’ willingness to offer discounts. However, the absence of stronger spot demand has prevented a sharper increase in pellet prices during the latest assessment.
The latest OMC revision has also altered near-term market expectations. Earlier expectations of a possible correction in pellet prices if sponge iron and billet markets weakened have been replaced by expectations of further price support, provided OMC maintains higher base prices and upcoming auction premiums remain healthy.
Pellet producers are therefore likely to remain firm on offers, with some sellers anticipating another increase if OMC auction bids emerge at elevated premiums. However, buyers’ resistance at current price levels remains an important constraint, particularly if downstream steel prices fail to absorb the higher raw-material costs.
Market participants indicated that domestic coal availability are expected and supply conditions may improve as the monsoon recedes, potentially may ease coal prices. This could partly cushion the impact of higher pellet costs on steelmakers, although the overall raw-material cost structure remains elevated.
Pellet offers from neighbouring markets are also expected to remain firm, supported by the broader increase in iron ore costs. 
Key market drivers
- Sponge iron prices edge down w-o-w: Sponge PDRI prices stood at INR 29,300/t ($305/t) exw Raipur, softening by INR 100/t w-o-w on 18 September against 11 September. Domestic sponge iron prices declined by around INR 100-200/t d-o-d across major regions. Festive-day celebrations in some regions further slowed market momentum and kept trading activity subdued. In Raipur, PDRI prices settled at around INR 29,200/t, down by INR 200/t. Market movement remained slow, with enquiries largely limited to need-based purchases. Buyers continued to remain cautious at current levels, as expectations of further price correction kept fresh buying interest limited. Demand from the finished steel segment also remained subdued, offering limited support to sponge iron prices and weighing on overall market sentiment.
- Billet prices inch higher w-o-w: BigMint’s billet index in Raipur rose by INR 1,050/t ($11/t) to INR 44,600/t ($465/t) exw on 18 September 2026 against 11 September. Sellers were offering material at firm levels, although overall buying remained largely need-based. Sellers remained firm on offers following the holiday, while buyers showed limited interest and largely focused on immediate requirements. Trading activity remained subdued, with only limited deals concluded during the session as participants continued to adopt a cautious approach.
Outlook
BigMint expects the Raipur pellet market to remain steady to bullish in the near term, supported by higher OMC iron ore prices and firm replacement costs. Sellers are likely to maintain firm offers and could attempt further increases if upcoming OMC auction premiums remain healthy. However, selective buying and sensitivity to elevated pellet prices could limit the pace of gains.
Leave a Reply