- UAE rebar market turns cash-driven amid tighter liquidity
- Saudi scrap prices decline, tight billet supply supports markets
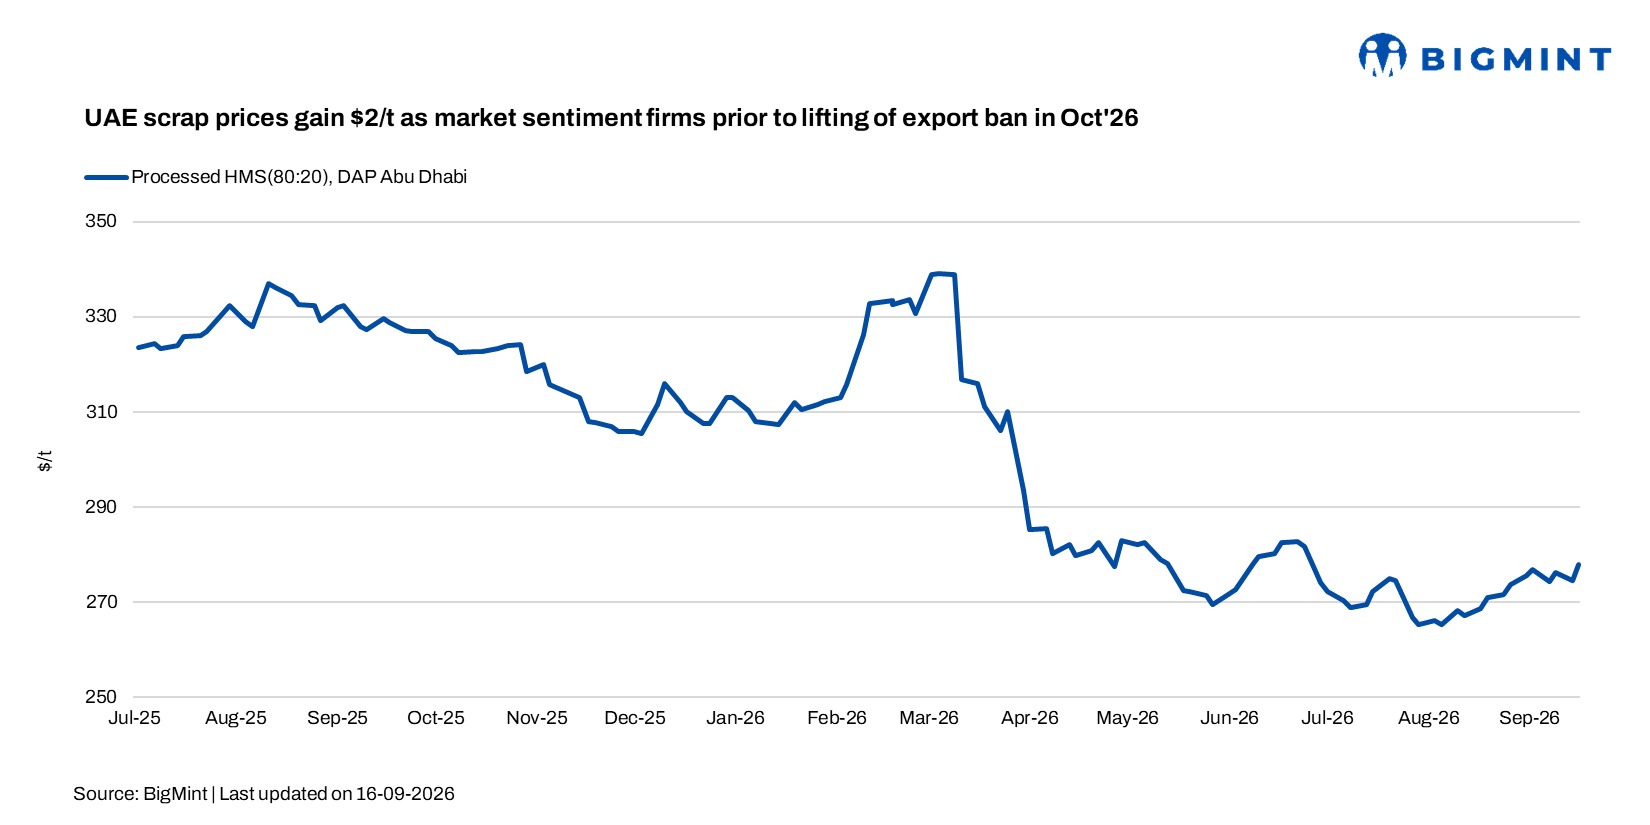
BigMint assessed processed HMS 80:20 at AED 1,021/t ($278/t), up by AED 6/t ($2/t) w-o-w. Workable HMS processed levels remained at AED 1,020-1,025/t ($278-279/t) DAP Abu Dhabi.
A regular supplier to Emirates and AGSI said buying activity has been slower, although HMS processed prices remain stable. Scrap market sentiment was firmer this week, supported by new players entering the collection and trading business and increased export interest as the 8 October scrap export ban-lifting date approaches.
As per a major Dubai-based scrap trader, 3,000-3,500 t of premium shredded scrap was sold at AED 1,140-1,150/t ($310-313/t) DAP Abu Dhabi, while no HMS processed sales were reported.
Rebar market slows
The UAE rebar market became more cash-driven, with traders offering lower prices to buyers willing to make immediate payments. Thin margins have made traders less willing to sell on credit, pointing to cash-flow pressure rather than a major drop in demand. Higher fuel costs are adding to the pressure. Diesel prices rose 12-13% m-o-m to AED 4.3/litre from 1 September.
Traders expect higher diesel costs to eventually push up rebar prices, although the extent of the increase will depend on demand in the coming weeks.
Other Middle East markets
Saudi Arabia saw mixed conditions in the scrap and billet market. Hadeed reduced its scrap buying prices by SAR 70/t ($19/t) effective 11 September, bringing premium scrap to SAR 2,000/t ($533/t) and shredded scrap to SAR 1,995/t ($532/t). However, central and eastern markets remained relatively firm, supported by tight scrap and billet availability.
Earlier this month, Hadeed raised wire rod prices but kept rebar prices unchanged. Concerns over an east-coast billet shortage continue to influence market expectations for October.
Bahrain saw a different trend, with weak demand putting pressure on retail rebar prices. Market participants also cited the Saudi billet shortage as a factor affecting the market outlook.
Outlook
UAE scrap prices are likely to remain supported by increased export interest as the 8 October ban-lifting date approaches, although slower domestic buying could limit gains. Rebar demand, fuel costs, liquidity, and billet import economics will remain key factors for the market in the coming weeks.
Leave a Reply