- Scrap bookings remain limited; comfortable mill inventories
- Steel prices increase by INR 850-1,350/t w-o-w
BigMint’s domestic end-cutting scrap index, tracking the Mandi Gobindgarh market, decreased by INR 100/t d-o-d to INR 42,900/t DAP on 18 Sept 2026.The scrap index rose by INR 1,000/t w-o-w amid moderate steel market sentiments.
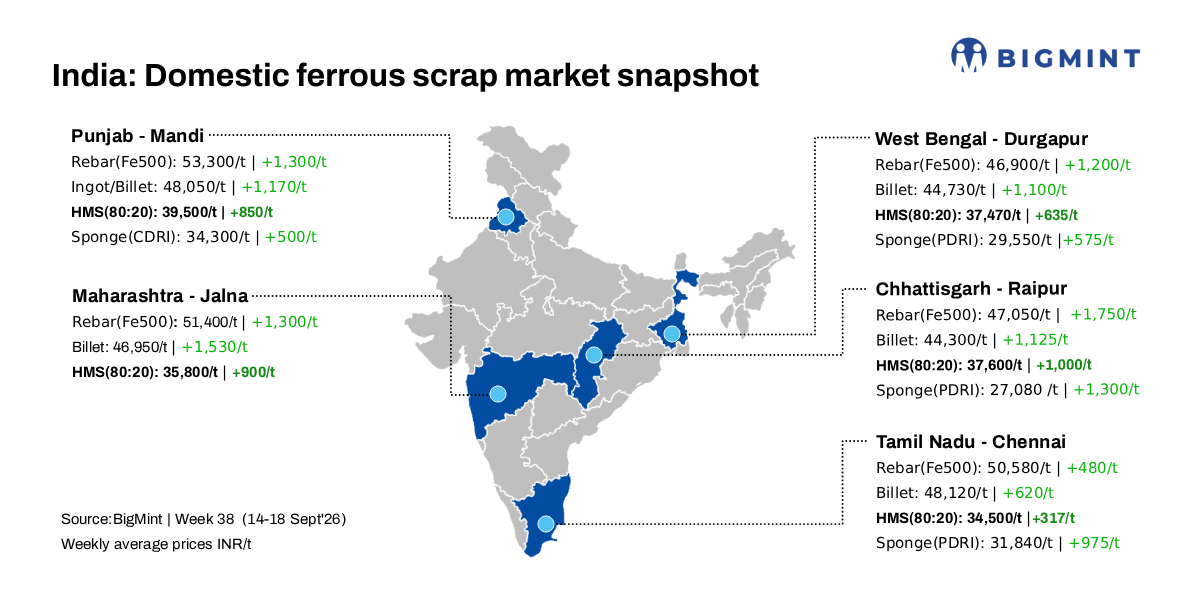
Scrap-to-finished steel prices in Mandi Gobindgarh rose by INR 850-1,350/t w-o-w, supported mainly by continuous gains in finished steel and improved HR strip(patra) demand during mid-week. However, the rise was not backed by strong overall consumption.
Scrap prices have declined over the past three days as increased arrivals from neighbouring regions followed the easing of GST-related checks in Mandi and Ludhiana. Many buyers had already booked material at lower levels during the first week of September, while mills are currently holding comfortable inventories.
As a result, fresh scrap bookings remained limited, with only mills requiring daily material buying in small volumes. Finished steel demand also weakened toward the weekend, keeping market activity cautious.
Overall, the market remains under pressure. Suppliers are accepting lower offers, while mills are avoiding aggressive procurement. The recent price rise was largely finished-steel-led, rather than driven by strong fundamentals in scrap demand.

Raw-material, steel market trends
Sponge iron prices in Mandi remained stable day-on-day at INR 34,300/t DAP as short-term trading activity moderated. Despite the pause, the weekly trend remained positive, with prices gaining INR 500/t, indicating continued underlying support.
In Ludhiana, pig iron prices rose sharply by INR 600/t d-o-d to INR 44,600/t DAP. On a weekly basis, prices increased by INR 1,480/t, reflecting a moderately firm market supported by balanced supply-demand conditions.
In finished steel, Mandi ingot prices eased by INR 100/t d-o-d to INR 48,000/t, while the weekly gain remained strong at INR 1,170/t. Rebar ex-works prices also declined by INR 100/t to INR 53,300/t, but were still up INR 1,300/t WoW, highlighting a firm broader trend despite softer daily trading. HR strip (patra) prices decreased by INR 200/t d-o-d to INR 53,300/t ex-works, while registering a w-o-w gain of INR 1,350/t.

Upcoming scrap auctions

Price highlights
End-cutting to billet spread: In Mandi, the spread between end-cutting scrap and billets stood in the range of INR 4,800-5,300/t.
Domestic vs imported scrap: Imported melting scrap prices at Nhava Sheva Port were assessed at $372/t, approximately INR 38,000/t (inclusive of freight). HMS (80:20) prices in Mumbai climbed by INR 400/t to INR 37,000/t DAP. Indicative prices of shredded from Europe stood at $412/t CFR Nhava Sheva.
Raipur sponge iron-billet spread: The conversion spread (margin) between pellet-based DRI (P-DRI) and steel billets in Raipur stood at INR 15,400/t.

To see BigMint’s melting scrap assessment, pricing methodology and specification documents, click here
To provide feedback on this index or if you would like to contribute by becoming a data partner, please contact – support@bigmint.co
Leave a Reply