- Mining operations to take time to normalise post-monsoon
- Major miner expects prices to decline further by next weekend
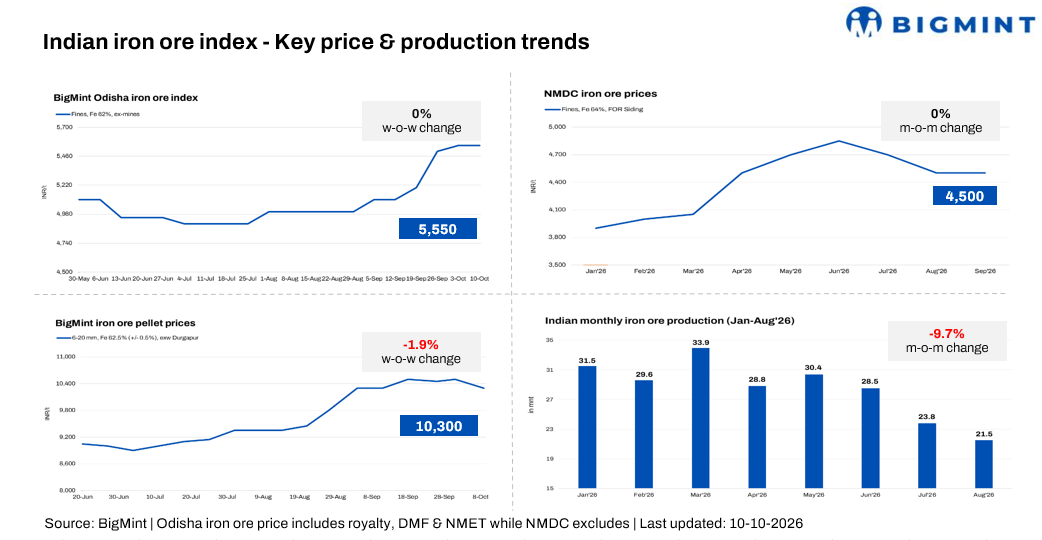
BigMint’s Odisha Fe 62% iron ore fines assessment remained unchanged at INR 5,550/t ($57.4/t) ex-mines in the week ending 10 October 2026, amid weakening domestic prices and subdued market activity.
Prices remained under pressure on limited buying interest and cautious procurement which weighed on trading activity, leaving prices with little immediate support.
“Domestic market is down. Nothing major heard. Monsoons have stopped but it will take time for operations to normalise,” an Odisha-based trader said.
Although the monsoon season has ended, mining operations and dispatches are expected to take time to return to normal levels. The gradual resumption of activities could improve material availability, potentially adding to downward pressure on prices if demand remains weak.
Rationale
- T1: Two (2) deals for Fe 62% fines were recorded during the publishing window, with each assigned a 50% weightage in the index calculation.
- T2: BigMint received sixteen (16) offers and indicative prices under the T2 category (offers, indicative, and bids) in this publishing window. Eight (8) were taken into consideration and given 50% weightage. To check BigMint’s iron ore assessment, pricing methodology, and document, click here.
Weak demand weighs on Odisha pellet, Rourkela C-DRI and rebar prices
- Pellet prices diverge w-o-w on subdued market sentiment: Odisha’s Barbil (Fe 62.5%) pellet prices remained unchanged at INR 9,600/t ($99.2/t) LTW on 9 October 2026, while Durgapur prices fell by INR 200/t ($2.1/t) w-o-w to INR 10,300/t ($106.4/t) ex-works. Market sentiment remained subdued amid cautious buying and limited demand, with the decline in Durgapur reflecting continued price pressure. The near-term outlook remains cautious, with prices likely to depend on steel demand, mill procurement and changes in pellet availability.
- Rourkela C-DRI prices fall w-o-w: Rourkela cold direct reduced iron (C-DRI) prices declined by INR 550/tonne (t) ($5.7/t) w-o-w to INR 30,450/t ($314.7/t) on 10 October, from INR 31,000/t ($320.3/t) a week earlier. The decline reflected subdued market sentiment and continued price pressure amid cautious buying interest. Weakness in the finished steel market and limited procurement by downstream buyers weighed on price momentum. The near-term outlook remains subdued, with prices likely to depend on steel demand, sponge iron market trends and the pace of restocking by buyers.
- Rourkela rebar prices ease w-o-w on soft demand: Rourkela induction furnace (IF)-route rebar prices (12-25 mm) fell by INR 200/t ($2.1/t) w-o-w to INR 56,300/t ($581.8/t) on 10 October 2026, from INR 56,500/t ($583.8/t) on 3 October. The decline reflected subdued market sentiment and cautious buying interest in the finished steel market. Limited demand from construction and infrastructure segments continued to weigh on trading activity, while buyers remained reluctant to make bulk purchases amid uncertain price trends. The near-term outlook remains cautious, with prices likely to depend on a recovery in downstream demand and improved market activity.

Outlook
Market sentiment is expected to remain bearish in the near term, with domestic iron ore prices likely to face further declines amid subdued buying interest and limited trading activity. Although the end of the monsoon season is expected to support a gradual recovery in mining operations and supplies, the pace of normalisation remains uncertain. A major iron ore miner told BigMint, “The market and prices should fall towards the end of next week.”
A sustained recovery in demand and improved trading activity will be key to stabilising prices. Until then, the combination of weak market sentiment, cautious procurement and a gradual normalisation of mining operations could keep Odisha iron ore fines prices under pressure.
Leave a Reply