- South African coal remained firm as tight supply supported offers
- Domestic coal prices rose as monsoon auction constraints limited availability
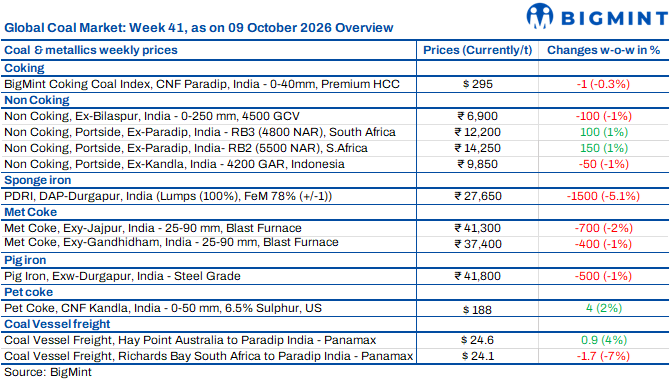
Coal market sentiment remained mixed this week. South African coal stayed firm as tight prompt availability and higher replacement costs supported offers, although weak sponge iron demand limited buying. Domestic coal remained firm amid supply constraints, while ROM shortages kept washed coal prices elevated. Indonesian coal softened on cautious procurement; met coke faced pressure from weaker raw material costs, and expensive petcoke encouraged fuel switching among cement producers.
Indonesian prices ease amid cautious buying
Indian portside Indonesian thermal coal prices softened slightly in the week ended 9 October as weak industrial demand and cautious buying weighed on the market. 5,000 GAR remained at INR 11,800/t at Kandla and INR 11,700/t at Vizag, while 4,200 GAR fell INR 50/t to INR 9,850/t and INR 9,750/t, respectively. 3,400 GAR at Navlakhi declined INR 50/t to INR 7,850/t. Power-plant stocks fell 2% w-o-w to 20.62 mnt, with 87 plants at critical levels, limiting downside. Indonesian export benchmarks rose across grades, but adequate port stocks and softening offers kept Indian buyers cautious.
South African coal prices rise further
South African thermal coal prices strengthened on higher replacement costs and limited supply. Ex-Paradip RB2 (5,500 NAR) rose INR 150/t w-o-w to INR 14,250/t, while RB3 (4,800 NAR) increased INR 100/t to INR 12,200/t. Ex-Vizag, RB2 climbed INR 250/t to INR 14,250/t and RB3 rose INR 250/t to INR 12,250/t. Import offers stood at $135-136/t for RB2 and $115-116/t for RB3. Port stocks rose 0.5% to 18.44 mnt, although several ports recorded drawdowns. Domestic coal remained elevated, while weak sponge iron demand limited buying. PDRI ex-Raipur fell INR 700/t to INR 28,850/t, while ex-Durgapur declined INR 1,500/t to INR 27,650/t.
Domestic coal prices remain firm
Domestic coal prices remained elevated despite mixed movements. Ex-Bilaspur 4,500 GCV coal declined INR 100/t w-o-w to INR 6,900/t, while 5,000 GCV coal remained unchanged at INR 9,000/t as of 6 October. Recent ECL and MCL e-auctions fetched premiums of around 200-300% for selected grades, reflecting strong competition and keeping procurement costs high. However, these elevated costs did not translate into stronger washed coal demand, as downstream buyers became increasingly price-sensitive and restricted purchases to essential requirements. Sellers therefore faced difficulty passing on higher raw material costs amid weaker buying interest.
Washed coal prices rise despite resistance
Indian washed coal prices rose INR 100/t to INR 10,100/t for 38-39% FC (5,000 GCV) FOR Raipur as of 7 October 2026. However, buyers resisted higher prices and limited purchases to essential requirements rather than building stocks. A 10,000 t deal was reported the previous week at INR 9,500/t plus GST, ex-plant Bilaspur, below the latest Raipur assessment. Domestic coal prices remained stable at elevated levels, while high e-auction premiums kept raw material costs firm. The market therefore faced a gap between sellers’ elevated costs and weaker buying interest, limiting the scope for further price increases.
Met coke prices fall amid caution
India’s met coke prices weakened in the week ended 8 October as cautious buying and pressure on steel margins weighed on demand. BF-grade prices fell INR 700/t w-o-w to INR 41,300/t ex-Jajpur and INR 400/t to INR 37,400/t ex-Gandhidham; foundry-grade coke at Rajkot declined INR 200/t to INR 39,200/t. Deals included 5,000 t at INR 44,000/t ex-works in eastern India and 2,000 t at INR 41,500/t. Buyers anticipated further corrections, while Indonesian supply disruptions limited downside. Australian PHCC fell $1/t to $271/t FOB. Durgapur pig iron declined INR 200/t to INR 41,850/t, despite firmer export activity. Higher coke-oven utilisation was expected to improve domestic supply, while Indonesian disruptions supported prices.
US NAPP coal prices remain elevated
US NAPP coal offers remained firm in early October, at around $185/t CFR India, as limited prompt availability supported prices. A major supplier had reportedly committed its availability through January. Freight from the US East Coast to India was indicated at around $51.75/t. Indian retail offers stood at INR 18,500-19,500/t, while Kandla and Tuna stocks totalled around 99,533 t. Weekly lifting reached 36,895 t. Around 0.84 mnt of retail or mixed-use cargoes and 0.56 mnt for industrial users were scheduled to arrive in October. Timely arrivals could ease retail supply pressure, although buyers continued to procure mainly as needed.
Petcoke prices prompt fuel switching
Imported petcoke offers remained high in early October, at around $185/t CFR west coast India, with some east-coast offers reaching $190/t. Buyer interest remained weaker, with some target prices in the $170s/t, as elevated replacement costs encouraged cement producers to use existing stocks and increase domestic coal consumption. US Gulf 6.5% sulphur petcoke prices and freight costs had strengthened, supporting sellers’ offers. Some producers also considered alternative imported coal grades, including higher-sulphur South African material, where plant specifications allowed. However, petcoke remained valuable for its high heat value and low ash, keeping fuel-blend economics central to purchasing decisions.
Coal freight markets show mixed trends
India-bound coal freight markets remained mixed in the week ended 9 October. Australia-Paradip Panamax rates rose $0.9/t w-o-w to $24.6/t, while RBCT-Paradip fell $1.7/t to $24.1/t. East Kalimantan-Navlakhi Supramax increased $0.3/t to $24/t, while South Kalimantan rose $0.3/t to $23/t. Australian coal demand supported Panamax, while limited South African fixtures weighed on Atlantic rates. The BDI fell 4.5% to 2,973, although Panamax and Supramax indices increased. Singapore VLSFO rose 6.1% to $896.5/t, while Brent futures gained 3.7% to $104.28/bbl, increasing voyage cost pressure.
Leave a Reply