- Improved dispatches and availability weigh on market sentiment
- Buyers await OMC auctions amid falling sponge iron and pellet prices
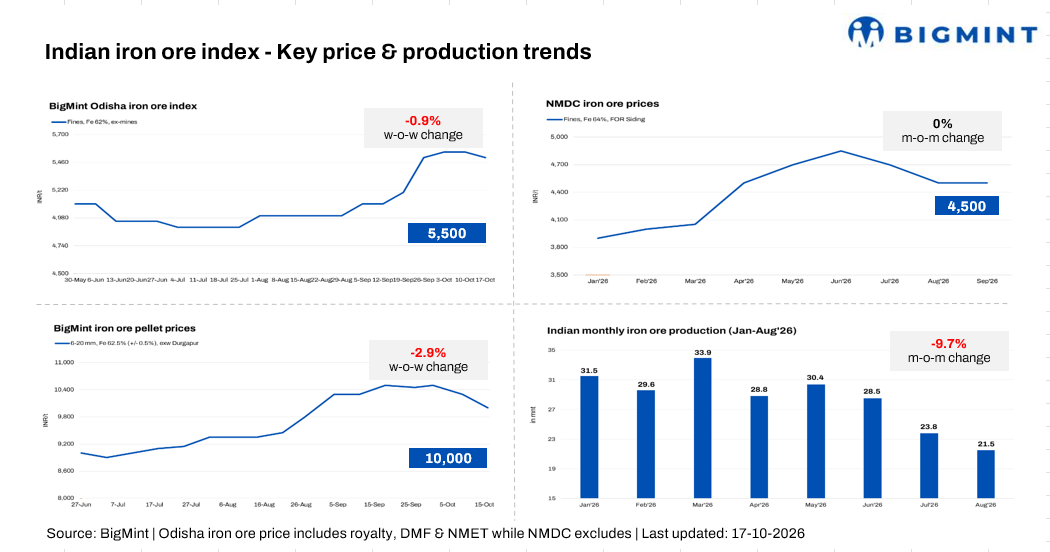
Odisha iron ore fines prices remained largely stable w-o-w in the week ending 10 October 2026, with BigMint’s assessment for Fe 62% fines decreased marginally by INR 50/tonne (t) ($0.5/t) at INR 5,500/tonne (t) ($57.9/t) ex-mines.
Improved dispatches and ore availability, coupled with lower prices for pellets and sponge iron, have weighed on market sentiment, while buyers remain cautious amid subdued steel demand.
“Dispatches and iron ore availability have improved in Odisha, with merchant miners holding adequate material. Meanwhile, lower pellet and sponge iron prices, along with reduced OMC auction offers, have further weighed on market sentiment”, a source told BigMint.
On the other hand, a major iron ore seller highlighted, “I have limited high-grade iron ore available for sale; however, subdued demand continues to constrain market activity.”
The recent price reductions in Odisha Mining Corporation’s (OMC) auction offers have added to the pressure. According to auction notices dated 22 October 2026, the miner lowered iron ore fines base prices by around INR 150/t ($1.6/t) from the previous month, while calibrated lump ore (CLO) prices were reduced by INR 50-450/t ($0.5-4.7/t), depending on grade and source. The cuts follow a decline of up to INR 1,500/t ($15.8/t) in eastern India’s sponge iron and billet prices over the preceding week.
Market participants are awaiting the upcoming OMC auction results to gauge buying interest and bid premiums. The auction offers 1.43 million tonnes (mnt) of fines, including 1.413 mnt of regular fines and 30,000 t of sub-grade material, alongside around 0.731 mnt of calibrated lump ore.
Rationale
- T1: One (1) deal for Fe 62% fines was recorded during the publishing window, carrying a 50% weightage in the index calculation.
- T2: BigMint received eleven (11) offers and indicative prices under the T2 category (offers, indicative, and bids) in this publishing window. Seven (7) were taken into consideration and given 50% weightage. To check BigMint’s iron ore assessment, pricing methodology, and document, click here.
Why Odisha iron ore prices are under pressure?
- Weak downstream demand weighs on Durgapur prices, while Barbil remains stable: Odisha’s Barbil (Fe 62.5%) pellet prices remained unchanged at INR 9,600/t ($99.2/t) LTW on 16 October 2026, while Durgapur prices declined by INR 300/t ($3.2/t) w-o-w to INR 10,000/t ($105.3/t) ex-works, marking a more than one-month low. Market sentiment remained subdued amid weak downstream demand and pressure from declining sponge iron and billet prices, which continued to weigh on pellet buyers’ purchasing appetite. While prices in Barbil held steady, the decline in Durgapur reflected persistent weakness in the eastern Indian pellet market, with buyers remaining cautious about fresh procurement.
- Weak steel demand and falling billet prices weigh on Rourkela C-DRI prices: Rourkela C-DRI prices declined by INR 950/t ($10/t) w-o-w to INR 29,500/t ($310.6/t) on 17 October 2026, from INR 30,450/t ($320.6/t) a week earlier. Market sentiment remained weak amid subdued finished steel demand and continued pressure on billet prices, which reduced buyers’ willingness to procure at higher levels. Buyers remained cautious, prioritising need-based purchases amid limited visibility on near-term demand and persistent pressure on margins across the steel value chain.
- Subdued buying weigh on Rourkela rebar prices: Rourkela induction furnace (IF)-route rebar prices (12–25 mm) declined by INR 300/t ($3.2/t) w-o-w to INR 56,000/t ($589.7/t) on 17 October 2026, from INR 56,300/t ($592.9/t) on 10 October. Market sentiment remained subdued amid sluggish construction-linked demand and cautious procurement by buyers. The decline in semi-finished steel prices, coupled with pressure on steelmakers’ margins, further dampened trading activity. Buyers continued to adopt a need-based purchasing approach, limiting the scope for a near-term price recovery.

Outlook
Odisha iron ore prices are expected to remain range-bound to weak in the near term amid subdued downstream demand, pressure on sponge iron and billet prices, and improved material availability. Buyers are likely to continue need-based procurement.
The upcoming OMC auction will be a key market indicator, with bid levels and booking volumes likely to influence private miners’ offers. A sustained price recovery will depend on improved steel demand and stronger buying interest.
Leave a Reply