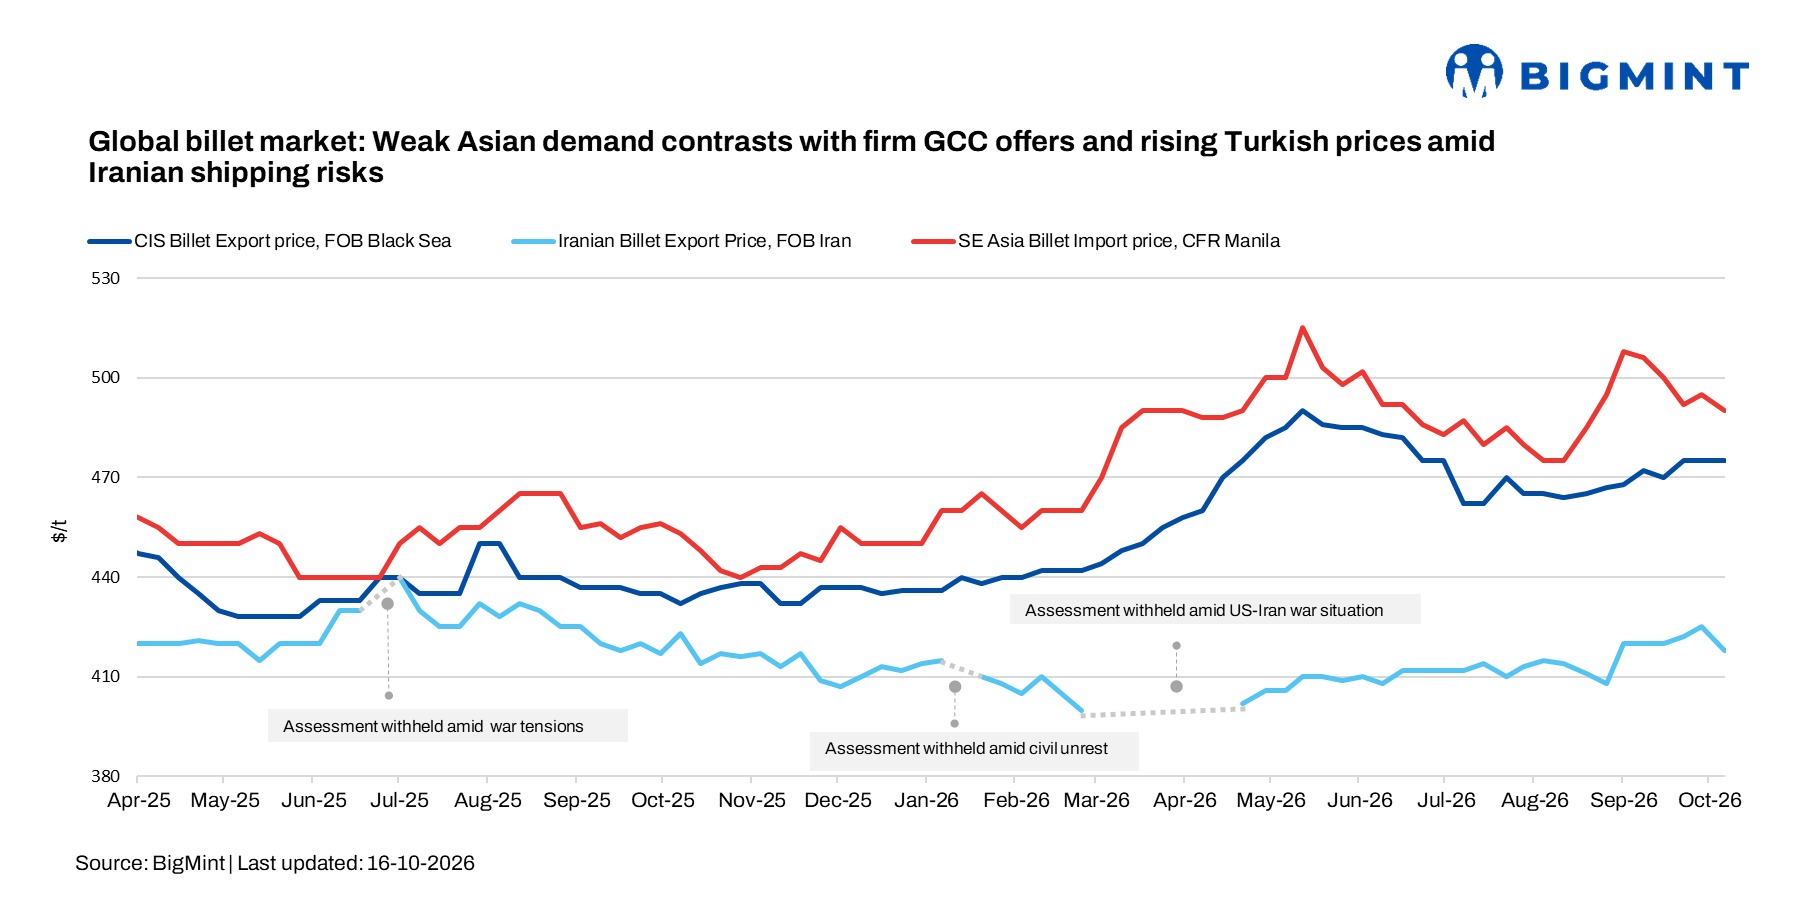
- Asian buyers remain cautious amid weak demand and high import costs.
- Iranian export activity improves despite shipping and security challenges.
Global billet markets moved in different directions during the week ending 16 October 2026. Trading remained slow in Asia as buyers avoided fresh purchases, while supply shortages and shipping difficulties continued to affect the Middle East. In Turkiye, domestic billet prices increased, but import deals remained limited because buyers and sellers could not agree on prices.
Chinese billet export offers remained at $464-465/t FOB China, supported by rising costs. Indonesian producers lowered December-shipment offers to $470-475/t FOB to attract buyers. In Iran, producers concluded several export tenders, with reported sales around $414-417/t FOB, although shipping problems continued to restrict trade.
Egypt remained under pressure from limited billet imports and high procurement costs. Several re-rollers reduced or stopped production because they could not secure enough affordable raw material. Meanwhile, Turkish domestic billet prices increased as import availability remained constrained.
Asia: Billet trade remains slow amid weak demand
Asian billet and rebar markets remained largely stable during the week, as buyers stayed cautious amid weak downstream demand and limited firm bids. Chinese export billet offers were heard at $464-465/t FOB China, while the assessed price stood at $463/t FOB on 15 October. Traders reported limited overseas inquiries and little improvement in buying interest.
In Manila, tradable values for 5SP 150 mm billet remained below $490/t CFR. Russian-origin billet was offered below $495-500/t CFR, providing an alternative to Chinese material.
A Southeast Asia-based trader source said, “We heard a few deals for 5SP billets at $483-485/t CFR in the Philippines and Indonesia for mid- to late-December shipment, with the total volume estimated at 70,000-80,000 tonnes across both destinations. Vietnamese buyers continued to target $475-480/t CFR, but no deals were concluded at these levels. GCC buyers remained silent, while Turkish buyers preferred to wait for a possible correction in Chinese prices.”
In Indonesia, a major steelmaker lowered its December-shipment billet offer by $4-5/t to $472-475/t FOB to attract export orders, reflecting continued efforts to secure sales amid subdued regional demand.
Rebar trading also remained slow. Chinese B500B-grade rebar offers were reported at $520-530/t CFR Hong Kong, with tradable values around $510-515/t CFR. In Singapore, Malaysian-origin rebar offers stood at $520-525/t CPT, while Chinese material was offered at around $520/t against bids of $510/t.
In Vietnam, mills increasingly turned to domestic scrap because it was cheaper than imported raw materials. Deep-sea bulk scrap was reported at $390-400/t CFR Vietnam, compared with Indonesian billet at around $490/t CFR Haiphong.
Chinese billet prices fell by RMB 20/t ($3/t) w-o-w to RMB 2,940/t ($440/t) on 16 October, from RMB 2,960/t ($443/t) on 9 October. SHFE rebar futures declined by RMB 23/t ($3.44/t) to RMB 3,074/t ($459.52/t), while billet export offers rose by $4/t to $464/t FOB.
Turkiye and CIS: Domestic billet prices increase
Russian billet offers stood at $520-525/t CFR Turkiye against buyer targets of $515-520/t, with no deals reported. Baltic-origin material was indicated at $525-530/t CFR, while Black Sea suppliers remained largely absent.
Turkish import billet prices rose to $520-525/t CFR on 8 October, up $8/t at the lower end week on week. Domestic billet prices increased to $560-580/t ex-works, rising by $20/t at the lower end and $10/t at the upper end.
Turkiye was expected to receive 150,000 tonnes of billet and 250,000 tonnes of hot-rolled coil from Asia during October. The cargoes had reportedly been purchased in June but were delayed. Meanwhile, Russian domestic steel sales fell 19% month on month to 73,000 tonnes in September.
Iran: Export tenders conclude despite shipping problems
Iranian billet export activity improved, with producers in Khuzestan and Chadormalu reportedly selling billet at $417/t FOB and $414/t FOB, respectively. A reported sale at $425/t FOB by a producer in Iran was questioned by market sources, who suggested it may involve higher-alloy material. A producer in southern Iran launched a 20,000 t tender, due on 19 October, targeting around $420/t FOB Bandar Abbas.
Despite renewed tender activity, high freight costs and security risks around the Strait of Hormuz weighed on exports. The weekly export price assessment eased to $415/t FOB from $415-420/t. Domestic FCA offers rose by $20-35/t to $420-440/t, while buyers targeted around $410/t.
On Iran’s domestic exchange, the average billet price fell by IRR 11,540/kg (1.34%) w-o-w to IRR 848,610/kg, excluding VAT. Sales totalled 80,000 tonnes down around 10,000 t w-o-w. The highest price reached was IRR 919,430/kg. The average price equated to $471/t exw at the official exchange rate and $331/t at the free-market rate.
GCC billet offers remain above Asian prices
GCC-origin billet was offered at $650-660/t CPT Jebel Ali, compared with Chinese offers at around $600/t CPT. However, security risks and longer delivery times made Asian cargoes difficult to execute. The import price assessment remained at $640-660/t CPT during mid-week, largely stable w-o-w.
Some buyers were negotiating larger volumes with Asian suppliers while securing smaller parcels from GCC producers. A UAE-based billet producer also received active conformity approval for square billet feedstock used to produce BS 4449 Grade B500B rebar. The producer has a reported annual billet capacity of 300,000 tonnes.

Leave a Reply