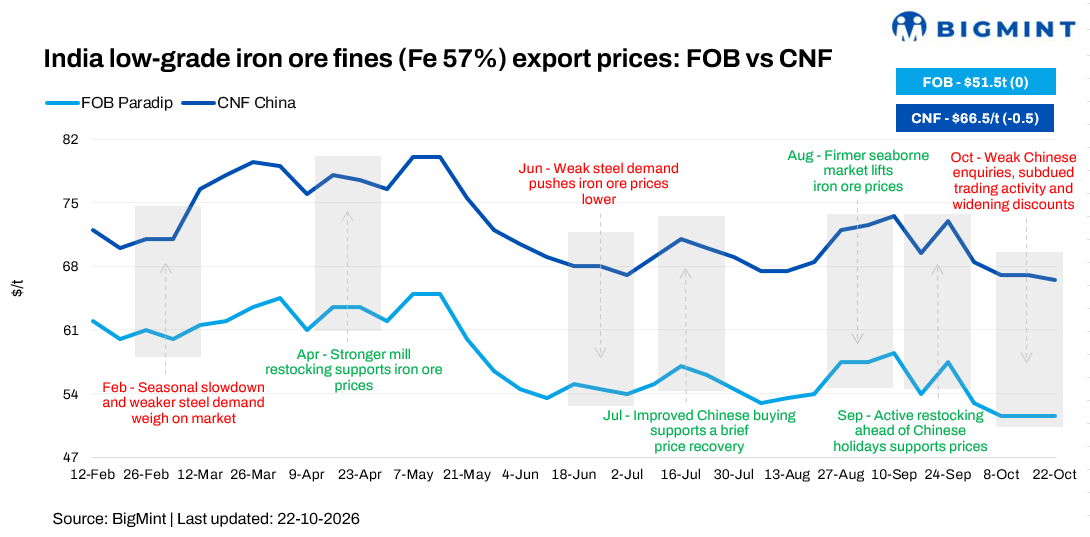
- Export enquiries weak amid buyer-seller mismatch
- Freight and port stocks weigh on market sentiment
Indian low-grade iron ore fines (Fe 57%) export prices held steady w-o-w on 22 October, but the unchanged assessment masked continued weakness in market activity. Exporters faced limited buying interest from China, while freight costs and widening discount expectations made deals increasingly difficult to conclude. Despite stable price indications, the absence of fresh transactions pointed to a market struggling to find a workable price level.
Indicative prices for Indian iron ore fines (Fe 57%) stood at at $51.5/tonne (t) FOB east coast, equivalent to $66.5/t CFR China. Market participants reported subdued trading activity, limited fresh export enquiries and a persistent gap between buyers’ and sellers’ price expectations.
Export market sentiment remained weak, with participants reporting little change in market conditions over the week. Domestic demand was also described as subdued amid festive-season activity, while Chinese buyers remained largely inactive.
“Nothing has changed in the export market. Prices are unchanged,” said a trader to BigMint.
Trading activity was reported around $50-51/t FOB east coast, but deals remained limited as exporters and buyers stayed apart on price expectations. Another trader mentioned, “Activity remained subdued, with limited firm enquiries and transactions.”
A source informed, “Prevailing prices are commercially unviable for Indian exporters. Indian players were unlikely to close deals at the indicated levels, citing a discount of around 19%.”
Freight costs and inventory pressures added to the cautious outlook as few sources told, “Port stocks were building up, while older contracted cargoes continued to ship out. Discounts could widen to 20%, although no deal had been concluded.”
Rationale
- No deals were reported during the current publishing window; consequently, T1 trades received 0% weightage in the index calculation.
- BigMint received sixteen (16) indicative price inputs, of which ten (10) qualified as T2 inputs and accounted for the 100% weightage.
Meanwhile, Indian iron ore export shipments rose sharply by 472.1% w-o-w to 3,45,097 t during 10-16 October 2026, compared with 60,500 t in the previous week (3-9 October), weekly vessel line-up data maintained with BigMint shows. The increase was primarily driven by fresh shipments from Paradip, which handled 1,22,097 t through Rungta Mines, and Dhamra, which recorded 1,10,000 t through Patnaik Steel and Auroglobal Comtrade.
Gopalpur also contributed 53,000 t through Kashvi Power & Steel, while Mormugao shipped 60,000 t through Vedanta. In contrast, Krishnapatnam recorded no shipments during the week, after exporting 60,500 t in the previous week. Destination-wise, shipments to China totalled 1,68,000 t.
Domestic iron ore prices outperform export realisations
The spread between domestic and export realisations widened to around INR 1,082/t ($11.4/t) this week, as export realisations remained under pressure while domestic low-grade iron ore prices held steady. Export realisations stood at around INR 2,423/t ($25.6/t), compared with domestic prices of INR 3,600/t ($38/t) ex-mines.
The widening gap highlights the weaker competitiveness of exports relative to domestic sales, potentially encouraging miners to prioritise local buyers where demand and logistics permit.

Prices diverge as modest spot gains contrast with weaker futures
Global benchmark iron ore (Fe 61%) prices edged up by $1/t w-o-w to $91/t CFR China on 21 October 2026, from $90/t on 14 October, indicating a modest recovery in the seaborne market. However, the marginal increase suggests that buying interest remained insufficient to trigger a stronger price rally. Market sentiment continues to hinge on Chinese steelmakers’ procurement activity, steel demand and inventory levels, with cautious purchasing potentially limiting further gains.
January 2027 iron ore futures on the Dalian Commodity Exchange (DCE) declined by RMB 4/t ($0.6/t) w-o-w to RMB 669/t ($100.2/t) on 22 October, reflecting a modest easing in market sentiment. The decline suggests continued caution among market participants, with prices facing pressure from uncertain Chinese steel demand and procurement activity.
Outlook
Indian low-grade iron ore export prices are likely to remain under pressure in the coming week amid subdued Chinese buying interest, limited fresh enquiries and a persistent gap between buyers’ and sellers’ price expectations. With export realisations trailing domestic prices and freight costs weighing on competitiveness, exporters may need to offer deeper discounts to secure deals, although sustained price declines will depend on changes in overseas demand and confirmed trading activity.
Leave a Reply