- Monsoon disruptions, festive holidays weigh on market sentiment
- Rebar prices fall by INR 200/t w-o-w, billet prices remain stable
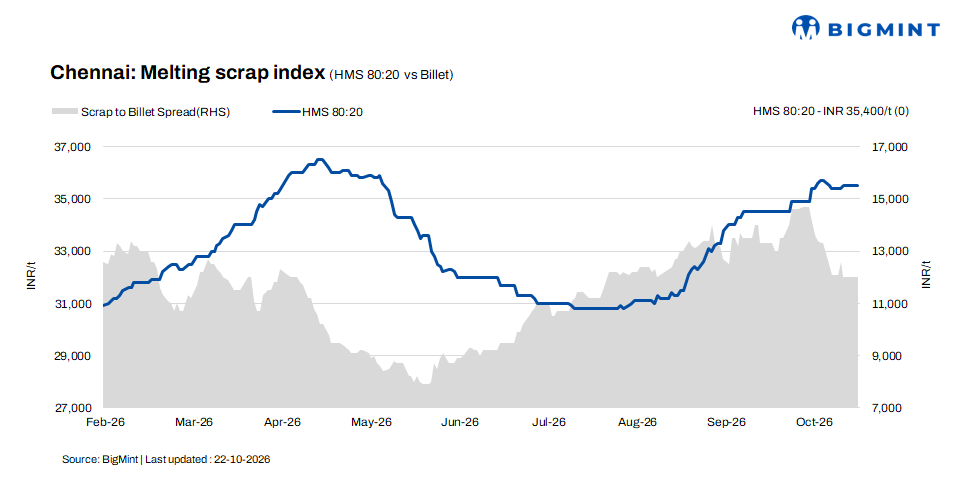
HMS (80:20) scrap prices in Chennai remained stable at INR 35,400/t, with no change on a d-o-d or w-o-w basis, according to BigMint’s latest assessment. Billet prices also held steady at INR 47,500/t across both periods. In contrast, rebar prices declined by INR 200/t d-o-d and w-o-w to INR 52,300/t, indicating comparatively softer sentiment in the finished steel market.
Imported, domestic market trends
Market participants reported that Australia-origin shredded scrap was offered at $382-385/t CFR Chennai, while HMS (80:20) was quoted at $362-365/t CFR. Buyers remained cautious, with bids trailing prevailing offers by around $10-15/t, resulting in a significant bid-offer gap. Despite the shortage of imported bookings, domestic scrap remained the more economical procurement option, limiting buying interest for imported material and keeping import trade activity muted in the Chennai market.

Domestic HMS (80:20) scrap prices remained largely stable at INR 35,000-36,000/t, with transaction prices largely influenced by payment terms. Buyers offering immediate payment were quoted INR 35,000-35,500/t, whereas extended payment terms attracted prices of INR 35,500-36,000/t.
Supplier offers were broadly stable, and most deals were concluded within these levels. Market participants remained cautious, factoring in liquidity availability and payment flexibility while negotiating transactions. Procurement continued to be driven by individual requirements and buyers’ cash-flow positions.
Buyer-supplier sentiments
A mill representative shared with BigMint that steel trading activity has slowed ahead of the Deepawali festival, resulting in limited market movement. He expects finished steel prices to decline marginally in the near term amid subdued demand and cautious buying. The onset of the monsoon season has further weakened market sentiment by disrupting logistics and dampening construction activity, thereby affecting downstream steel consumption.
Meanwhile, the Ayudha Pooja and Dussehra festivals earlier this week affected scrap supply to mills, creating some constraints in material availability. In response, mills may adjust their scrap procurement prices based on immediate requirements and prevailing supply conditions. Market participants are likely to remain cautious, with purchasing activity largely driven by production needs and price competitiveness. The near-term direction of scrap prices will depend on finished steel demand, material availability and mills’ procurement strategies.
A leading scrap supplier told BigMint that HMS (80:20) scrap prices in Chennai are currently trading in the range of INR 35,000-36,000/t, depending on payment terms. The onset of the monsoon season is expected to slow steel trading activity in the coming days, as construction activity and material movement may be affected.
With Deepawali approaching, market participants anticipate further softness in finished steel prices amid subdued demand and cautious buying. These factors are likely to keep market sentiment under pressure, with mills expected to follow requirement-based procurement strategies. Scrap prices may remain vulnerable to further corrections if finished steel demand weakens, although supply constraints could provide some near-term support.
Outlook
Market participants anticipate scrap prices to hold steady or register a slight dip of nearly INR 200-500/t in the coming days. With the Deepawali holidays ahead, reduced trading in finished steel is expected to keep overall market sentiment subdued and may exert mild downward pressure on prices.
Leave a Reply