- Coal stocks at Indian ports rise w-o-w
- Festive slowdown, weak sponge iron margins limit buying
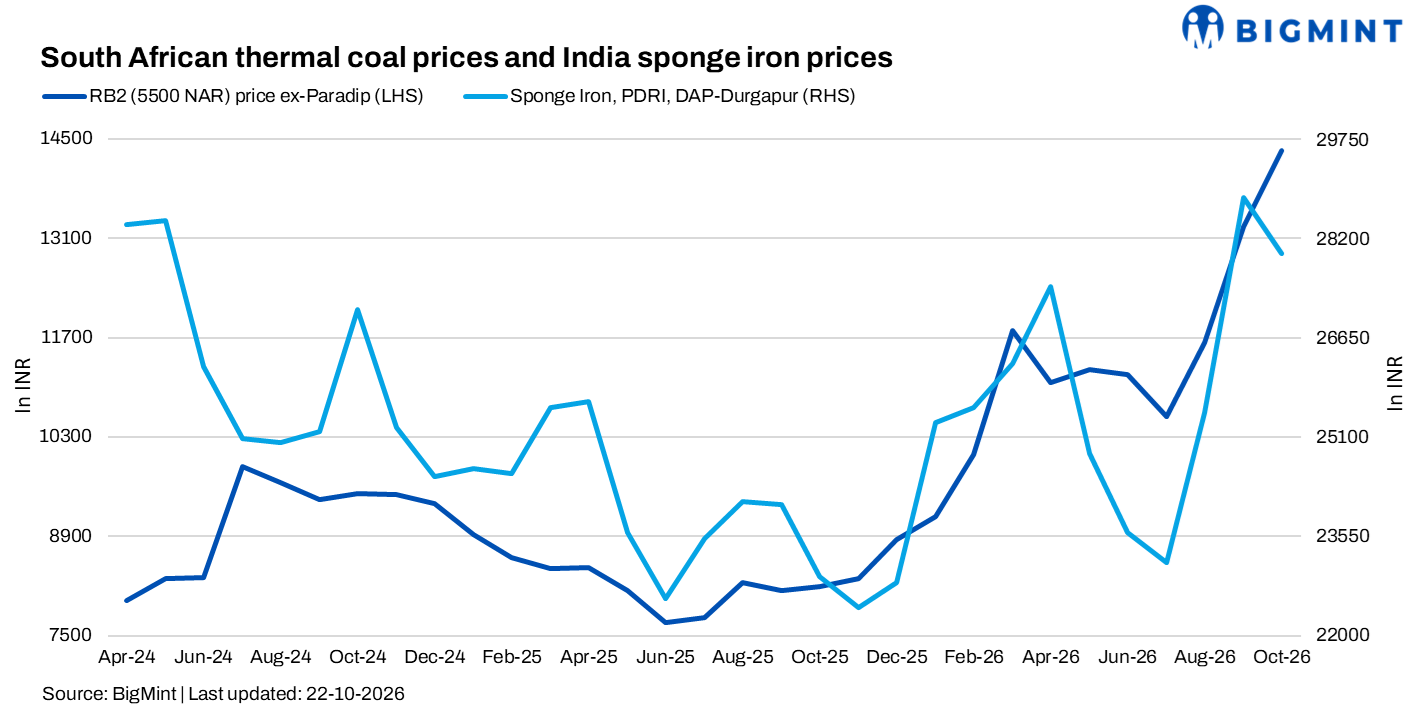
South African thermal coal prices increased at Indian ports as of 22 October 2026, supported by firmer export indications and elevated replacement costs. However, festive season trading remained subdued, with buyers cautious after earlier bookings and limited fresh spot offers. Despite stronger prices, moderate demand and pressure on sponge iron margins limited immediate buying interest.
Portside prices strengthen across key locations
At Paradip, South African RB2 (5,500 NAR) prices rose INR 200/t ($2.12/t) w-o-w to INR 14,550/t ($154.05/t) as of 22 October, while RB3 (4,800 NAR) increased INR 250/t ($2.65/t) to INR 12,600/t ($133.40/t). At Vizag, RB2 gained INR 200/t ($2.12/t) to INR 14,500/t ($153.52/t) and RB3 rose by INR 12,500/t ($132.34/t).
Prices at Krishnapatnam on 19 October were assessed at INR 14,500/t ($153.52/t) for RB2 and INR 12,600/t ($133.40/t) for RB3. At New Mangalore, RB2 stood at INR 14,500/t ($153.52/t) and RB3 at INR 12,500/t ($132.34/t).
Market participants reported limited fresh offers during the festive period, with sellers maintaining firm indications. Spot availability remained tight, while the gap between elevated offers and lower buyer bids restricted deal-making. Some buyers were also relying on previously booked cargoes rather than committing to additional purchases.
Export offers remain firm amid global competition
South African export prices strengthened, with 5,500 NAR coal indicated at around $117-118/t FOB Richards Bay Coal Terminal (RBCT), while 4,800 NAR coal was reported at $98-100/t FOB. Market indications for higher-grade RB1 and RB2 cargoes also remained elevated, although buyer bids were lower than offers.
Competition for South African coal from buyers in other markets, including Turkiye, Japan and South Korea, was reported to be supporting seller confidence. Concerns over energy supply and the availability of alternative origins added to the competition for cargoes.
Market participants expected prices to remain firm into January 2027, supported by elevated petcoke and US coal costs and demand from power and cement consumers. However, these expectations remained subject to actual buying activity and changes in export availability.
Festive slowdown limits Indian buying interest
Despite stronger portside prices, Indian demand remained moderate. The festive period reduced market participation, and no fresh offers were reported in the market through 21 October. Buyers largely adopted a wait-and-watch approach as sellers held firm offers and procurement remained selective.
Some consumers had already booked cargoes and were using existing inventories, reducing the urgency for fresh purchases. The difference between high offers and lower bids further constrained spot transactions.
The market therefore faced contrasting signals: firmer international replacement costs supported prices, but limited immediate buying restricted trading activity. The extent to which higher export prices translate into further Indian portside gains will depend on fresh enquiries after the holiday period.
Sponge iron market shows mixed regional movement
Sponge iron prices remained mixed across regions. BigMint’s Raipur PDRI assessment remained rangebound at INR 28,050/t ($296.98/t) as of 22 October, while Durgapur PDRI increased INR 950/t ($10.06/t) to INR 28,550/t ($302.28/t).
In eastern India, improved sentiment and healthy enquiries supported higher offers. However, limited bulk purchases and cautious buying prevented stronger enquiries from consistently converting into deals. Festive holidays also kept trading activity subdued.
In parts of southern India, sponge iron producers faced margin pressure from high iron ore, pellet and coal costs. This weakened the incentive to procure imported coal aggressively, with some consumers reportedly considering greater use of Indonesian coal in blends. These conditions limited the immediate demand response to rising South African coal prices.
Domestic coal stability and port stocks shape procurement
Ex-Bilaspur domestic coal prices remained unchanged w-o-w as of 21 October, with 4,500 GCV coal at INR 6,200/t ($65.64/t) and 5,000 GCV coal at INR 8,700/t ($92.11/t). The pause followed the previous week’s sharp declines, leaving buyers to assess domestic coal’s competitiveness against imported material.
Meanwhile, BigMint’s week 42 assessment showed total coal inventories at covered Indian ports rising 2% to 19.06 mnt during 11-17 October. Non-coking stocks increased to 13.69 mnt, while coking coal inventories recovered to 5.37 mnt.
However, replenishment was uneven. Mundra and Mangalore led the non-coking stock build, while Kandla, Navlakhi, Tuna and Krishnapatnam recorded drawdowns. Higher national inventories therefore did not necessarily translate into improved availability at every receiving location.
Market sentiment
South African coal prices strengthened at Indian ports as export offers and replacement costs remained firm. However, festive-season inactivity, limited fresh offers and buyers’ reliance on existing cargoes kept spot trading subdued. Mixed sponge iron price movements and margin pressure continued to restrain procurement, while stable domestic coal prices and uneven port inventories shaped buyers’ fuel choices.
Leave a Reply