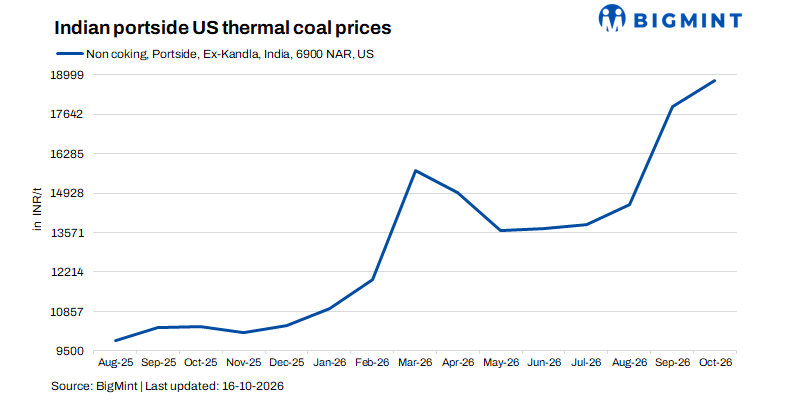
- Retail prices soften as western port stocks recover
- Cement commitments limit freely available spot supply
India’s US thermal coal import market is becoming more balanced as fresh cargoes improve western port availability. Retail NAPP prices have eased from early-October highs, while the October-November vessel list includes both Northern Appalachian and Illinois Basin coal.
Demand remains divided between cement producers seeking high-energy, low-ash fuel and retail consumers assessing affordability. Incoming cargoes could ease immediate scarcity, but expensive replacement supplies and limited forward producer availability continue to support sellers.
Western port prices soften
Market feedback on 13-16 October placed the main cluster of NAPP retail indications around INR 18,200-18,800/t ex-port. Approximately INR 18,500/t was reported at Kandla on 16 October.
These levels compare with indications around INR 19,000-19,500/t in early October. Some higher offers persisted during 14 October, showing that pricing remained dispersed.
Fresh arrivals and buyer resistance have softened sentiment. Consumers are considering domestic coal or blended purchases rather than accepting every higher offer. Kandla has the clearer price evidence. Tuna is an important part of the same western retail supply pool, but the available information does not establish a separate, consistently assessed Tuna price.
Stocks improve from September lows
Tracked Kandla and Tuna retail inventories reached 107,177 t on 12 October, comprising 31,652 t at Kandla and 75,525 t at Tuna. That compared with 99,533 t on 5 October. Detailed dispatch statements show weekly lifting increasing to 42,787 t from 36,895 t.
The recovery follows a weak September. The historical retail series recorded monthly lifting of 68,709 t, down approximately 68% y-o-y, and closing inventories of 71,122 t.
These figures cover the tracked NAPP/ILB retail market, rather than all US coal held in India. September’s low lifting reflects a combination of availability, prices and purchasing conditions.
Brick kiln buying could strengthen as operations resume, but elevated prices encourage smaller purchases and greater domestic-coal blending.
Cement buyers evaluate NAPP and ILB
NAPP remains relevant to cement producers because of its high energy content and relatively low ash. It can replace part of the petcoke requirement or help balance higher-ash domestic coal.
However, imported NAPP is also expensive. Earlier October delivered indications around $185/t illustrate why cement buyers continue to evaluate domestic coal and other imported grades.
ILB is appearing in the lineup as a supplementary US sourcing option. It is not interchangeable with NAPP: cargo-specific energy content, ash and sulphur determine its value to individual consumers.
Identified imports and cargoes at port
The available records identify completed October movements for Nuvoco Vistas and Chettinad Cement, alongside NAPP cargoes discharging or awaiting discharge for JSW and UltraTech.

The two recorded imports total 143,003 t. A further 224,413 t of identified NAPP was explicitly reported at port, including 151,329 t for JSW and 73,084 t for UltraTech.
The retail records also identify October arrivals on Siboney M and Anglo Alexandria for SSOE. However, the dispatch statement does not provide sufficiently reconciled original cargo quantities to include them in a verified import total.
Identifiable forthcoming receivers
Excluding the three vessels explicitly reported at port, the updated list contains approximately 2.25 mnt of scheduled US coal across October and November.

UltraTech is the largest individually identified forthcoming receiver, with 410,000 t across Santa Sophia, Star Zulu, Horizon II and Flag Marina. Shree Cement’s 175,000 t comprises Pinchat and MSC Magali. My Home is identified against 75,000 t on Agri Ocean, while Tata Power is listed for 110,000 t on Magsenger 16.
The explicit ILB cargoes are CL Yichun, carrying 79,590 t for Adani at Krishnapatnam with an 18 October date, and RB Leah, carrying 75,000 t for SSOE at Kandla-Tuna on 22 November.
Including the 224,413 t explicitly at port, the October-November list totals 2.475 mnt: 2.321 mnt of NAPP and 0.155 mnt of ILB. It is a combined at-port and scheduled list, not a completed-import total.
Forward producer availability remains tight
According to the latest commercial information supplied, Core Natural Resources is sold out through March 2027 and is accepting new bookings from April, or Q2 2027.
Its highest achieved Q1 2027 price was $128/t FOB. This is a reported forward transaction level, rather than a current spot assessment or an April offer.
BigMint assessment
Incoming US cargoes should ease immediate western port availability, but industrial commitments and joint allocations will determine how much reaches retail buyers. The market is moving towards a test of demand at high prices. Cement fuel substitution, brick-kiln purchasing and discharge progress will determine whether retail prices soften further.
Tight forward producer availability, meanwhile, means improved port stocks need not translate into cheaper replacement cargoes.
Leave a Reply