- E-auction demand strengthens, with allocation at 72% and premiums at 94%
- Post-monsoon restocking to support demand; high premiums may limit participation
Coal India Ltd (CIL) subsidiaries recorded a significant improvement in e-auction performance in September 2026, with 9.36 million tonnes (mnt) allocated, up 13% m-o-m from 8.28 mnt in August. Meanwhile, the quantity offered declined sharply by 38% m-o-m to 13.02 mnt from 21.07 mnt. Consequently, the overall allocation rate rose to 72% in September from 39% in August, indicating stronger absorption of the reduced auction availability.
This was considerably higher than the 40% allocation rate recorded during April-September FY27, indicating a notable improvement in buyer participation during the month. At the same time, the average premium over notified prices increased to 94% in September, compared with 59% in August.
September auction performance shows stronger market participation
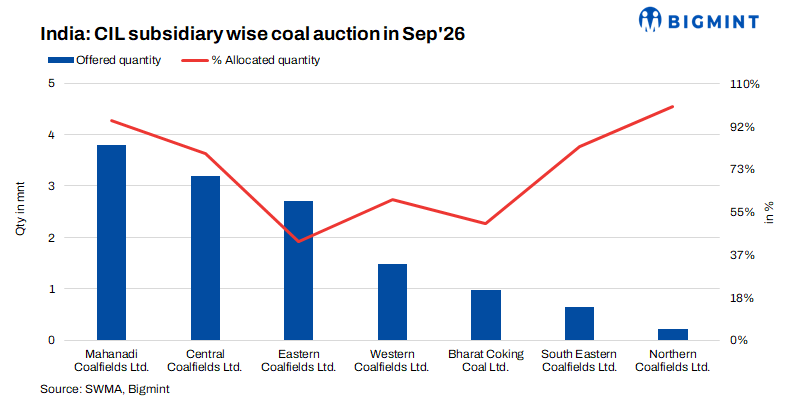
The September results indicate a broad-based improvement in coal uptake across several CIL subsidiaries. Mahanadi Coalfields Ltd (MCL) recorded the highest allocation volume, with 3.56 mnt allocated out of 3.80 mnt offered, translating into an allocation rate of 94%. Central Coalfields Ltd (CCL) allocated 2.54 mnt against 3.19 mnt offered, while Eastern Coalfields Ltd (ECL) allocated 1.13 mnt from 2.71 mnt.
Among the other subsidiaries, South Eastern Coalfields Ltd (SECL) allocated 0.53 mnt out of 0.64 mnt offered, achieving an 83% allocation rate, while Western Coalfields Ltd (WCL) and Bharat Coking Coal Ltd (BCCL) recorded allocation rates of 60% and 50%, respectively.

Northern Coalfields Ltd (NCL) achieved complete absorption of its offered quantity, with 0.22 mnt allocated against 0.22 mnt offered, although the relatively small auction volume limits its impact on the overall allocation figure.
Elevated premiums reflect competition for specific coal grades
The sharp increase in auction premiums provides an important indication of market dynamics. CIL’s September auctions recorded an overall 94% premium over notified prices, with particularly high premiums reported for NCL and SECL coal at 231% and 211%, respectively. ECL and WCL also recorded premiums exceeding 100%, at 118% and 105%.
The elevated premiums suggest that buyers were competing aggressively for specific grades and sources where coal availability was relatively constrained or where the delivered cost remained competitive against alternative sources.
Key factors supporting higher premiums
- Improved industrial procurement: Non power consumers, including sponge iron, steel, cement and other coal-intensive industries, may have increased procurement requirements as operating activity improved.
- Grade-specific demand: Buyers tend to compete more strongly for coal with suitable quality parameters, particularly where substitution with other domestic grades is difficult.
- Inventory replenishment: Post monsoon procurement requirements can encourage industrial consumers to rebuild inventories and secure material for upcoming production requirements.
- Replacement-cost dynamics: Where imported coal or alternative domestic sources carry higher delivered costs, buyers may remain willing to bid aggressively in domestic auctions.
- Regional supply considerations: Freight economics and proximity to coal-producing regions can make specific CIL sources more attractive to consumers despite higher auction premiums.
FY27 performance below Sept’26 levels
Despite the strong September performance, cumulative FY27 figures indicate that e-auction demand has remained selective during the first half of the financial year. CIL subsidiaries offered 142.19 mnt between Apr-Sep’26, against which only 57.10 mnt was allocated, resulting in an overall allocation rate of only 40%.
Among major subsidiaries, SECL recorded the highest allocation rate among the larger-volume producers at 68%, with 15.29 mnt allocated against 22.50 mnt offered. WCL allocated 5.40 mnt from 10.75 mnt, while CCL allocated 11.01 mnt against 24.97 mnt offered. MCL, despite offering the largest cumulative volume of 52.78 mnt, allocated 15.62 mnt, equivalent to 30% of the quantity offered. ECL and BCCL recorded even lower allocation rates of 26% and 20%, respectively.
This divergence indicates that auction participation remains highly dependent on coal grade, price competitiveness and individual consumer requirements rather than simply the volume offered by CIL subsidiaries.
Post-monsoon demand may support further auction uptake
September’s stronger performance comes at a period when coal market conditions typically begin transitioning from monsoon-related logistical constraints towards relatively improved movement and procurement conditions. With the monsoon season receding, industrial consumers may gradually increase procurement and replenish inventories.
The improvement in allocation therefore appears to indicate stronger near-term procurement interest, although the sustainability of the trend will depend on industrial operating rates, coal availability, logistics and competing fuel prices.
Outlook
CIL e-auction demand is expected to remain firm but selective, supported by inventory replenishment and steady industrial consumption. Higher premiums and improved allocations indicate strong competition for preferred grades and strategically located supplies. However, elevated premiums may constrain participation where landed costs become less competitive, keeping buyers focused on coal quality and delivered economics. Going forward, allocation rates and premiums are likely to vary across subsidiaries and grades, with industrial demand, post-monsoon movement, CIL availability, import replacement costs and premium differentials remaining key market indicators.
Leave a Reply