- Indian aluminium ingot prices remain stable; scrap offers weaken
- Domestic copper cathode prices increase on supply concerns
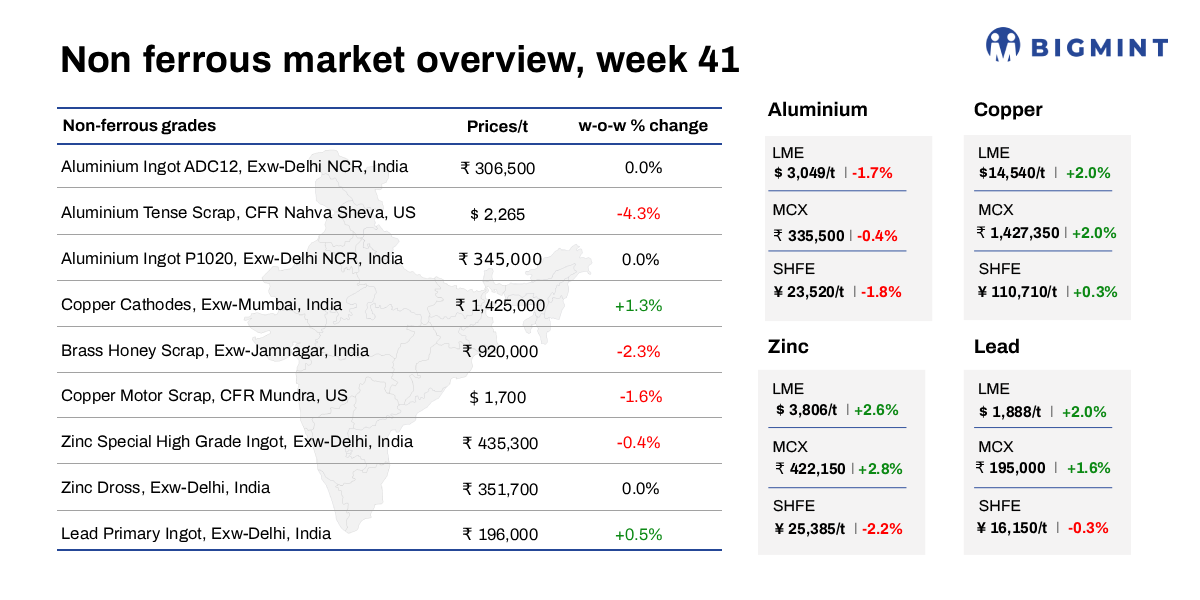
LME base metals showed mixed trends during the week ended 9 October. Aluminium fell 1.7% to $3,049/t, while copper rose 2.0% to $14,540/t. Zinc gained 2.6% to $3,806/t, and lead increased 2.0% to $1,888/t.
Indian physical markets also diverged. Aluminium ingot prices remained unchanged despite weaker global benchmarks and lower scrap offers. Copper cathode prices strengthened on higher international prices, tight scrap availability and pre-festive procurement. Meanwhile, zinc prices softened at the secondary-market level, and Hindustan Zinc Ltd (HZL) reduced its zinc benchmark while raising its lead benchmark.
Aluminium
India’s aluminium market remained stable at the ingot level during the week, despite declines in international and domestic futures prices. Strong demand and tight physical availability supported domestic prices, while lower replacement costs weighed on imported scrap.
According to BigMint’s assessment, P1020 aluminium ingot prices in Delhi NCR remained unchanged at INR 345,000/t. Aluminium ingot ADC12 prices ex-Delhi NCR also remained stable at INR 306,500/t.
However, imported scrap prices weakened. UK-origin Zorba 95-5 scrap prices fell by $60/t, or 2.2% w-o-w, to $2,635/t from $2,695/t. US-origin Tense scrap offers, CFR Nhava Sheva, declined 4.3% to $2,265/t.
Indian aluminium premiums remained stable at $280-290/t, supported by tight primary metal availability, while weaker Japanese import demand pushed Q4 MJP premiums down nearly 35% q-o-q to $255/t CIF Japan. Meanwhile, a proposed EU restriction on metal-waste exports to non-OECD countries from May 2027 could constrain India’s scrap sourcing, even as manufacturers such as Yamaha increase recycled aluminium use, highlighting the growing importance of scrap availability and supply diversification.
Domestic aluminium ingot prices are expected to remain stable in the near term, supported by tight physical availability and demand from manufacturers. However, weaker global benchmarks, lower imported scrap offers, and subdued Japanese premiums could limit upward price movement. Potential changes to EU scrap-export rules will remain a longer-term supply consideration.
Copper
India’s copper market strengthened during the week as higher international prices, falling exchange inventories and supply concerns supported sentiment. Renewed Chinese buying after the Golden Week holiday and labour disruptions at major Chilean mines reinforced the market’s firm outlook.
According to BigMint’s assessment, copper armature scrap prices ex-Delhi increased by INR 2,000/t, or 0.15% w-o-w, to INR 1,352,000/t from INR 1,350,000/t. Copper cathode prices ex-Mumbai rose by INR 19,000/t, or 1.35%, to INR 1,425,000/t from INR 1,406,000/t.
International copper prices strengthened as Chinese buying resumed after Golden Week amid tight concentrate supply, with treatment charges falling to negative $235-240/t. The Centinela strike, potential labour action at Escondida and rising sulphuric acid costs added supply risks. With Chinese demand recovering and supply constraints persisting, competition for available copper is expected to intensify in the coming months, supporting prices.
Domestic copper prices are also expected to remain firm as festive buying gathers momentum after mid-October. However, elevated input costs continue to restrain buyers, keeping procurement cautious and focused on immediate requirements rather than inventory building.
Zinc & lead
India’s zinc and lead markets showed mixed trends this week. Secondary zinc prices diverged, while HZL revised its zinc and lead benchmarks in opposite directions. Firmer LME prices supported sentiment, but rising zinc inventories weighed on the outlook.
According to BigMint’s assessment, zinc dross prices ex-Delhi remained stable w-o-w at INR 351,700/t, while Zinc oxide (99% Zn) prices rose 0.51% to INR 334,700/t.
HZL cut its SHG zinc ingot benchmark by INR 1,500/t to INR 408,200/t from INR 409,700/t. Its lead ingot benchmark rose by INR 1,100/t to INR 212,600/t from INR 211,500/t.
Zinc prices may remain range-bound as exchange inventories rise and Chinese exports increase. Lead prices are likely to track LME movements, domestic benchmarks, and buying activity.
Leave a Reply