- Imported thermal coal prices strengthen as domestic buying stays cautious
- Petcoke costs rise, prompting cement producers to reassess fuel blends
Indian coal markets showed mixed trends in the week ended 24 October 2026, with firm international offers and supply uncertainties supporting imported coal prices, while festive-season inactivity and cautious procurement limited trading. Domestic coal and washed coal prices weakened, although selected auction bids remained firm. Higher petcoke costs encouraged cement buyers to consider alternative fuel blends, while uneven port inventories and freight increases complicated replacement decisions. Weak steel margins also restrained coking coal and metallurgical coke demand, despite supply-side risks.
Indonesian thermal coal prices stay stable amid cautious buying
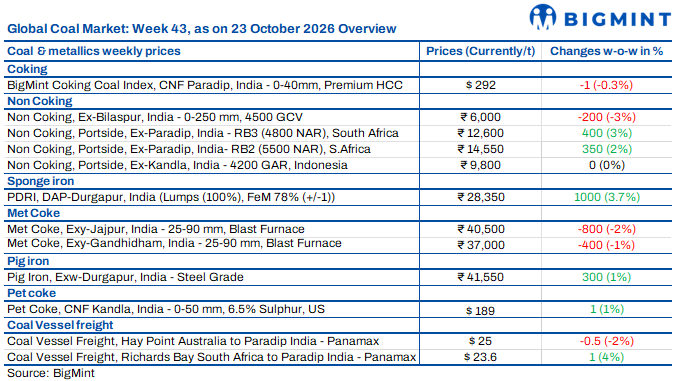
Indian portside Indonesian thermal coal prices remained largely unchanged in the week ended 23 October 2026, as subdued spot demand offset support from low power plant stocks. Prices for 5,000 GAR coal stood at INR 11,700/t at Kandla and INR 11,600/t at Vizag, while 4,200 GAR coal remained at INR 9,800/t and INR 9,700/t, respectively. Navlakhi 3,400 GAR coal held at INR 7,750/t. Power plant stocks fell 3.5% w-o-w to 19.73 mnt, covering around six days of consumption. However, port inventories rose 2% to 19.06 mnt, limiting price gains. Mixed Indonesian benchmarks and cautious procurement kept the market under pressure.
South African coal prices rise despite subdued buying
South African thermal coal prices strengthened at Indian ports as of 23 October, supported by firm export offers and higher replacement costs. At Paradip, RB2 rose INR 350/t w-o-w to INR 14,550/t, while RB3 increased INR 400/t to INR 12,600/t. At Vizag, RB2 gained INR 350/t to INR 14,500/t and RB3 rose INR 350/t to INR 12,500/t. However, festive-season trading remained slow, with limited fresh offers and buyers relying on existing cargoes. Sponge iron prices increased to INR 28,100/t at Raipur and INR 28,350/t at Durgapur. Port coal stocks rose 2% to 19.06 mnt, although availability varied across locations.
Washed, domestic coal prices weaken amid festive slowdown
BigMint assessed 38-39% FC (5,000 GCV) washed coal FOR Raipur at INR 9,500/t as of 21 October, down INR 50/t w-o-w. Ex-Bilaspur 4,500 GCV coal prices fell INR 200/t to INR 6,000/t as of 23 October, while 5,000 GCV coal declined INR 150/t to INR 8,550/t. Festive-season trading and soft market sentiment weighed on spot prices, although final bids in SECL’s 23 October auction remained firm. Buyers remained cautious about bulk purchases as they compared prevailing market prices with earlier auction costs.
Coking coal index eases amid supply risks
India’s premium hard coking coal index fell by $1/t week-on-week to $292/t CNF Paradip on 23 October 2026, down nearly $15/t since end-September. An Australian miner sold 75,000 t of Goonyella coking coal to an Indian mill at $267/t FOB for 15-24 November loading. Supply concerns persisted after tighter checks in China’s Shanxi province affected 10 mnt of coal output, while Australian production uncertainty and Russian port disruptions supported prices.
Indian met coke prices weaken on cautious buying
India’s BF-grade met coke prices fell by INR 800/t week-on-week to INR 40,500/t ex-Jajpur and by INR 400/t to INR 37,000/t ex-Gandhidham in the week ended 22 October 2026. Rajkot foundry-grade coke declined by INR 100/t to INR 39,100/t. Weak steel demand and pressure on mill margins limited purchases to immediate needs. Imported Indonesian met coke prices remained stable at $368/t CFR India, while Australian PHCC prices fell by $4/t to $265/t FOB. A 30,000-t Indonesian coke cargo was reportedly traded at $339/t FOB. In China, producers proposed coke price hikes of RMB 50-55/t ($7.5-8/t), but mills remained cautious. Durgapur pig iron prices rose by INR 500/t to INR 41,800/t on export bookings and supply constraints.
US coal stocks rise; retail prices soften
Tracked US coal stocks at Kandla and Tuna nearly doubled to 204,384 t on 19 October 2026 from 107,177 t a week earlier, while weekly lifting rose 26.5% to 54,122 t. Retail indications softened to INR 18,500-18,600/t, against INR 19,000-19,500/t in early October, as festive-period buying remained subdued. However, fresh NAPP offers stayed above $180/t CFR, limiting the scope for further price declines. The October-December vessel pipeline totalled 2.66 mnt, including 2.50 mnt of North Appalachian (NAPP) and 0.16 mnt of Illinois Basin (ILB).
Petcoke prices rise as freight costs increase
Global 6.5% sulphur petcoke prices rose by $2/t week-on-week to $117/t FOB US Gulf Coast in the week ended 21 October 2026. Indian delivered prices increased by $4/t to $189/t CFR, while November-December offers reached $193-195/t. Freight to India stood at around $58/t, up $20.25/t year-on-year. Buyers remained selective, favouring existing inventories, domestic coal and alternative blends. Petcoke cost around $25.20/Gcal against $24.15/Gcal for coal, based on the stated benchmarks. Recorded Indian petcoke imports reached 653,517 t through 18 October, with another 375,322 t outstanding, taking total visibility to 1.03 mnt. UltraTech remained the largest identified receiver.
Coal freight rates diverge despite rising fuel costs
India-bound coal freight markets showed mixed trends in the week ended 23 October 2026. Panamax freight from Hay Point, Australia, to Paradip fell by $0.5/t to $25/t, while South African rates rose by $1/t to $23.6/t. Indonesian Supramax rates to Navlakhi increased by $0.6-1.5/t to $23.7-24/t. The Baltic Dry Index rose 5.8% week-on-week to 2,693, despite an 8.7% decline in the Panamax index to 2,151. Singapore VLSFO prices climbed 4.7% to $952.5/t, raising vessel operating costs. Cautious charterers and limited fresh bookings constrained activity, while tighter vessel availability supported selected routes.
Leave a Reply