- Domestic coal shortages lift import enquiries
- Cargo availability remains tight across key ports
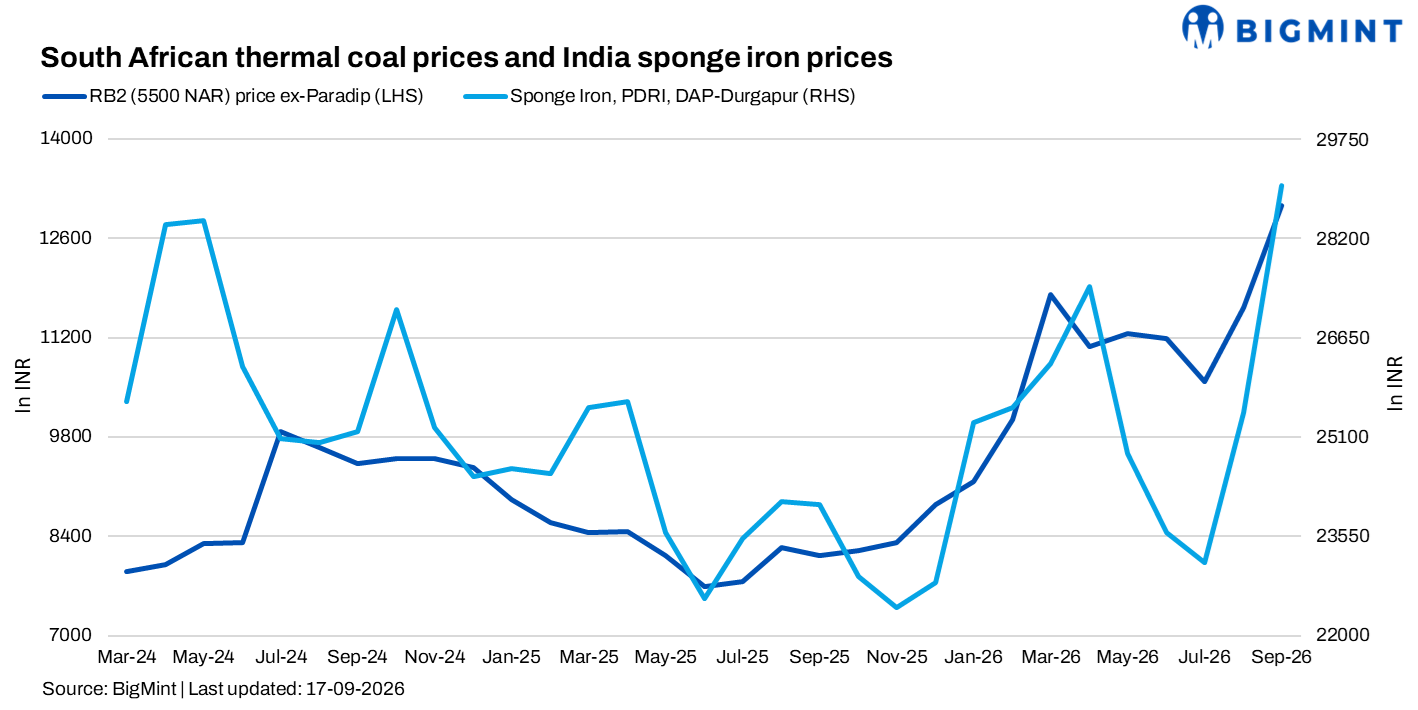
South African thermal coal prices at Indian ports strengthened further as of 17 September 2026, supported by tight domestic coal availability, limited South African cargoes and firm demand from overseas markets. Ex-Paradip RB2 (5,500 NAR) increased INR 100/t w-o-w to INR 13,300/t, while RB3 remained at INR 11,600/t. Ex-Vizag, RB2 rose INR 150/t w-o-w to INR 13,250/t and RB3 increased INR 50/t to INR 11,550/t. Buyers continued to enquire for imported coal as domestic availability remained constrained.
Domestic coal shortage supports import enquiries
Domestic coal prices moved higher during the week, increasing the attractiveness of imported material for consumers facing limited availability. Ex-Bilaspur 4,500 GCV coal rose INR 400/t w-o-w to INR 6,300/t, while 5,000 GCV coal increased INR 50/t to INR 8,050/t as of 15 September.
Availability also remained constrained as auction frequency from Coal India subsidiaries declined during the monsoon period. Recent auctions by MCL and ECL saw very high premiums for selective grades, making procurement more expensive for consumers.
With domestic coal availability tightening, buyers started enquiring for South African cargoes. Offers for 5,500 NAR were around $105/t FOB South Africa, against bids of around $102/t. For 4,800 NAR, offers were around $93/t, while bids were around $90-91/t. For 5,700 NAR material, offers were heard around the index minus $4.5-5/t.
Cargo shortages keep South African supply tight
Limited cargo availability continued to support South African prices. Strong demand from other destinations, including tenders from South Korea, also increased competition for available cargoes and contributed to vessel availability constraints.
Indian port stocks remained under pressure. Total thermal coal inventories at major Indian ports declined 3% w-o-w to 13.08 mnt in Week 37 from 13.48 mnt in Week 36. Stocks fell at several major ports, including Kandla, Magdalla, Krishnapatnam and Dahej, although higher inventories at Karaikal, Gopalpur and Gangavaram partly offset the decline.
At Vizag, South African coal stocks were unavailable, although upcoming vessels were expected to replenish supplies. Demand at Vizag remained limited, while enquiries were stronger at Paradip and Dhamra. Some cargoes were therefore being diverted towards these ports.
At Mangalore, limited stock availability also kept offers elevated. RB2 was being offered around INR 13,200-13,400/t, while a purchase of around 5,000 t of RB2 was reported at INR 13,000/t. RB3 offers were around INR 11,400-11,500/t.
Higher steel demand adds support to coal market
Improved steel demand also provided support to thermal coal consumption through the sponge iron sector. PDRI ex-Raipur increased INR 550/t w-o-w to INR 29,600/t.
However, buying activity in the sponge iron market remained slow and largely need-based. Positive sentiment in finished steel supported prices, while buyers continued to limit purchases amid the Vishwakarma Puja holiday. Around 9,000 t of sponge iron was traded, down 6,000 t d-o-d, indicating softer buying momentum.
Higher raw material costs also kept sellers firm, with Raipur raw pellet prices around INR 11,100/t, up INR 250/t.
Buyers remain cautious despite tighter availability
Although domestic shortages have increased enquiries for South African coal, the gap between bids and offers remained evident. Buyers continued to assess replacement costs carefully and largely focused on immediate requirements.
Outlook
South African coal prices could remain supported if domestic coal availability stays tight, overseas demand remains firm and cargo availability remains limited. However, elevated import prices are likely to keep broader buying cautious and largely need-based.
Leave a Reply