- Chinese zinc output falls 1.8% y-o-y in August amid supply concerns
- Higher Chinese exports could ease zinc availability outside China
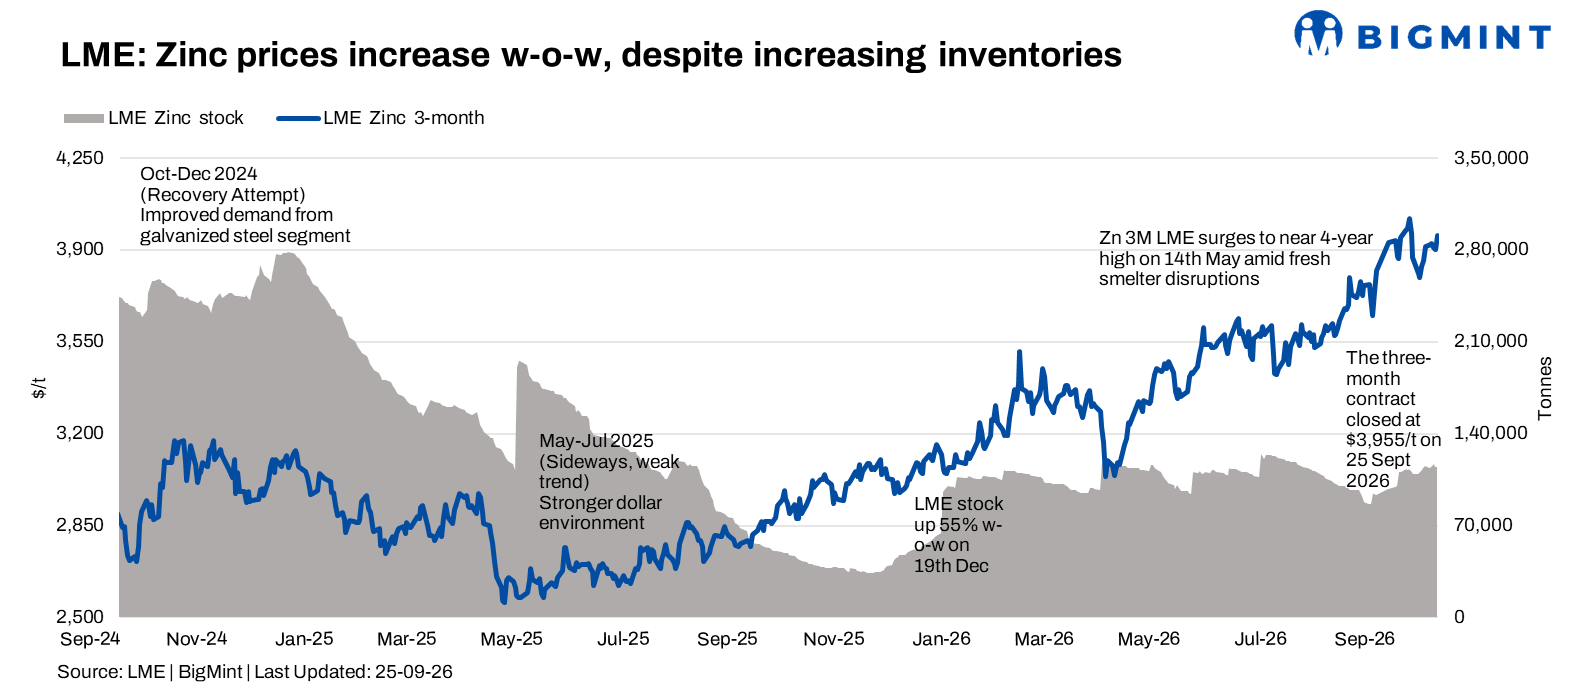
LME zinc prices strengthened during the week, recovering above $4,000/t amid continued supply concerns. LME cash settlement rose 1.2% to $4,060/t on 25 September from $4,010/t on 18 September. The three-month contract increased 1.0% to $3,952/t.
LME inventories increased by 6,300 t, or 5.5%, to 121,600 t during the week from 115,300 t. The cash-to-three-month backwardation widened to $108/t from $97/t, indicating that nearby physical tightness remained despite the rise in warehouse stocks.
Supply concerns persist amid smelter and concentrate risks
Zinc prices continued to receive support from concerns over refined metal and concentrate availability. The fatal accident at Korea Zinc’s Onsan smelter on 16 September remained a market focus, although the extent of any production impact was still uncertain.
Supply concerns were reinforced by lower mine output and tight concentrate availability. Boliden’s zinc concentrate production declined 16.8% q-o-q to 74,200 t, while Glencore’s own-sourced zinc production remained 21% lower y-o-y at 365,600 t in H1 2026.
Nyrstar’s strategic review of its Budel zinc smelter in the Netherlands, citing high energy costs and low treatment charges, also added to concerns over European refined zinc supply. Meanwhile, disruptions at several mines and restrictions on Iranian ore shipments have further tightened concentrate availability.
Global refined zinc fundamentals remained mixed. The market moved into a 31,400-t deficit in June from a 22,400-t surplus in May. However, the market remained in a 120,000-t surplus during H1 2026, compared with a 74,000-t surplus in H1 2025.
Rising LME inventories provide some counterweight to supply concerns, while elevated prices and expectations of higher Chinese exports could improve availability in other markets. China’s refined zinc production declined 1.8% y-o-y to 639,000 t in August, its first annual decline in nearly a year.
MCX zinc falls 2.3% as open interest declines
MCX zinc futures weakened during the week, with the September contract closing at INR 423,050/t on 25 September against INR 433,050/t on 18 September, down INR 10,000/t, or 2.3%.
The contract touched a weekly high of INR 451,000/t and a low of INR 420,700/t. Open interest declined sharply to 408 lots from 2,022 lots.
The strongest move came during the final session, with prices falling from INR 446,150/t on 24 September to INR 423,050/t on 25 September. The sharp decline coincided with a steep fall in open interest as the September contract approached expiry.
SHFE zinc remains elevated amid domestic inventory drawdowns
SHFE zinc maintained a higher price centre during the week, supported by LME gains and domestic destocking. The most-traded 2611 contract closed at 26,760 yuan/t on 24 September, up 195 yuan/t from the week’s opening level, while open interest increased by 18,231 lots to 147,861 lots.
Domestic inventory drawdowns and pre-holiday stockpiling provided support, although elevated prices continued to keep downstream buying cautious. SHFE zinc trading was also influenced by expectations around China’s upcoming holiday period.
Domestic zinc market remains firm
India’s domestic zinc market remained firm amid elevated international prices and a higher BigMint assessment.
Hindustan Zinc Ltd (HZL) raised its benchmark Special High-Grade (SHG) zinc ingot price by INR 900/t on 24 September to INR 425,500/t. The company also increased its lead benchmark by INR 2,700/t to INR 216,900/t.
BigMint’s SHG zinc assessment rose to INR 447,700/t ex-Delhi on 25 September, remaining significantly above the HZL benchmark.
Higher international prices, elevated replacement costs and supply concerns continue to support domestic zinc levels. However, elevated prices and cautious downstream buying could limit further upside.
Outlook
LME zinc is expected to remain volatile as persistent supply concerns are balanced against rising inventories and cautious downstream demand.
The move above $4,000/t keeps supply risks in focus, particularly amid tight concentrate availability, low treatment charges and ongoing smelter concerns. However, the 5.5% weekly increase in LME inventories and expectations of higher Chinese exports could limit the upside.
Support is seen at $3,900-3,950/t, while resistance is expected around $4,060-4,100/t. LME inventories, backwardation, Chinese exports, treatment charges, mine supply and smelter developments will remain key indicators for zinc prices.
Leave a Reply