- Fujairah MGO gains sharply on tighter middle-distillate supply
- VLSFO prices ease across key bunkering hubs amid softer sentiment
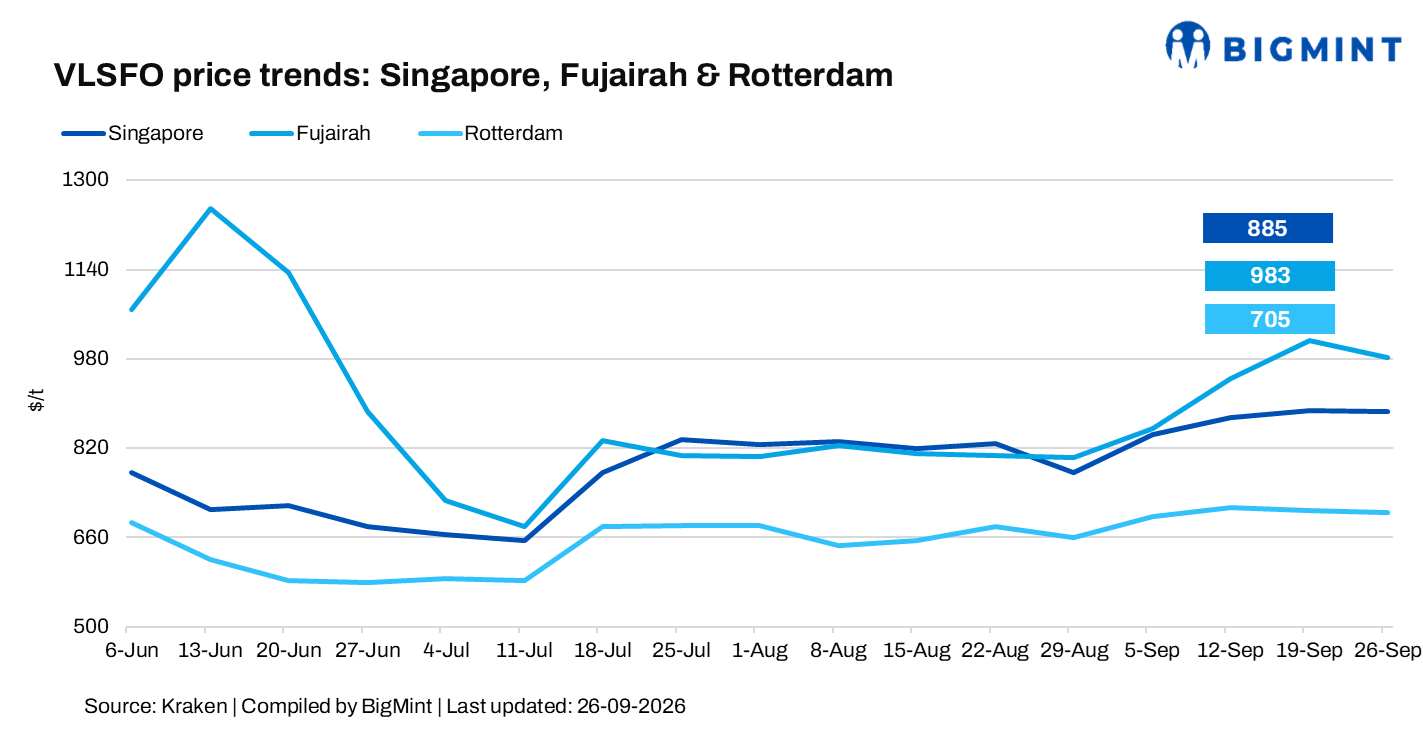
Global bunker prices showed mixed movements across major hubs in the week ended 25 September 2026. Marine Gas Oil (MGO) prices rose sharply in Fujairah, while Very Low Sulphur Fuel Oil (VLSFO) declined across all three hubs and High Sulphur Fuel Oil (HSFO) posted mixed regional movements.
The divergent trend reflects continued volatility in Middle East fuel markets, with supply and shipping disruptions keeping regional premiums elevated. At the same time, renewed US-Iran diplomatic efforts and expectations of a possible reopening of the Strait of Hormuz have recently eased some crude-price pressure.

Regional bunker markets
- Singapore: VLSFO declined $3/tonne (t) (0.3%) w-o-w to $885/t, while MGO fell sharply and HSFO increased w-o-w. The decline in middle-distillate prices indicates some easing in regional replacement costs, although fuel markets remain sensitive to supply disruptions.
- Rotterdam: VLSFO eased by $3/t (0.4%) w-o-w to $705/t, while MGO also declined, reflecting softer buying interest and a relatively subdued market tone. In contrast, HSFO prices increased, supported by firmer demand and tighter availability, highlighting divergent sentiment across fuel grades.
- Fujairah: VLSFO fell by $29/t (2.9%) w-o-w to $983/t, reflecting softer buying interest and easing market sentiment. In contrast, MGO surged, supported by firmer demand and tighter availability, while HSFO declined sharply amid weaker market fundamentals. Despite the fall in VLSFO, Fujairah continued to command a significant regional premium, particularly for MGO, indicating sustained tightness in the middle-distillate market.
Market factors
- Brent crude rises: Brent crude futures increased $1.50/barrel (bbl) (1.4%) w-o-w to $104.94/bbl, from $103.44/bbl. Crude remained elevated amid renewed attacks targeting Saudi energy infrastructure and persistent concerns over Middle East supply disruptions. However, reports of renewed US-Iran talks and potential arrangements to reopen the Strait of Hormuz have capped further upside.
- WTI crude declines sharply: WTI stood at $92.82/bbl on 26 September, down $6.58/bbl (6.6%) from $99.40/bbl on 19 September. The decline was driven mainly by growing hopes of a US-Iran truce and potential reopening of the Strait of Hormuz, which eased concerns over supply disruptions.
Outlook
Global bunker prices are likely to remain volatile in the near term, with Middle East security, Strait of Hormuz developments and crude-price movements remaining key drivers. MGO could retain relative strength amid tight middle-distillate markets, while VLSFO and HSFO may see more mixed regional movements. Any concrete improvement in US-Iran negotiations and restoration of regional oil flows could reduce the geopolitical premium, while renewed attacks or shipping disruptions could quickly push bunker prices higher.
Leave a Reply