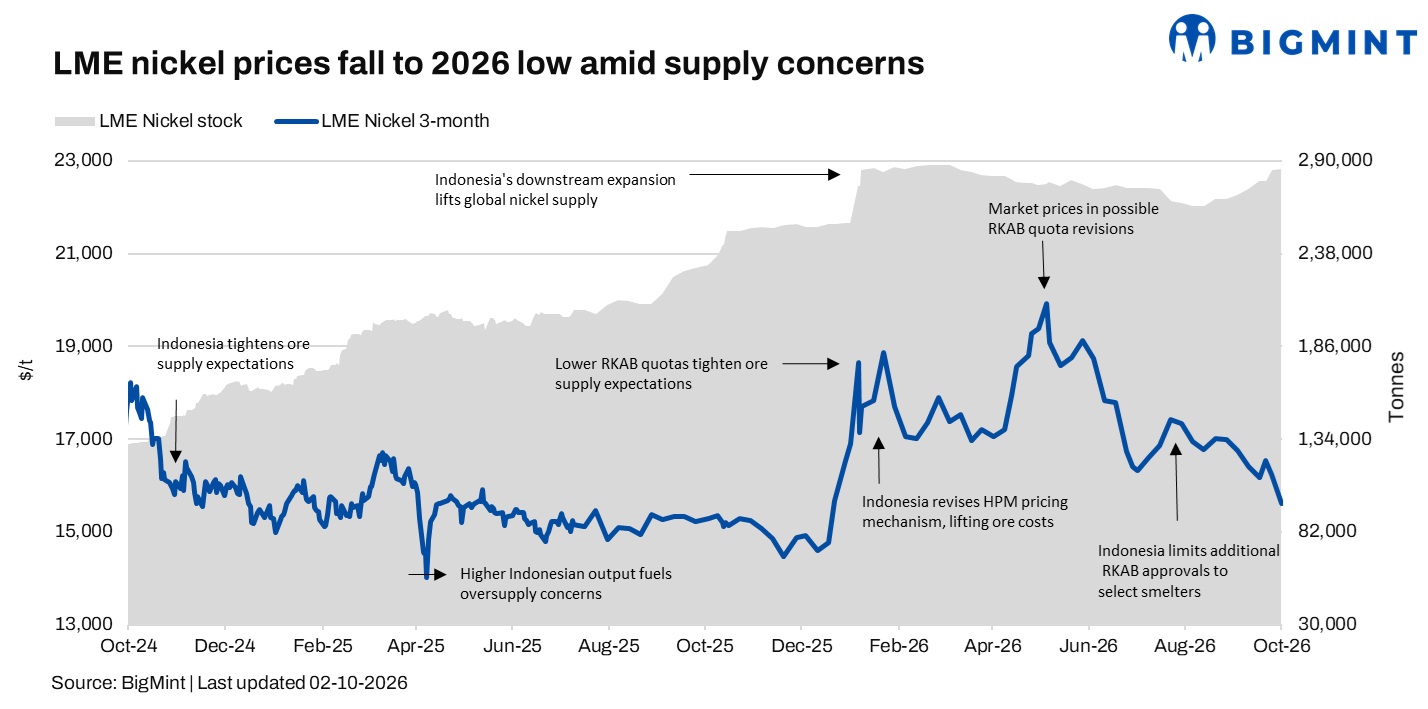
- Nickel prices declined 3.8% w-o-w
- Indonesian policies could influence global prices
LME three-month nickel prices declined 3.8% w-o-w to $15,625/t on 2 October 2026, from $16,230/t a week earlier, marking the lowest level recorded in 2026. The decline came amid concerns over ample supply and subdued demand from the stainless steel sector. Meanwhile, LME nickel inventories increased marginally to 285,168 t from 284,946 t over the same period, indicating continued availability of metal in the exchange warehouse system.
Indonesia strengthens influence over global nickel supply
Indonesia continues to strengthen its position in the global nickel market, having emerged as the world’s largest nickel smelting and processing producer. Government policies restricting raw nickel ore exports and encouraging domestic downstream investment have driven a rapid expansion in processing capacity. Indonesia’s nickel smelting and processing output increased from around 22,000 t in 2014 to more than 1.4 mnt in 2023, raising its share of global production from around 1% to 41%.
Indonesia overtook China in 2021 and has maintained its leading position since then. However, Chinese companies continue to have a significant presence in Indonesia’s nickel-processing industry through investments in smelting and refining assets. Going forward, Indonesia’s efforts to regulate production through mining companies’ work plans and budgets (RKAB) could increase its influence over global nickel supply and pricing.
China’s refined nickel imports remain elevated
China’s refined nickel imports stood at around 17,000 t in August, down 18.9% m-o-m and 29.8% y-o-y. However, cumulative imports during January-August 2026 reached approximately 187,000 t, up 19.9% y-o-y, indicating stronger import availability despite the decline recorded in August.
China’s broader raw-material imports also showed mixed trends during the period. Chrome ore imports increased 36.2% y-o-y to 19.02 mnt, while ferrochrome imports declined 39.2% to 1.12 mnt. Manganese ore imports rose 12% to 23.14 mnt, while stainless steel scrap imports surged 84.9% to 130,900 t. Molybdenum ore imports also increased 57.2% to 73,000 t.
Stainless steel demand remains key to nickel outlook
The stainless steel sector remains a major demand driver for nickel, particularly through the production of 300-series stainless steel. However, elevated stainless steel inventories and cautious downstream procurement in China could limit near-term nickel demand. Higher availability of alternative nickel units, including nickel pig iron (NPI), also remains an important factor for the stainless steel raw-material market.
Outlook
LME nickel prices are likely to remain sensitive to developments in Indonesian production policy, exchange inventories and Chinese stainless steel demand. Any further increase in Indonesian supply or continued inventory accumulation could keep prices under pressure, while production controls under the RKAB system or an improvement in stainless steel demand could provide support. Market participants will closely monitor Indonesia’s production policies, Chinese demand, LME inventories and developments in the stainless steel sector.
Leave a Reply