- Tight physical supply, strong Chinese demand limit LME price correction
- Festive buying supports Indian scrap demand despite high price levels
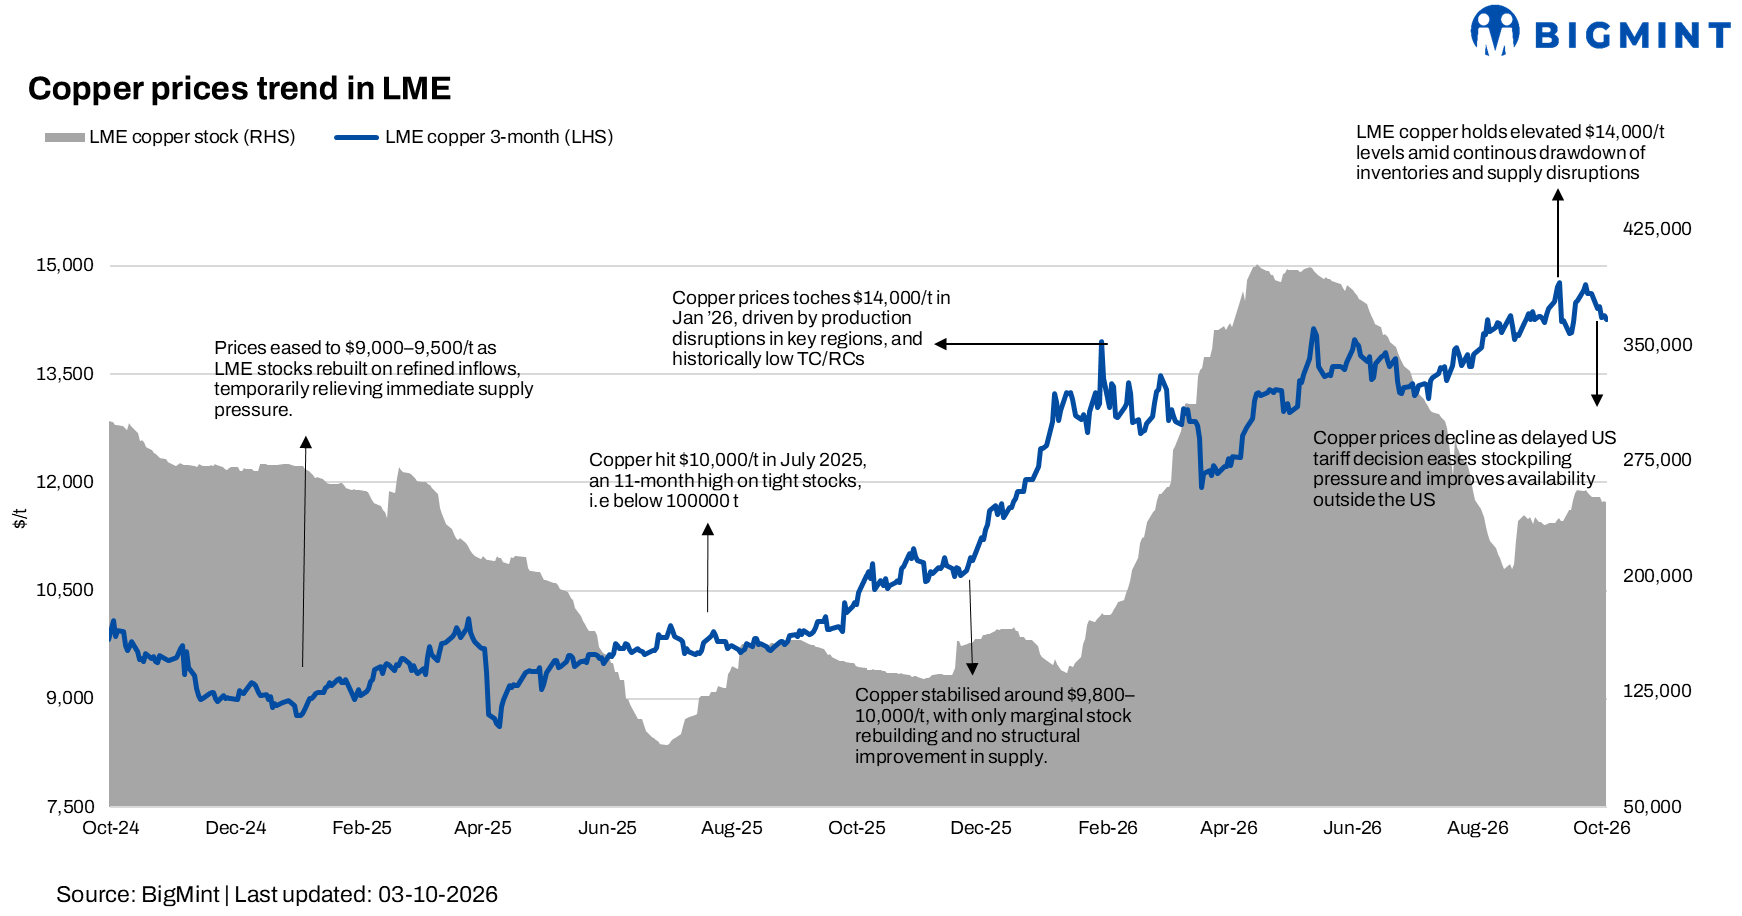
Copper prices corrected during the week ended 3 October as uncertainty over US copper tariffs reduced the incentive for further stockpiling into the US. LME three-month copper fell 2.5% w-o-w to $14,259/t from $14,623/t in the previous week.
The correction followed earlier record highs driven partly by tariff-related inventory shifts. Despite the decline, the physical market remained relatively tight. Chinese demand for copper and scrap stayed firm, while record-low treatment charges continued to signal constrained concentrate availability. Structural demand from AI infrastructure, data centres, next-generation vehicles and grid investment also remains supportive.
US tariff uncertainty triggers copper correction
Copper prices came under pressure after the White House delayed its decision on refined copper tariffs. Earlier tariff expectations had encouraged traders and manufacturers to build US inventories, tightening availability in markets outside the US.
The delay reduced the urgency for further front-loading into US warehouses, allowing the tariff-driven premium to unwind. However, the correction remains balanced by concerns over physical supply. Copper prices continue to trade at historically elevated levels, while exchange inventories outside the US remain vulnerable to renewed demand.
Chinese demand keeps physical market supported
China remains a major driver of copper demand and global scrap flows. Copper scrap imports reached 1.24 mnt in H1CY26, up 8.3% y-o-y, as tighter domestic availability encouraged secondary producers to increase overseas sourcing. Scrap accounted for 25.2% of China’s refined copper feedstock during the period, compared with 22.5% a year earlier.
Chinese refined copper output is also expected to record its slowest growth in decades in 2026. Limited access to concentrate and scrap has prompted several smelters to schedule maintenance during October-November, with estimated refined copper production losses of around 80,000 t.
China’s worsening concentrate shortage was further highlighted this week, with its antitrust regulator seeking supply commitments from Anglo American as part of its review of the proposed Teck Resources merger.
India
According to BigMint’s assessment, ex-Ahmedabad cathode prices remained unchanged at INR 1,408,000/t w-o-w. Ex-Mumbai cathode prices also remained unchanged at INR 1,406,000/t.
Domestic buying interest improved ahead of the festive season, particularly for high-recovery scrap grades. Recyclers and secondary manufacturers increased purchases for immediate requirements amid tighter imported availability.
However, elevated copper prices continued to make buyers price-sensitive. Higher working-capital requirements limited inventory building, with consumers favouring smaller, requirement-based purchases. Competition from overseas buyers also remains relevant. Strong Chinese procurement is absorbing higher-recovery scrap, while stronger bids from Pakistan are making some US-origin motor scrap more competitive there than in India.
Copper prices are expected to remain volatile in the near term, with domestic scrap demand likely to stay supported. However, elevated price levels may keep buying interest selective.
Leave a Reply