- HZL cuts SHG benchmark by INR 6,000/t
- Tight imports and elevated premiums continue to support domestic prices
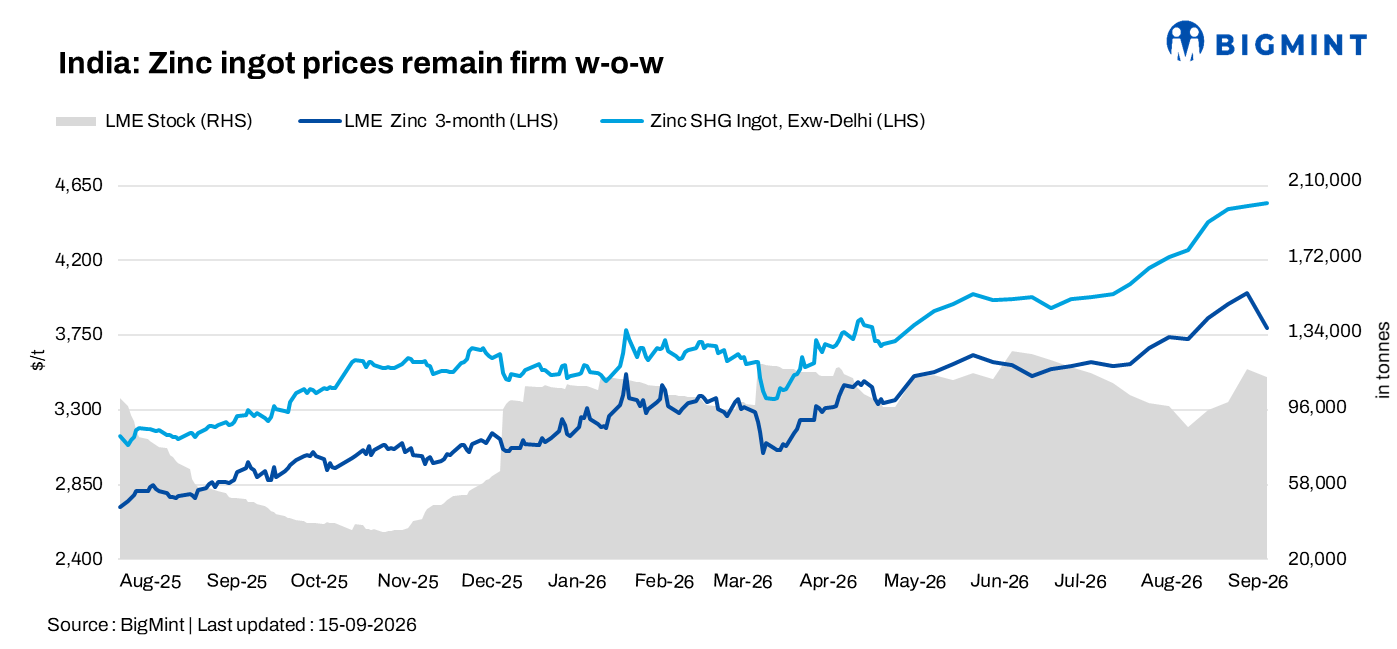
India’s zinc ingot (99.995%) prices remained firm despite a correction in international zinc prices and continued weak downstream demand. BigMint’s benchmark assessment stood at INR 432,000/t ex-Delhi on 15 September, while Hindustan Zinc Ltd (HZL) reduced its SHG zinc benchmark by INR 6,000/t on 14 September to INR 431,400/t.
LME zinc prices declined from the previous week, with cash prices falling below $4,000/t, although exchange stocks also declined by around 4,150 t. Import availability remains relatively tight, while CIF premiums for fresh material remain elevated at around $270-275/t, limiting the scope for imports to provide significant price relief.
Domestic zinc prices remain firm despite HZL cut
Domestic zinc prices remained elevated despite HZL’s latest downward revision.
HZL reduced its benchmark SHG zinc ingot price by INR 6,000/t on 14 September to INR 431,400/t. The reduction came despite lower LME stocks and continued tightness in the import market.
BigMint’s benchmark assessment stood at INR 432,000/t ex-Delhi on 15 September, broadly aligned with HZL’s revised benchmark.
However, downstream buying remained selective, with consumers largely restricting procurement to immediate requirements. Higher zinc prices continue to pressure galvanisers and other downstream users, limiting their ability to absorb further increases.
Zinc imports remain relatively tight despite lower premiums
India’s zinc import market remains relatively tight, although indicative premiums have eased slightly from the previous week’s levels.
Fresh imported zinc was indicated at CIF premiums of around $270-275/t, compared with around $280-290/t previously. South Korean zinc was indicated at around $4,130-4,135/t, while Korean-origin material was heard at around INR 428,000/t in the domestic market.
Australian-origin zinc remained significantly higher at around INR 475,000/t domestically, keeping replacement costs elevated.
Despite the slight moderation in premiums, imported material remains relatively expensive, while availability continues to limit the scope for imports to exert significant downward pressure on domestic prices.
Weak downstream demand continues to limit buying
Downstream zinc demand remains cautious, with buyers largely following a need-based purchasing approach amid elevated input costs.
Galvanisers continue to face pressure from high zinc costs, while the ability to pass on higher costs to customers remains limited. This has kept purchasing activity subdued despite firm domestic zinc prices.
The recent correction in LME zinc prices could provide some relief to downstream consumers, but the impact remains limited as domestic replacement costs and import economics continue to remain elevated.
Zinc alloy prices remain firm
Zinc alloy prices remained supported by elevated primary zinc costs.
In Delhi, Zamak 3 was heard at around INR 446,000/t, while Zamak 5 was indicated at INR 453,000/t. Zinc PMI prices were reported at around INR 388,000/t.
However, downstream demand remained selective, with buyers continuing to procure mainly against immediate requirements.
Coated steel prices continue to increase
India’s coated flat steel prices continued to increase during the latest week, supported by firm input costs.
BigMint’s benchmark assessment for Mumbai GP coil (0.8 mm/CTL, 120 GSM, IS 277) increased by INR 1,600/t w-o-w to INR 79,800/t ex-Mumbai. Mumbai PPGI (0.5 mm/CTL, 90 GSM, IS 14246) rose by INR 300/t w-o-w to INR 87,300/t ex-Mumbai, while BGL (0.5 mm/CTL, 1220 mm, AZ150) remained stable at INR 90,000/t ex-Mumbai.

Outlook
India’s zinc ingot market is expected to remain firm in the near term, supported by relatively tight import availability, elevated replacement costs and CIF premiums of around $270-275/t.
However, the recent correction in LME zinc prices and weak downstream demand could limit further domestic price gains. LME cash zinc declined to $3,922/t on 15 September from $4,110/t on 8 September, while stocks fell to 111,225 t from 115,375 t over the same period.
Imported zinc remains relatively expensive, with Korean-origin material indicated at around INR 428,000/t and Australian-origin material at around INR 475,000/t.
While domestic prices continue to receive support from import economics and replacement costs, further movement will depend on international zinc prices, import availability and downstream buying interest.
Leave a Reply