- Physical zinc shortage pushes Mumbai spot prices above MCX futures
- Import premiums heard at around $270/t; supply tightness may persist until January
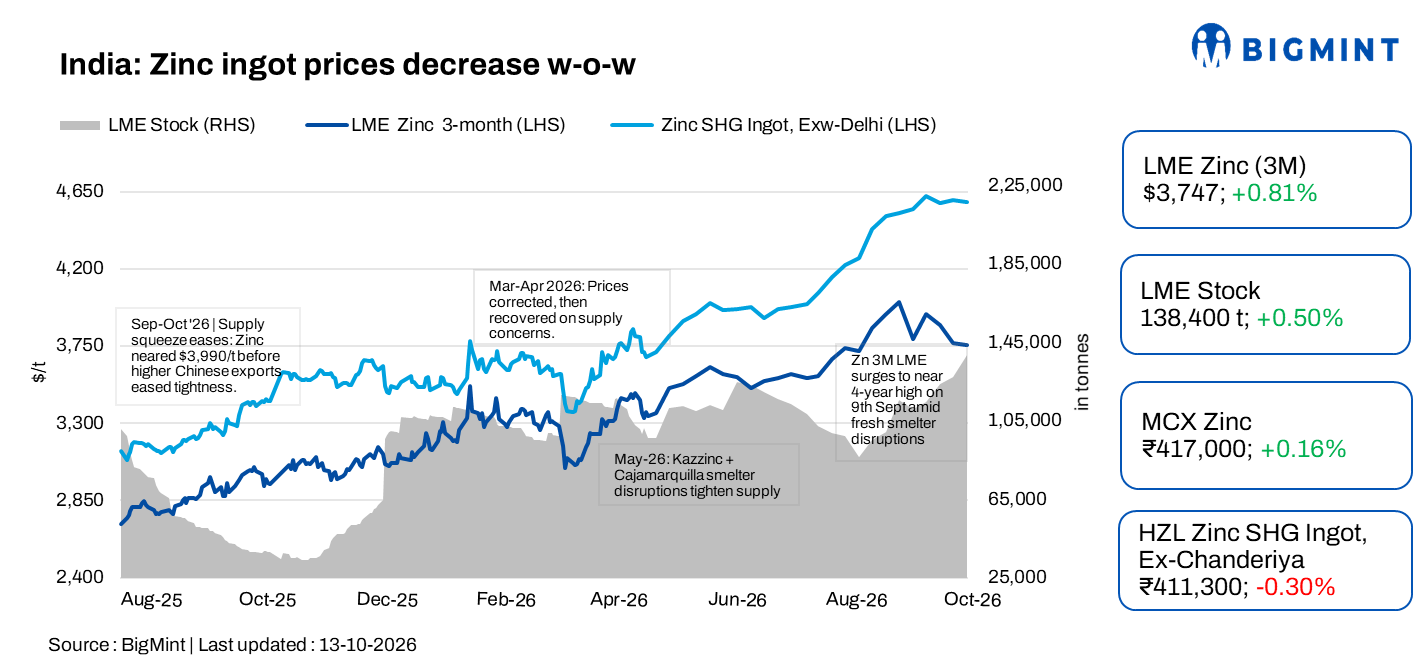
India’s zinc ingot prices eased marginally w-o-w, although physical market premiums remained elevated amid an acute shortage of metal in domestic and import markets. BigMint’s SHG zinc benchmark assessment stood at INR 435,900/t ex-Delhi on 13 October, down INR 1,600/t as reported. Meanwhile, Hindustan Zinc Ltd (HZL) raised its SHG zinc benchmark by INR 3,100/t to INR 411,300/t on 12 October.
Market participants reported that physical zinc prices in Mumbai were trading at a premium of INR 10-15/kg over MCX futures, which were themselves at a premium of around INR 15/kg over LME-based prices. Kolkata spot prices were also reported at a premium of INR 5-6/kg over MCX futures. Import premiums were heard at around $270/t, while tight material availability continued to support domestic prices.
Domestic prices remain supported by acute supply shortage
Domestic zinc ingot prices eased marginally, but physical market conditions remained tight amid limited availability of metal.
BigMint’s SHG zinc benchmark assessment stood at INR 435,900/t ex-Delhi on 13 October, down INR 1,600/t as reported. In contrast, HZL raised its SHG zinc benchmark by INR 3,100/t to INR 411,300/t on 12 October.
According to market participants, physical zinc prices in Mumbai were trading at a premium of around INR 10-15/kg over MCX futures, while futures were at a premium of approximately INR 15/kg over LME-based prices. Kolkata spot prices were also reported at a premium of INR 5-6/kg over MCX futures.
Supply constraints were also evident in Delhi, where market feedback indicated limited availability of HZL-origin SHG zinc, with arrivals reportedly restricted to around one truckload daily. Availability of AZ-origin material was also said to be tight.
Zinc import premiums rise amid limited availability
India’s zinc import market remained tight, with limited availability supporting physical premiums.
South Korean SHG zinc duty-free premiums were heard at around $270/t, compared with earlier indications of $260-265/t. Korean SHG zinc was indicated at around $4,005-4,010/t, while Korean-origin zinc was heard at around INR 432,000/t in the domestic market. Australian-origin zinc was indicated at INR 493,000-494,000/t.
Market participants indicated that import availability would remain insufficient to ease the current shortage immediately. Although fresh imports are expected to begin arriving, market feedback suggests that supplies may remain constrained through November, with conditions potentially taking until January to stabilise.
Material shortage keeps physical premiums elevated
Material availability remained the key concern across India’s zinc market, with shortages reported in both domestic and imported material.
Market participants indicated that limited HZL-origin SHG zinc arrivals in Delhi, tight AZ-origin availability and constrained Korean-origin supplies were contributing to the shortage. The resulting gap between futures-based prices and physical spot prices was particularly pronounced in Mumbai.
The premium structure suggests that buyers are paying more to secure immediate physical metal than implied by exchange-linked prices alone. However, the extent and duration of the shortage will depend on actual import arrivals and domestic supply availability over the coming months.
Zinc alloy prices
In the zinc alloy market, Zamak 3 and Zamak 5 prices were indicated at around INR 442,000/t and INR 448,000/t, respectively. Zinc PMI prices were indicated at around INR 385,000/t.
Alloy buyers continued to monitor raw material replacement costs and metal availability, with supply constraints remaining an important consideration for procurement.
Coated steel prices increase
India’s coated flat steel prices increased w-o-w in the week ended 8 October, with gains across GP coil, PPGI and Galvalume.
BigMint’s Mumbai GP coil assessment increased by INR 100/t to INR 83,100/t ex-Mumbai on 8 October. PPGI prices rose by INR 1,300/t to INR 90,600/t, while Galvalume prices increased by INR 1,100/t to INR 93,700/t.
The gains in coated steel prices provide a downstream market reference, although the impact of zinc supply constraints on galvaniser procurement will depend on order activity and raw material requirements.

Outlook
India’s zinc ingot market is expected to remain supported by acute physical metal shortages and elevated spot premiums, even as rising LME stocks could limit gains in international prices.
LME zinc cash prices increased to $3,821/t on 13 October from $3,799/t on 7 October, while three-month prices remained unchanged at $3,756/t. LME zinc stocks rose to 138,400 t from 127,750 t over the same period, an increase of 10,650 t.
Import premiums were heard at around $270/t, while market participants indicated that fresh imports may not be sufficient to resolve the shortage in November. Supply conditions could take until January to stabilise, although this remains a market expectation rather than a confirmed timeline.
In the near term, domestic price direction is likely to depend on the availability of physical metal, import arrivals and the persistence of spot premiums over exchange-linked prices.
Leave a Reply