- Firm vessel offers support bulk freights despite cautious chartering
- Exchange volatility, uneven enquiries weigh on container bookings
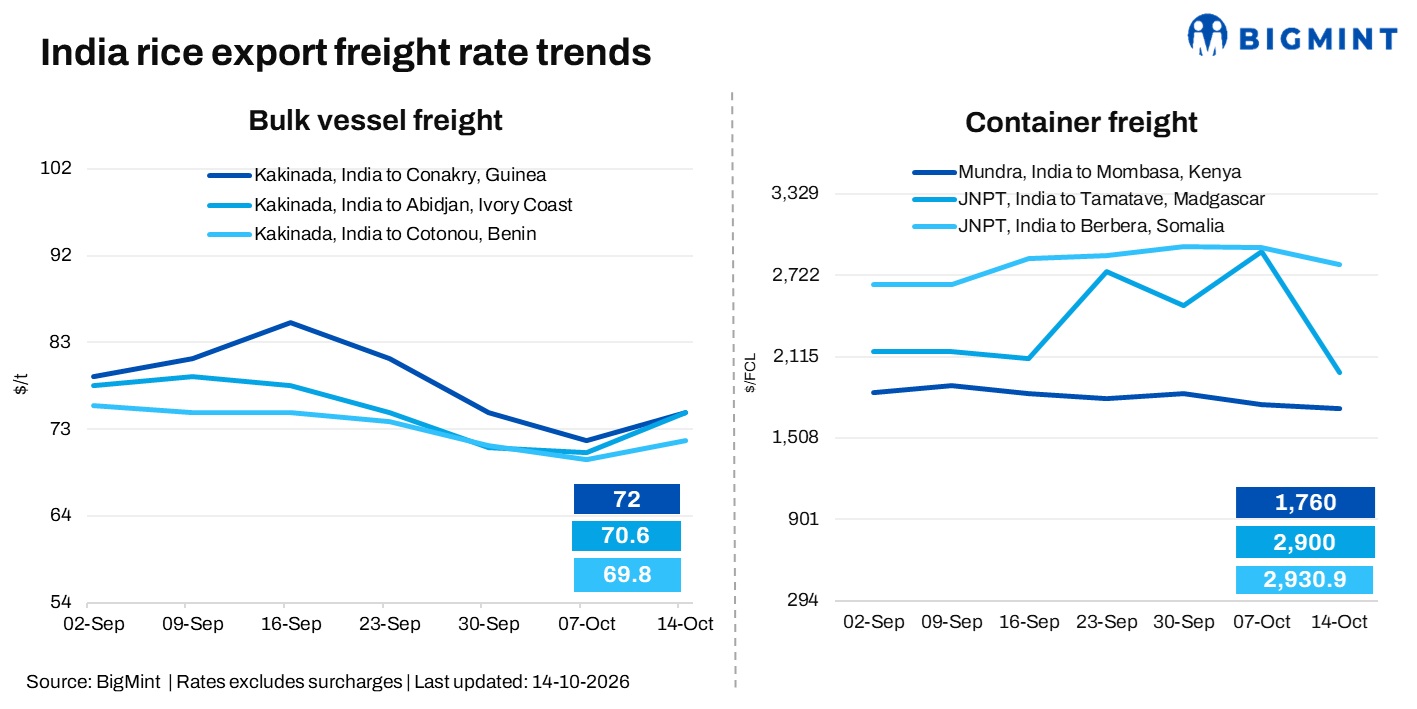
India’s rice freight market showed mixed trends in the week ended 14 October, with bulk freights recovering on West African routes after last week’s losses, while container rates varied across African destinations. Port congestion and firm vessel offers supported bulk rates, whereas exchange-rate volatility and selective buying continued to influence container bookings.
A shipbroker told BigMint, “The bulk market remains firm, supported by improving Atlantic Supramax activity and emerging new-crop demand. However, war-risk premiums on the Berbera route and elevated freight rates to the Gulf and Africa continue to pose challenges.”

West African bulk freights increase
Bulk freights rose across Kakinada’s key West African routes, with congestion at Conakry and Abidjan affecting vessel turnaround and adding pressure to freight negotiations. Improving Atlantic Supramax activity provided further support, although cargo enquiries remained selective.
A shipbroker said, “Market sentiment remains bearish amid expectations of new-crop arrivals, while festive-season sluggishness is weighing on activity. Market momentum is expected to improve after Diwali.”
The market saw firm vessel offers alongside cautious buying. Traders are assessing new-crop prices and availability before committing to shipments, leaving the pace of fresh fixing activity dependent on renewed enquiries.
Container market remains uneven
Container freights showed mixed trends across African destinations. Improved space availability eased pressure on some routes, while limited sailing options and route-specific demand continued to influence others. At Mombasa, equipment imbalances and documentation delays added to shipment uncertainty. Exchange-rate volatility further complicated negotiations, prompting some buyers to reconsider or cancel bookings as overall shipment costs fluctuated.
A shipbroker told BigMint, “Container freights remain slightly weaker than bulk, with fluctuating exchange rates leading to deal cancellations. Container rates may take at least a month to get in comparison with bulk market levels.”
With booking activity still uneven, the container market is likely to remain sensitive to exchange-rate movements, sailing availability and fresh cargo enquiries in the coming weeks.
Rice export prices edge higher; buyers remain selective
BigMint’s assessment for non-basmati parboiled rice (IR-64 5% PB), FOB Kakinada, increased by $2/tonne (t) to $375/t on 14 October, compared with $373/t in the previous week. Buyers continued to assess cargo prices alongside freight and other logistics costs.
The approaching new-crop season is influencing purchase timing, while rainfall deficits in parts of Andhra Pradesh have added uncertainty to supply expectations. This could keep buyers selective until crop availability and pricing become clearer.

Outlook
Bulk freights are expected to remain supported by port congestion, firm vessel offers and improving Atlantic Supramax activity, although cautious buying ahead of new-crop arrivals could limit further gains. Container rates are likely to remain mixed in the near term, with exchange-rate volatility, space availability and uneven cargo enquiries continuing to influence booking decisions.
Market participants expect activity to improve after Diwali as buyers return to the market and fresh enquiries emerge. However, the extent of any recovery will depend on actual fixing activity, shipment volumes and the availability of suitable vessels and container space.
Leave a Reply