- Festival disruptions, buyer resistance limit gains elsewhere
- Higher fuel costs, producer hikes support price sentiment
Indian cement trade prices remained broadly supported w-o-w, with gains in selected markets across the north, west, and central regions. Moderate buying and recent producer price hikes helped dealers raise offers in some markets. However, buyer resistance in parts of the south and subdued purchasing ahead of Durga Puja in the east limited broader price increases.
Market performance remained uneven, with local supply availability, dealer inventory, and acceptance of higher prices determining the extent of regional gains.
West: Supply tightness supports offers
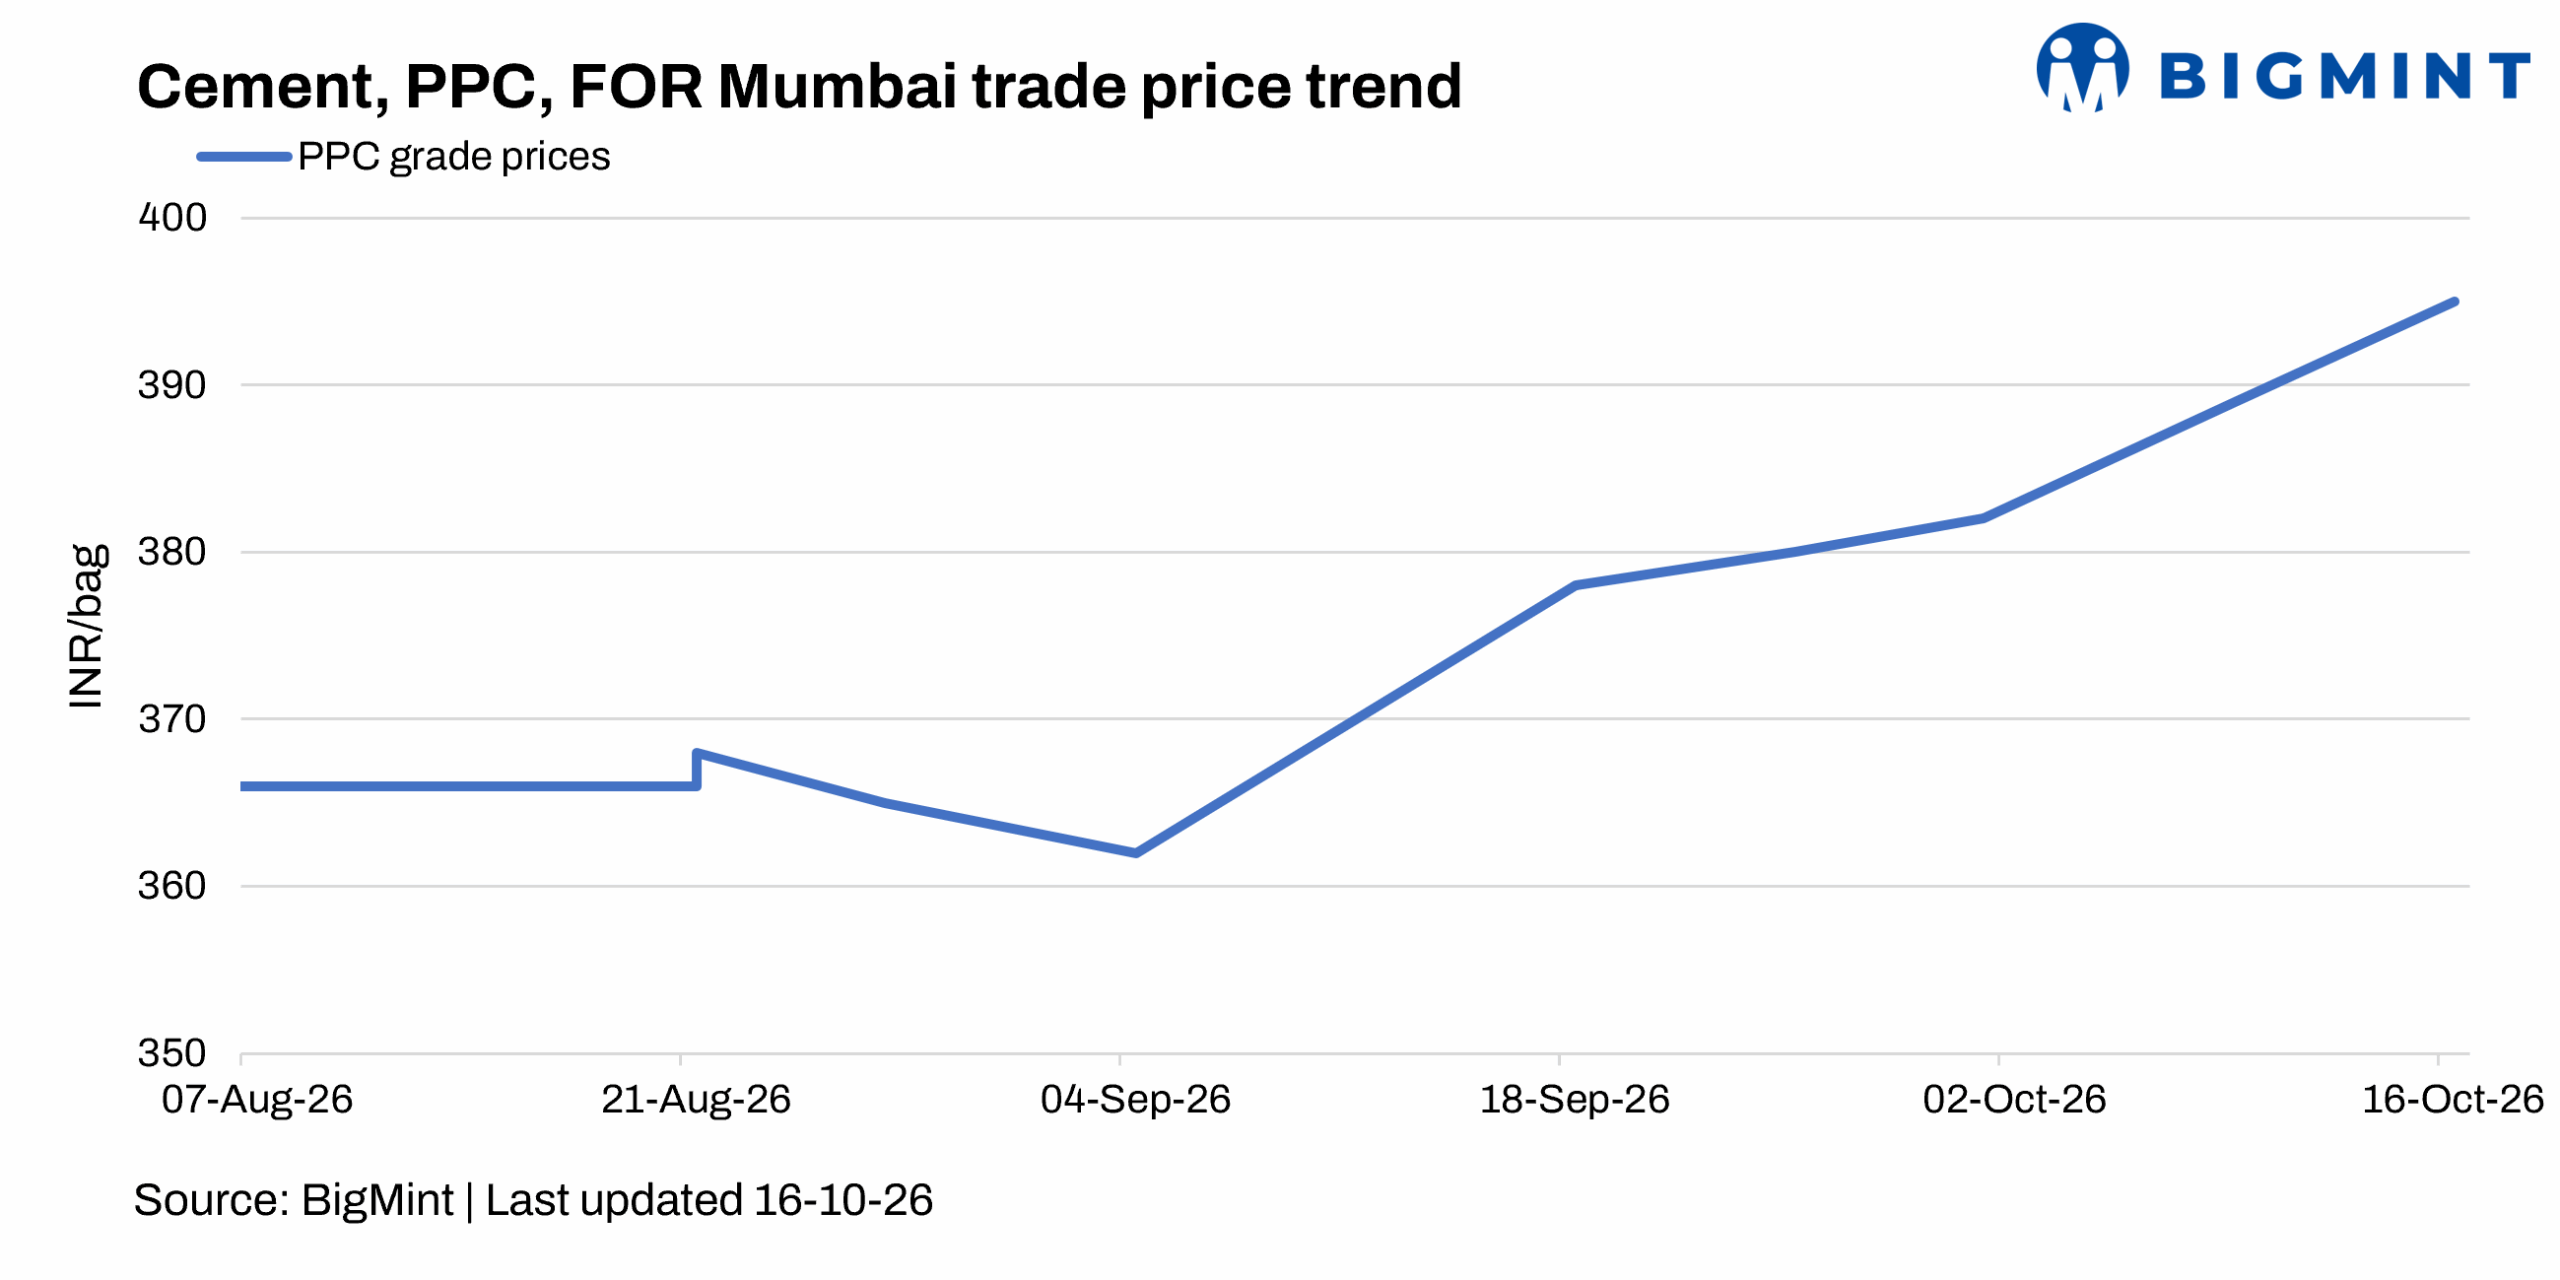
Cement prices increased in parts of western India as limited material availability in dealer channels supported offers. Buying activity improved to moderate levels, while recent producer price hikes encouraged dealers in Ahmedabad and Mumbai to raise billing prices. Prices increased by INR 6/bag w-o-w to INR 395/bag FOR Mumbai.
However, market conditions in Mumbai remained mixed. Water scarcity and potential disruption to construction and infrastructure activity could weigh on cement consumption, although the extent of the impact on weekly trade volumes requires confirmation.
East: Festival disruptions restrict transactions
Kolkata recorded subdued buying ahead of Durga Puja, with festival-related logistics disruptions limiting market activity. Manufacturers reportedly raised prices by around INR 10/bag, but the extent to which these increases translated into realised trade prices remained constrained by weak purchasing.
Reduced trading activity during the festival period also makes it difficult to assess underlying demand solely from weekly price movements.
South: Buyer resistance caps prices
Prices weakened in Chennai as buyers resisted higher offers. Meanwhile, Hyderabad dealers kept prices on the higher side despite weak sales, reflecting subdued market sentiment and limited acceptance of prevailing price levels. Prices dropped by INR 5/bag w-o-w to INR 334/bag FOR Chennai.
Bangalore prices remained largely stable amid subdued buying during the festival week. The divergence across southern markets highlights the influence of local inventory and purchasing conditions on price realisation.
Central: Producer hikes meet resistance
Raipur prices moved higher following producer price increases of INR 10-15/bag, effective from 10 October. Dealers subsequently raised offers, but buyer resistance and subdued purchasing limited further gains. Cement prices increased by INR 12/bag w-o-w in Raipur.
The market’s response suggests that announced price hikes do not necessarily translate into equivalent increases in realised transaction prices when demand remains weak.
North: Moderate buying supports prices
Delhi recorded a reported INR 5/bag increase in the trade segment. Moderate buying and end-user demand supported dealer billing prices, helping lift average trade prices w-o-w. Trade prices rose by INR 4/bag on the week to INR 352/bag FOR Delhi.
Outlook
Cement prices may remain supported in selected markets as producers seek to pass on higher fuel costs and implement announced price increases. Imported pet coke prices rose to $189/t CNF Vizag in October from $166/t in September, while non-coking coal prices ex-Bilaspur increased by INR 600/t m-o-m to INR 6,775/t.
Easing monsoon conditions and improving construction activity could support dealer offtake in some markets. However, further price gains will depend on buyer acceptance, inventory availability and the ability of producers to sustain increases beyond announced price revisions. Weak demand and dealer discounting remain key constraints in parts of south and central India.
Leave a Reply