- Thermal replenishment broadens as Mundra’s previous build partly clears
- Coking stocks fall despite increases at three major ports
Coal inventories at Indian ports covered by BigMint’s Week 41 assessment increased by 0.24 Mnt, or 1.3%, to 18.68 Mnt during 4-10 October 2026.
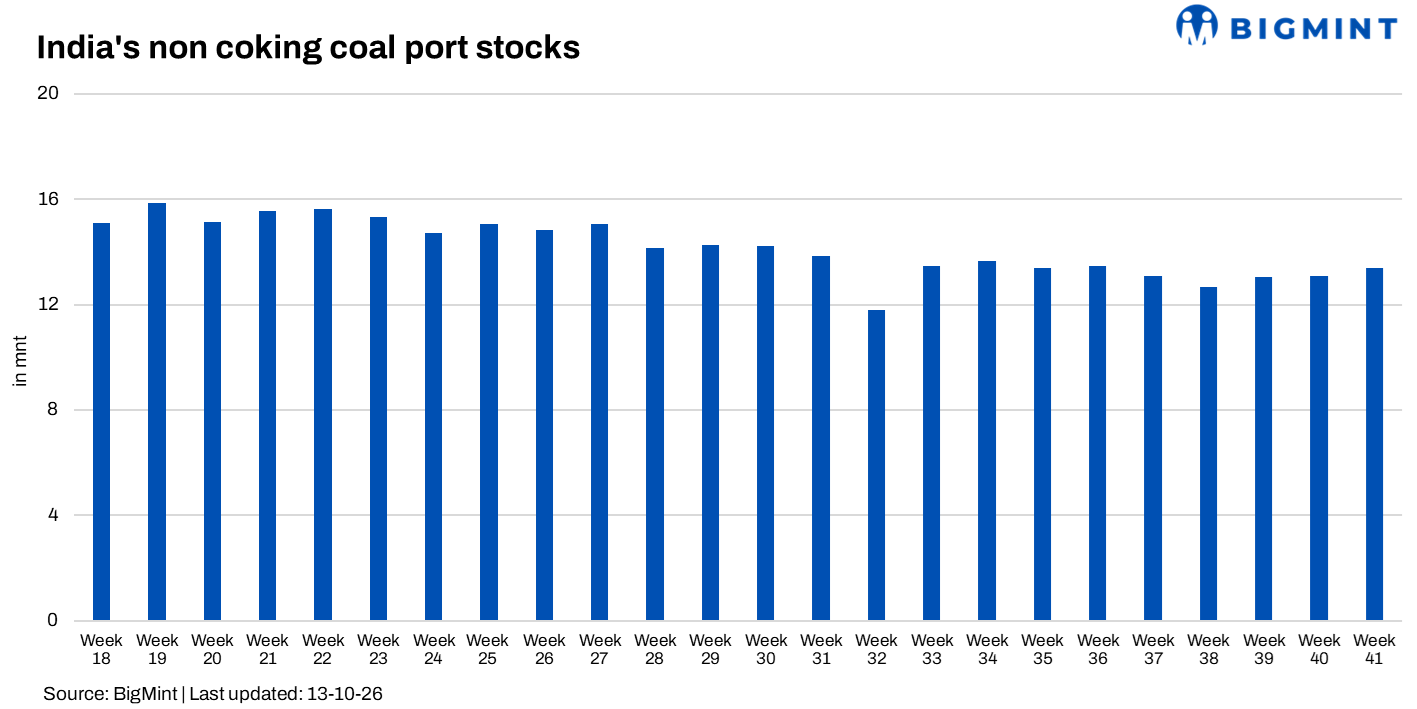
Non-coking coal stocks rose by 0.32 Mnt, or 2.4%, to 13.39 Mnt, while coking coal inventories declined by 0.08 Mnt, or 1.6%, to 5.28 Mnt.
The pattern changed from the previous week, when Mundra’s sharp build masked drawdowns elsewhere. This week, Mundra stocks declined, while replenishment spread across several other ports. However, the increase remains uneven across receivers and coal types, limiting what the higher headline inventory says about readily available supply.

Quantity in Mnt. Changes calculated from unrounded figures. Stocks are provisional; some Indian ports are outside the assessment.
Mundra’s build begins to unwind
Mundra’s total stocks declined by 4.7% to 2.31 Mnt, following the previous week’s 0.63 Mnt increase.
Non-coking inventories fell by 0.09 Mnt to 2.20 Mnt. CGPL/Tata holdings declined by approximately 0.18 Mnt to 0.72 Mnt, partly offset by a 0.09 Mnt increase in Adani Enterprises stocks to 0.92 Mnt. Adani Power holdings remained broadly steady at 0.56 Mnt.
The change shows that last week’s replenishment is partly clearing. Nevertheless, Mundra’s total inventories remain approximately 0.51 Mnt above their 26 September level.
Across the other covered ports, combined stocks increased by approximately 0.35 Mnt this week. Replenishment has therefore become more widely distributed.
Western trading stocks recover, but Kandla keeps drawing down
Magdalla recorded the largest absolute port-level increase, adding 0.19 Mnt to reach 0.82 Mnt. Green Gold holdings increased by approximately 0.10 Mnt, while Twenty First Century Landmark recorded nearly 0.06 Mnt against no reported holdings the previous week.
Navlakhi stocks recovered by 6.7% to 0.72 Mnt, supported by higher Green Gold, Aditya Birla and Agarwal Coal holdings. Dahej also replenished, largely through Adani Enterprises.
Kandla moved in the opposite direction. Stocks declined by 12.3% to 0.68 Mnt, with reductions at UltraTech Cement, Agarwal Coal, Balaji and Shri Cement. UltraTech holdings fell by approximately 0.05 Mnt to 0.29 Mnt.
Industrial replenishment was similarly mixed. Tata Chemicals holdings at Jamnagar increased to 0.22 Mnt, while Wonder Cement stocks at Tuna rose to approximately 0.055 Mnt. These increases coexist with continued drawdowns at other industrial and trading locations.
Coking replenishment remains concentrated
Paradip retained its position as the largest stockholding port, with inventories increasing to 2.62 Mnt.
Coking stocks rose by 0.10 Mnt to 1.36 Mnt, supported particularly by Jindal Steel & Power. Non-coking holdings increased by 0.05 Mnt to 1.26 Mnt, with increases at Tata Steel, Jindal Steel & Power and Shyam Group partly offset by reductions elsewhere.
Gangavaram’s coking stocks increased by 0.09 Mnt to 0.86 Mnt, while Vizag added approximately 0.08 Mnt to reach 1.09 Mnt.
However, these builds were outweighed by reductions at Dhamra, Krishnapatnam, Haldia, Goa and Mundra. Krishnapatnam’s coking inventory fell by 60.8% to approximately 0.06 Mnt, reversing much of the previous week’s replenishment.
At Dhamra, coking stocks declined by 0.11 Mnt, while non-coking inventories increased by almost the same amount. Its broadly unchanged total therefore conceals a substantial shift between fuels.
Arrivals show continued onward movement
The available vessel records identify substantial arrivals even at ports where stocks declined or barely increased.
Mundra recorded approximately 0.38 Mnt of non-coking arrivals during 4-8 October, while its weekly non-coking stock fell by 0.09 Mnt. Together, these figures suggest approximately 0.47 Mnt of onward movement.
At Hazira, identified arrivals of 0.26 Mnt alongside a stock increase of only 0.02 Mnt indicate approximately 0.24 Mnt of clearance. Kandla’s 0.08 Mnt of arrivals and 0.10 Mnt stock reduction imply approximately 0.18 Mnt.
These are indicative balance calculations, rather than reported evacuation figures. Vessel records end on 8 October, two days before the stock assessment, and may omit other receipts.
BigMint assessment
Week 41 shows broader thermal coal replenishment alongside continued movement out of ports. The aggregate increase offers some improvement in the coastal supply buffer, but availability remains uneven.
For buyers, the relevant question is how much suitable coal is available at their supply port and which holders control it. Stocks assigned to power companies or steelmakers may serve their own requirements, while trader-held inventories form a different supply pool.
The next test is whether the expanding import pipeline replenishes ports experiencing repeated drawdowns. Until then, higher national port stocks alone provide limited reassurance to consumers facing tight fuel availability and elevated replacement costs.
Leave a Reply