- Firm iron ore realisations and limited selling pressure support market
- Pellet offers from Raipur remained firm amid selective buying
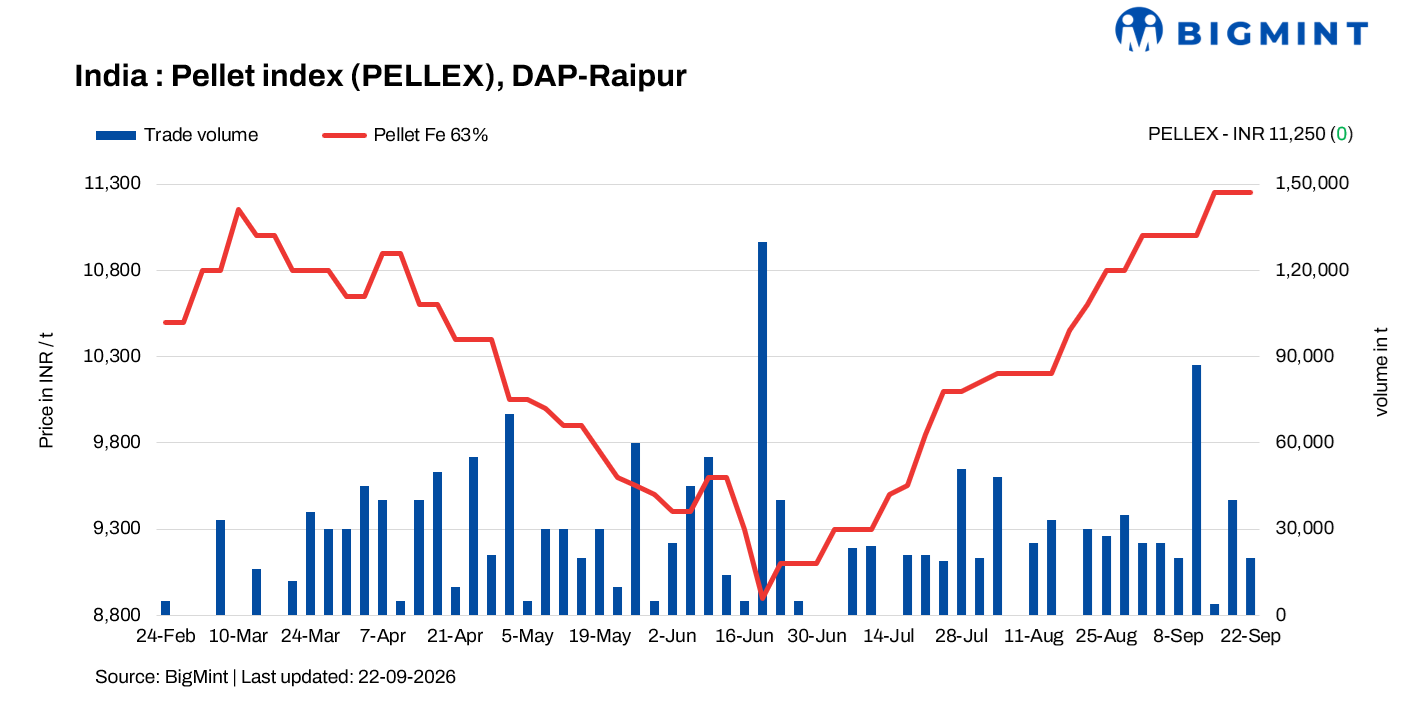
PELLEX, BigMint’s bi-weekly domestic pellet (Fe 63% +/- 0.5%) index for Raipur remained unchanged at INR 11,250/t DAP Raipur on 22 September 2026 against 18 September.
The market continued to draw support from elevated iron ore costs following Odisha Mining Corporation’s (OMC) latest auction held on 19 September. Around 50-53% of the offered iron ore quantity was booked, while lump bookings were comparatively better at around 80%. Despite relatively limited overall bookings, the material sold largely cleared at firm premiums, keeping iron ore realisations elevated and supporting pellet replacement costs.
Rationale
- PELLEX has been derived using data points, i.e., trades, offers, and bids. To download the detailed methodology, click here.
- One (1) deals were recorded in this publishing window and was taken for calculation. Thus, the T1 trade category was accorded a weightage of 50%.
- Twenty (20) firm offers, bids, and indicative prices were heard, of which nineteen (19) were taken for price calculation and given the balance 50% weightage.
Price movements and offers
Major pellet manufacturers in Chhattisgarh largely maintained their offers for Fe 62.5/63% (+/-0.5%) grade pellets in line with the previous assessment. Sellers showed limited inclination to reduce prices, supported by elevated iron ore costs and firm sponge iron and billet prices.
Around 20,000 t of pellet deals for (Fe 63% +/- 0.5%) were reported during the assessment period. While buying remained selective at current price levels, sellers continued to maintain reasonably healthy order books and were not under significant pressure to liquidate material.
Market scenario
The Raipur pellet market remained firm, with high iron ore costs and limited selling pressure keeping prices supported. The latest OMC auction provided further cost support, as booked material largely cleared at firm premiums despite relatively limited overall sale volumes.
Lump availability in the market is currently reported to be relatively tight, while lump prices have also moved to elevated levels. This has encouraged some consumers to consider pellets as an alternative raw material, particularly given the potential for better yields in sponge iron production.
However, high prices of both pellets and lumps have made buyers increasingly cautious. Market participants indicated that consumers are evaluating whether to procure at prevailing levels or wait for a possible correction. Buyers in Raipur and Bilaspur have expressed expectations of some downward revision in the near term, although sellers currently see limited scope for a broad-based correction.
Some pellet-selling plants in Raipur were also heard to be temporarily unavailable for fresh offers, keeping spot availability selective. Nevertheless, sellers continue to report reasonably healthy order books.
On the downstream side, firm sponge iron and billet prices are providing support to pellet realisations. At the same time, weak sponge iron margins are influencing production decisions across some mills in Eastern and Central India.
Market sources indicated that the resulting pressure on margins has prompted some integrated and captive-power-based producers to reportedly reduce or temporarily halt sponge iron production.
Some such producers are understood to be diverting available power to the grid, where realisations are around INR 10/unit, instead of continuing sponge iron production at current economics. Any sustained reduction in sponge iron output could keep availability relatively constrained and provide some support to downstream and raw-material prices.
However, the impact on pellet demand remains mixed. While tighter sponge iron availability can support the broader ferrous market, high pellet prices are simultaneously encouraging consumers to remain cautious on fresh procurement.

Key market drivers
- Sponge iron prices edge down w-o-w: Sponge PDRI prices stood at INR 28,100/t ($305/t) exw Raipur, softening by INR 1,350/t w-o-w on 22 September against 15 September. The fall was mainly driven by weak finished steel demand and limited acceptance of prices at higher levels. Overall market sentiment remained slow and bearish today due to sluggish demand in the finished steel segment. Sponge iron prices also dropped, while finished steel fell by Rs 200-500/t across regions. Sellers reduced offers to attract buyers, but enquiry levels remained very poor in the market, and no bulk deals were observed.
- Billet prices edge down w-o-w: BigMint’s billet index in Raipur fell by INR 400/t ($4/t) to INR 44,000/t ($460/t) exw on 22 September 2026 against 15 September. Subdued demand continued to weigh on market activity, while buyers remained cautious amid uncertainty. Continued weak demand weighed on trading activity and triggered further corrections in spot offers. Buyers maintained a cautious approach, while sellers lowered prices to revive trade. However, limited buyer participation kept market sentiment weak during the session.
Outlook
Leave a Reply