- Global fines prices weaken further; trading fails to recover post-holiday
- Rising Chinese port inventories, falling futures weigh on sentiment
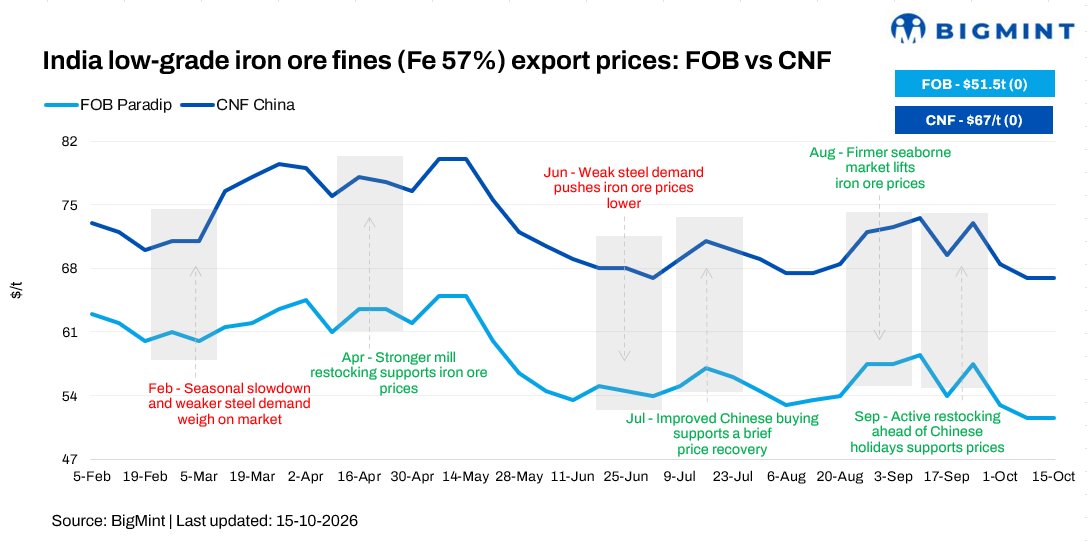
Indian low-grade iron ore fines (Fe 57%) export prices remained flat w-o-w on 15 October, as global fines prices continued to weaken and post-holiday trading activity failed to recover. Despite supportive market sentiment, no fresh transactions were reported, with buyers remaining cautious and sellers reluctant to accept lower prices amid difficult export economics.
Indicative prices for Indian iron ore fines (Fe 57%) stood at $50/t FOB east coast (equivalent to $65/t CFR China). Discounts for lower-grade material remained broadly unchanged, reflecting continued pressure on lower-grade fines.
Market activity remained limited following the holiday break, with no fresh export transactions reported. Buyers showed limited interest at prevailing levels, while sellers maintained offers above buyer expectations, preventing deals from materialising.
Moreover, Chinese iron ore inventories across 34 major ports increased by 1.23 million tonnes (mnt) w-o-w to 139.24 mnt in week 42 of CY’26, from 138.01 mnt a week earlier. The rise in port stocks amid subdued steel demand and cautious mill restocking reflects a slower pace of inventory absorption, adding to the bearish sentiment in the iron ore market. Persistently high stock levels may continue to weigh on prices unless steel production and procurement activity improve.
Rationale
- No deals were reported during the current publishing window; consequently, T1 trades received 0% weightage in the index calculation.
- BigMint received fifteen (15) indicative price inputs, of which eight (8) qualified as T2 inputs and accounted for the 100% weightage.
During the week over 3-9 October 2026, total Indian iron ore export shipments declined significantly by 48.11% to 60,500 t from 116,600 t recorded in the previous week (26 September-2 October). This weekly contraction was driven by a complete absence of activity at Mormugao Port, which had exported 60,500 t via Vedanta in the previous week.
On the other hand, Krishnapatnam Port remained the sole active port during the week under review, loading 60,500 t (via Minera Steel and Power), representing a slight 7.84% increase compared to the 56,100 t shipped through the port (via A One Steels) a week before. All other major ports, including Paradip, Haldia, and Kakinada, recorded no export shipments across both weeks.
Domestic-export price gap widens amid weak export realisations
The spread between domestic and export realisations widened to around INR 1,079/t ($11.4/t) this week, as export realisations remained under pressure while domestic low-grade iron ore prices held steady. Export realisations stood at around INR 2,427/t ($25.6/t), compared with domestic low-grade iron ore prices of INR 3,600/t ($37.9/t) ex-mines.
The persistent gap highlights the relatively weaker returns from exports, limiting their competitiveness against domestic sales. With global prices subdued and Chinese buying cautious, export economics are likely to remain challenging unless international prices improve or domestic-export price differentials narrow.
Iron ore prices decline amid weak Chinese steel demand, cautious mill restocking
Global benchmark iron ore (Fe 61%) prices declined by $1/t w-o-w to $90/t CFR China on 14 October 2026, from $91/t on 7 October. Prices remained under pressure amid subdued steel demand in China, cautious procurement by mills and limited signs of a sustained recovery in iron ore consumption following the Golden Week holiday. Elevated port inventories and weak finished steel demand continued to weigh on market sentiment, while buyers remained reluctant to build stocks aggressively. The marginal decline reflects persistent demand-side concerns, with market participants closely monitoring steel production trends and restocking activity for clearer price direction.
January 2027 iron ore futures on the Dalian Commodity Exchange (DCE) declined by RMB 11/t ($1.6/t) w-o-w to RMB 671.5/t ($100.3/t) on 15 October. Weak steel demand, elevated port inventories and cautious mill restocking continued to weigh on market sentiment, limiting prospects for a near-term price recovery.
Outlook
Indian low-grade iron ore fines export activity is likely to remain subdued over the next couple of weeks as buyers and sellers maintain a wait-and-watch approach. A recovery in trading would depend on stabilisation in global fines prices and improved alignment between buyer bids and seller expectations. However, continued weakness in international prices could keep export realisations under pressure.
Leave a Reply