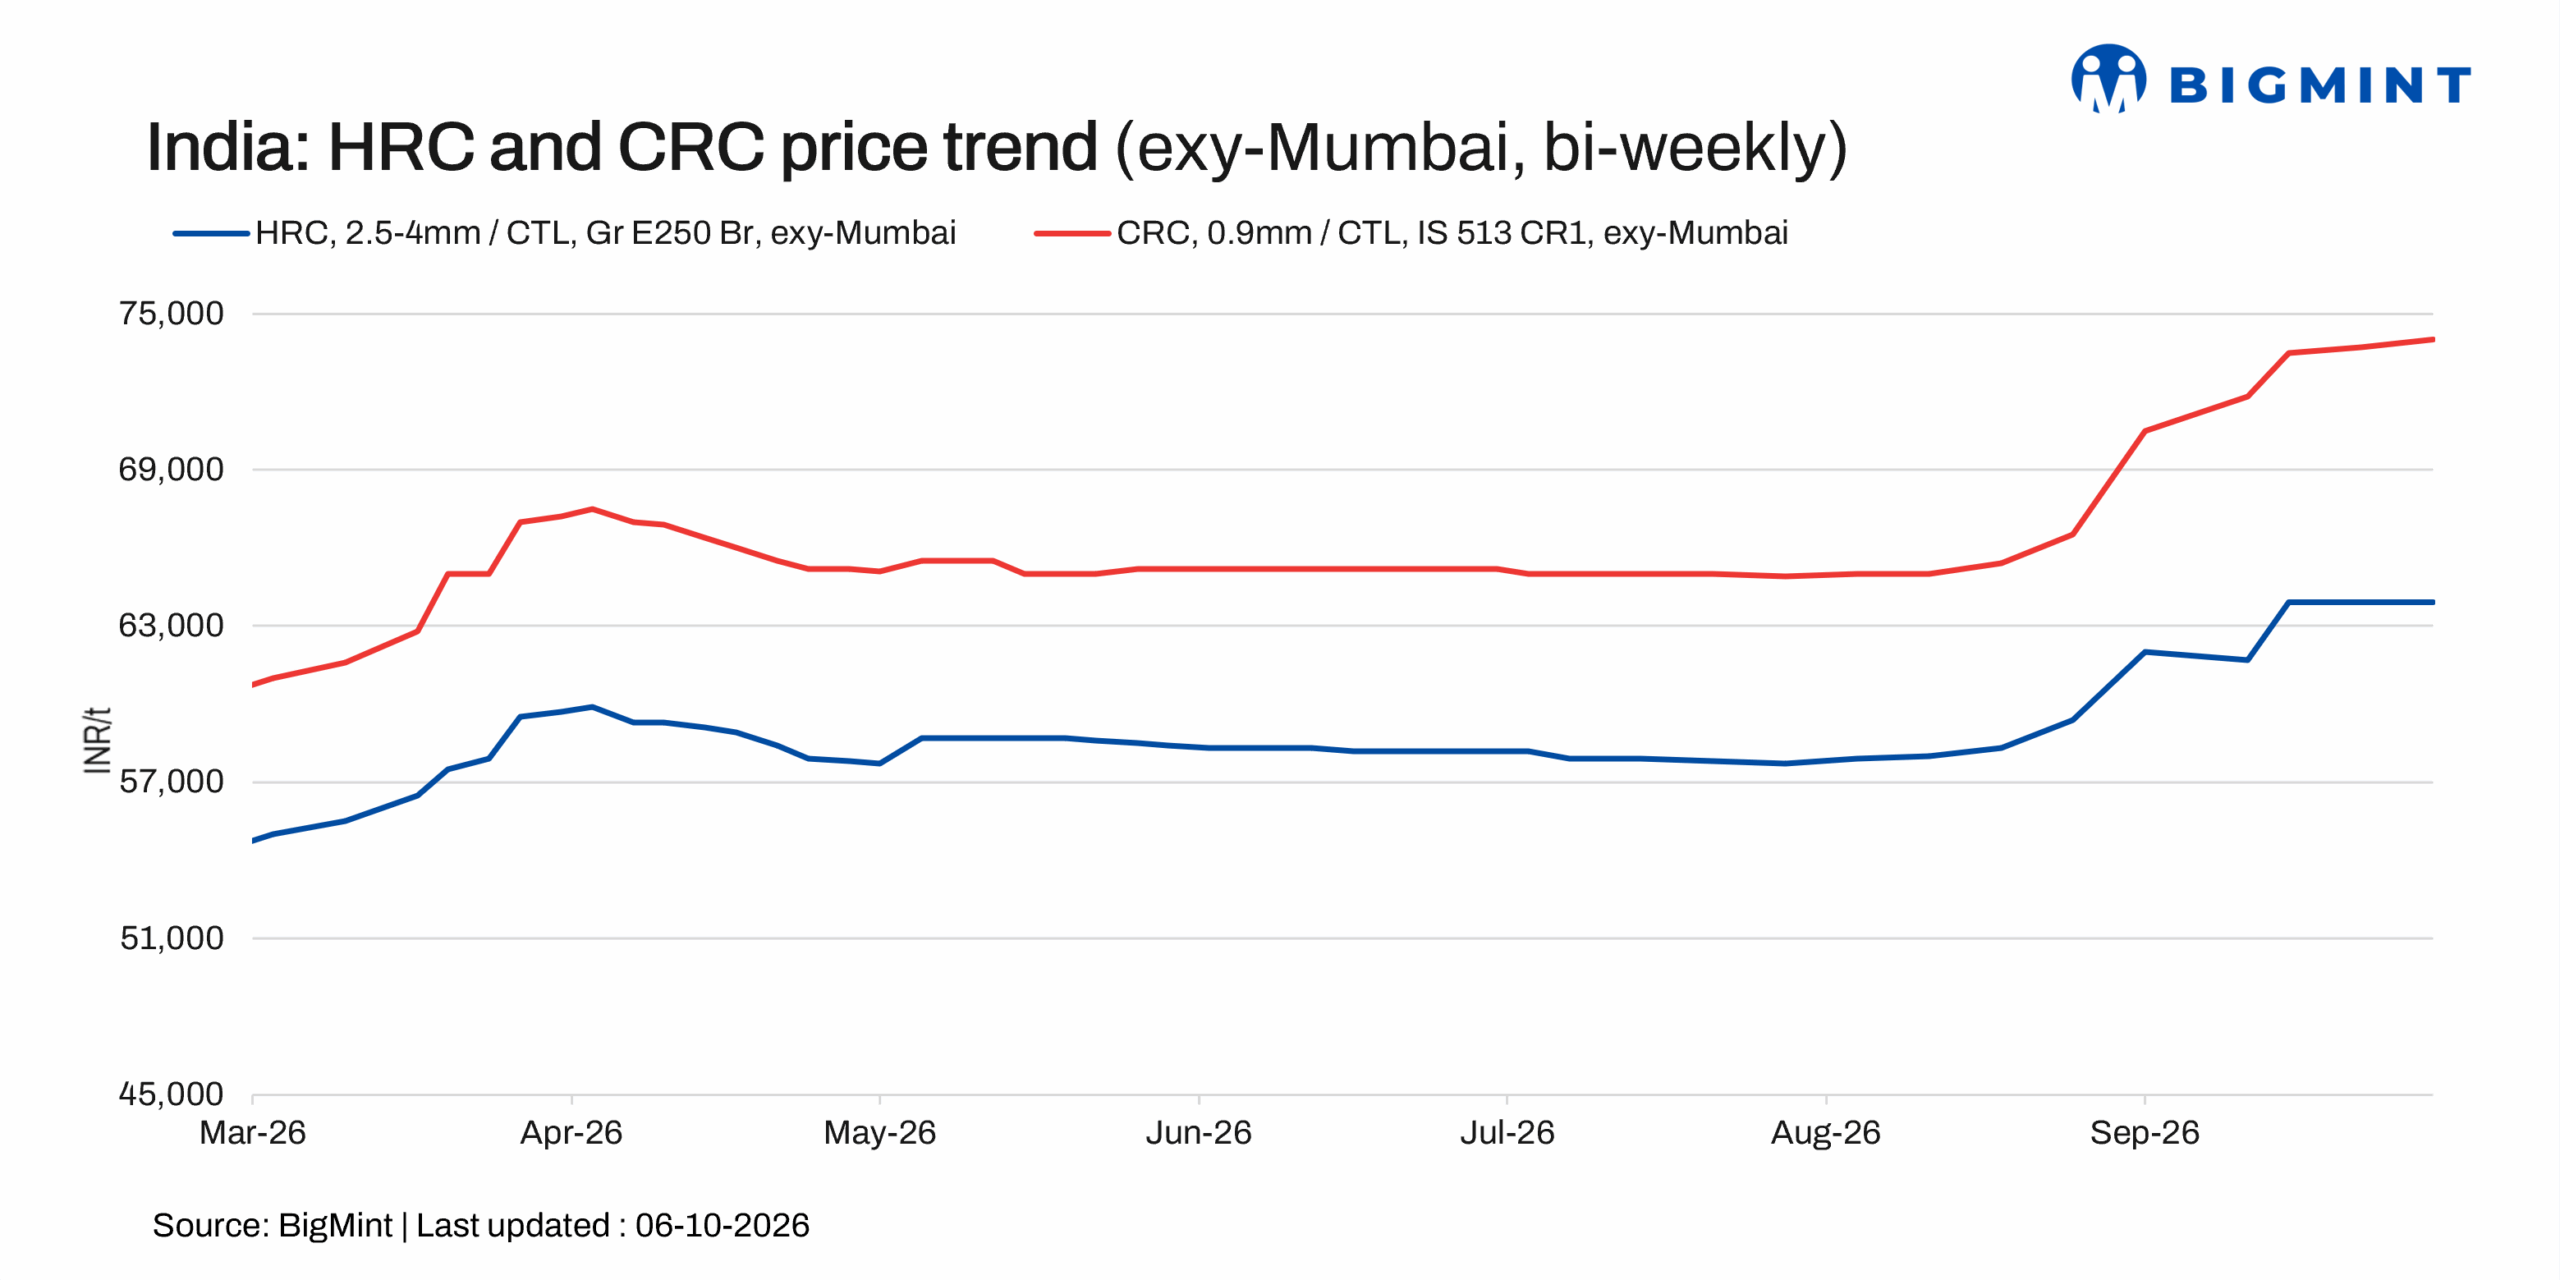
- Higher offers face cautious market response
- Inventory remains comfortable across key markets
India’s hot-rolled coil (HRC) trade-level prices increased by around INR 100-800/t w-o-w across key markets, supported by improved buying activity and higher offers.
Cold-rolled coil (CRC) trade prices also increased by around INR 200-1,800/t w-o-w in key markets, with higher offers and firm buying interest supporting the price movement.
BigMint’s bi-weekly benchmark assessment for Mumbai HRC (2.5-8 mm/CTL, IS 2062, Grade E250 BR) increased by INR 800/t w-o-w to INR 64,700/t ex-Mumbai as of 6 October from INR 63,900/t in the previous assessment.
Meanwhile, Mumbai CRC (0.90 mm/CTL, IS 513, CR1) was assessed at INR 74,800/t ex-Mumbai, up INR 800/t w-o-w from INR 74,000/t in the previous assessment.

Market updates:
HRC and CRC prices have increased across key markets following recent price hikes announced by major domestic steel mills. Major mills raised HRC list prices by INR 750-1,500/t and CRC by INR 750-2,000/t. The increase has been partially reflected in the trade market, although the full extent of the mill hikes has not yet been passed through.
In western India, demand remains largely need-based, with buyers continuing to procure mainly for immediate requirements. While prices have moved higher, buying interest remains measured and has not fully matched the recent increase in mill offers.
In south India, demand remains mixed. Some market participants reported good enquiries and relatively better buying activity, while others described demand as largely need-based and moderate. Higher mill offers have supported prices, but buyers remain cautious at elevated levels.
In the north, demand continues to be largely requirement-driven, with buyers mainly purchasing for immediate needs. Buying activity remains moderate, with no significant improvement in overall consumption reported.
Inventory levels remain comfortable across markets, with ample material currently available with traders and distributors. This relatively high inventory availability is limiting the urgency among buyers and keeping procurement largely need-based despite recent mill price hikes.
Overall, market demand remains mixed and largely requirement-based, while supply is comfortable due to ample inventory. Although recent HRC and CRC mill price hikes have pushed trade prices higher, the full increase has not yet been absorbed by the market. Near-term price movement will depend on the extent of further mill hikes, inventory liquidation and improvement in underlying demand.
Trade activity:
Import volumes:
India’s bulk HRC imports stood at 136,802 tonnes (t) in September, with a further 80,451 t expected to arrive by the end of October. A significant portion of these imports is being undertaken under long-term agreements between Indian companies and their parent entities in South Korea and Japan.

Export volumes:
India’s bulk HRC exports stood at 299,413 t as of September.
Outlook
HRC and CRC prices are expected to remain firm in October, with market participants indicating a potential upside of around INR 1,000-1,500/t. However, the increase is likely to be gradual as buying remains largely need-based and inventory availability is comfortable.
Further price movement will depend on trade-level absorption of higher mill offers, inventory reduction and improvement in underlying demand. If buying activity strengthens, the market could see further upside; otherwise, ample availability may limit the extent of the increase.
Leave a Reply