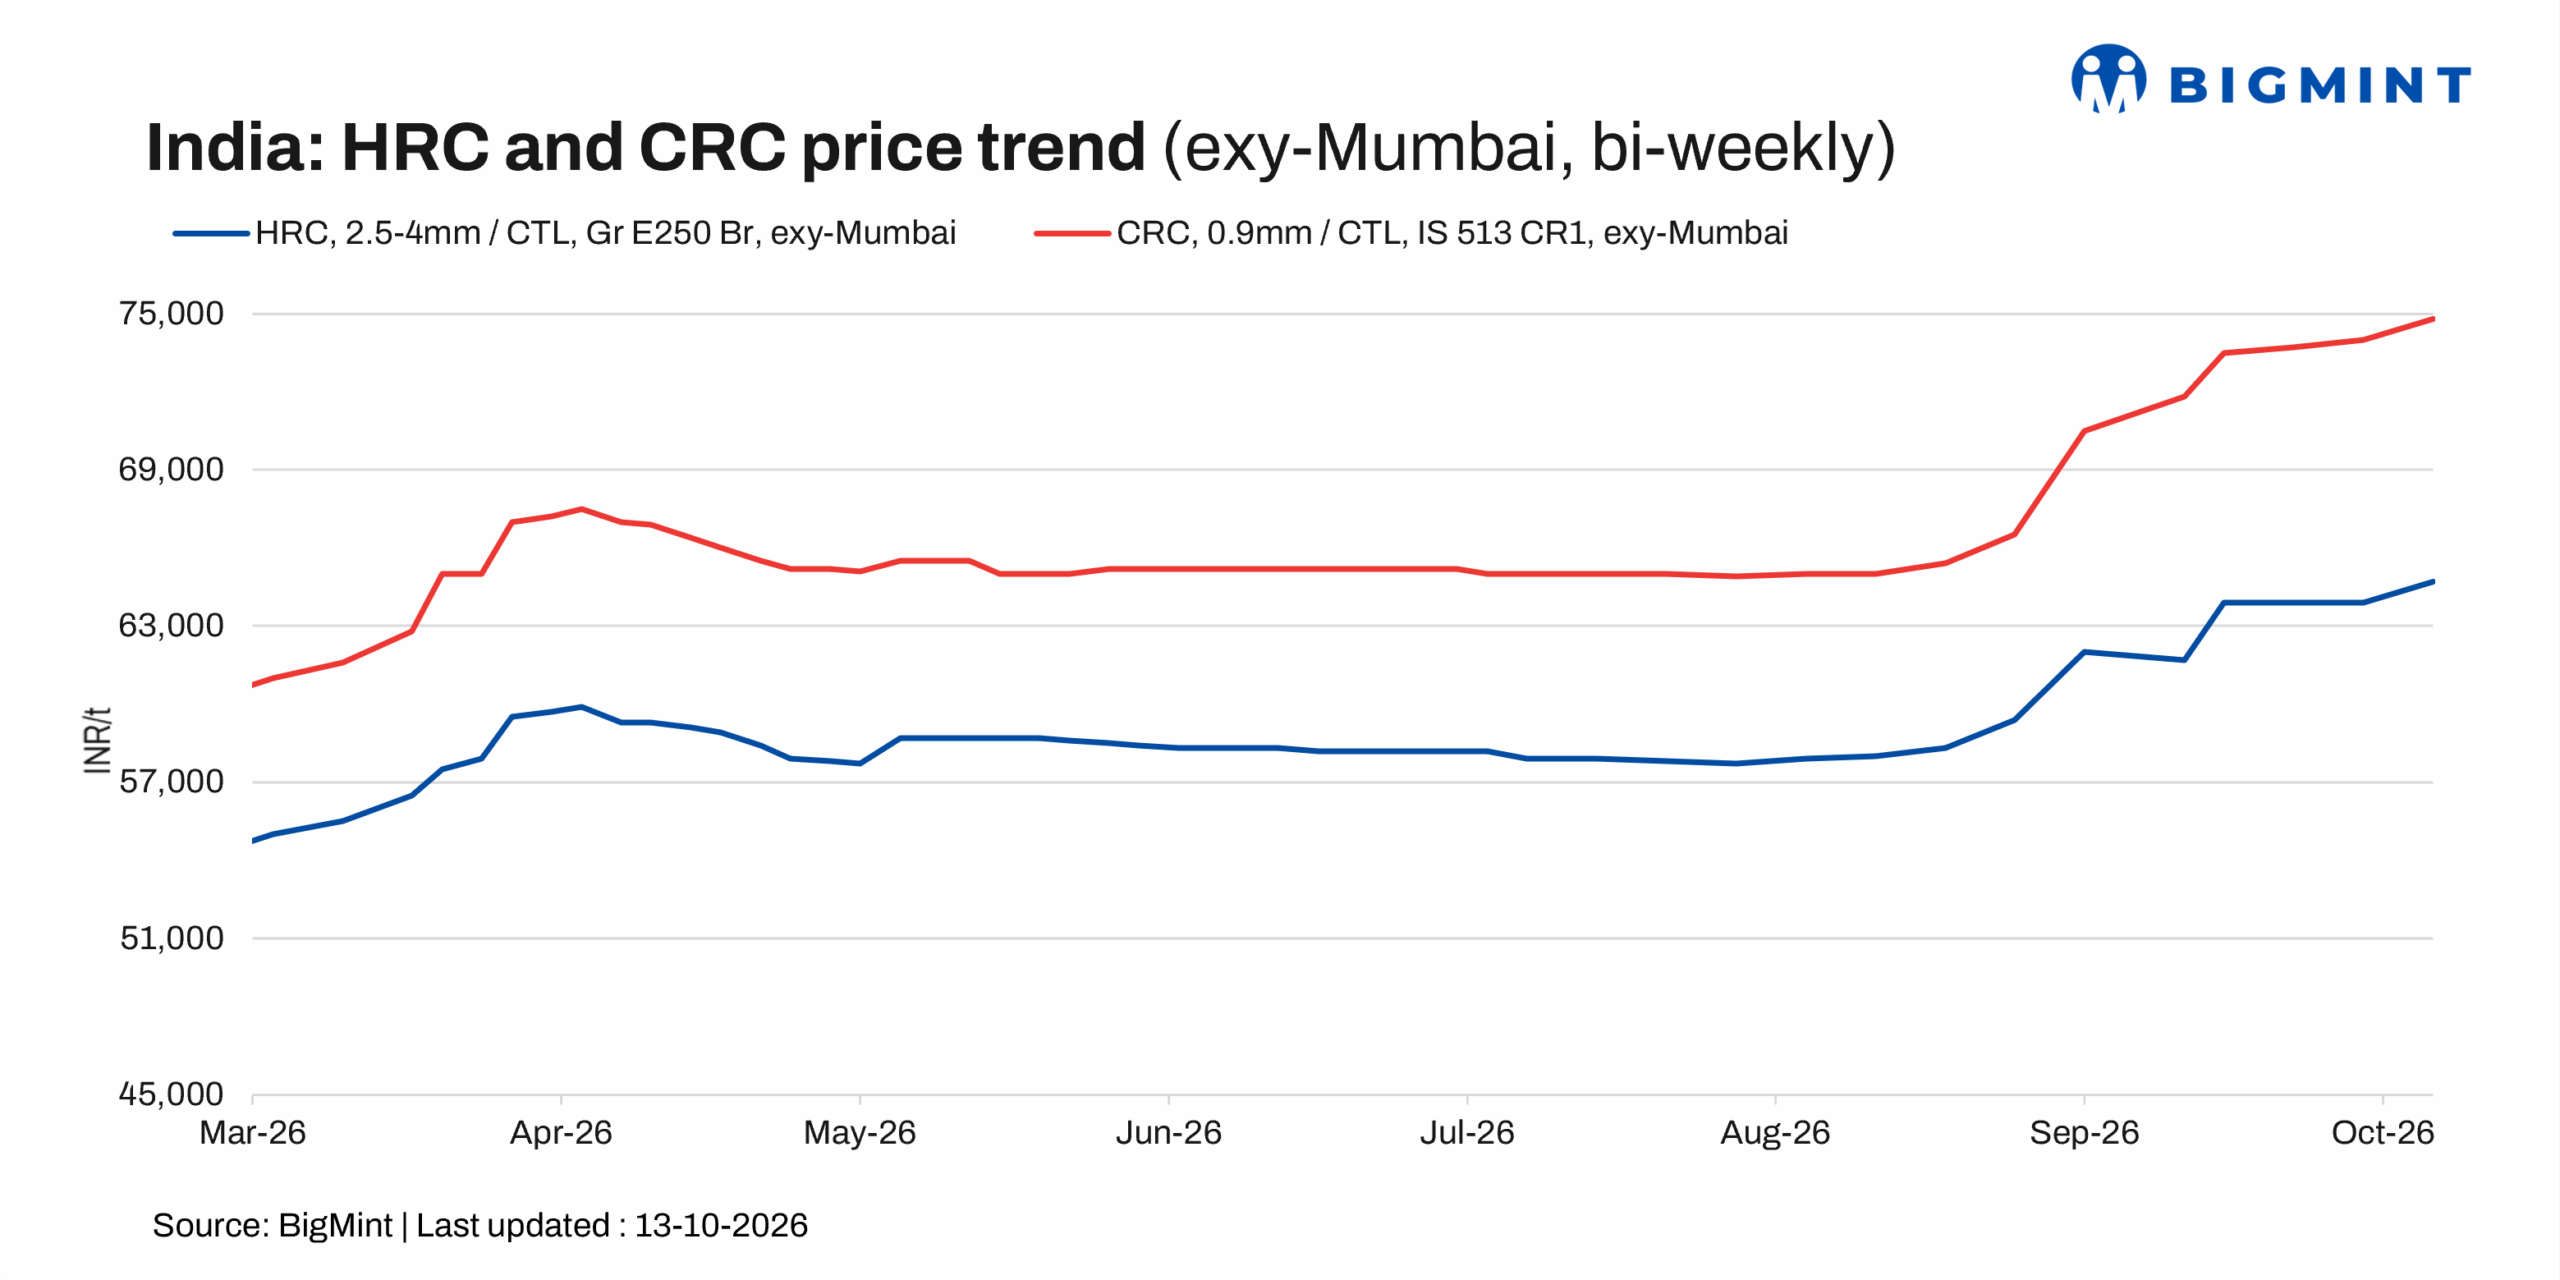
- Sellers liquidate inventory at lower prices to manage cash flows ahead of festive season
- Prices in southern markets rise amid moderately strong demand despite cautious sentiment
India’s trade-level hot-rolled coil (HRC) prices declined by INR 100-900/t w-o-w across most markets, as per BigMint’s assessment on 13 October 2026, as festive season liquidity constraints prompted inventory liquidation. However, prices in southern markets increased by INR 200-600/t due to demand remaining moderately strong in the south despite cautious buyer sentiment.
Trade-level cold-rolled coil (CRC) prices declined by INR 400-800/t w-o-w in select markets, while increases of INR 100/t were recorded in others. Overall, prices showed mixed movements across key markets.
BigMint’s bi-weekly benchmark assessment for Mumbai HRC (2.5–8 mm/CTL, IS 2062, Grade E250 BR) decreased by INR 700/t w-o-w to INR 64,000/t ex-Mumbai as of 13 October 2026, from INR 64,700/t in the previous assessment on 6 October.
Meanwhile, Mumbai CRC (0.90 mm/CTL, IS 513, CR1) was assessed at INR 73,800/t ex-Mumbai as of 13 October, down INR 1,000/t w-o-w from INR 74,800/t in the previous assessment on 6 October.

Market updates
HRC and CRC trade-level prices showed mixed movements across key markets due to liquidity constraints ahead of the upcoming festive period, which prompted some traders and distributors to liquidate inventory at relatively lower prices to manage cash flows.
In western India, demand was largely need-based, with buyers continuing to procure mainly for immediate requirements. Liquidity constraints and efforts to liquidate existing inventory put downward pressure on prices in some markets, as sellers prioritised stock clearance and cash flow management ahead of the festive period.
In southern India, HRC and CRC prices increased in some markets, supported by relatively better, though moderate, demand. Market participants indicated that buying interest was sufficient to support prices, although procurement continued to be cautious amid elevated price levels and the approaching festive period.
In the CRC segment, there was a shortage of thinner-gauge material, which provided some support to prices for these specifications despite the mixed trend across the broader market. Limited availability of specific gauges contributed to price variations across markets.
Inventory levels remained relatively comfortable overall, although availability varied by product and specification. The need to liquidate stocks and manage working capital ahead of the festive period resulted in varied pricing strategies, with some sellers offering discounts to generate liquidity, while the shortage of thinner-gauge CRC supported prices of certain specifications.
Trade activity
Import volumes: India’s bulk HRC imports stood at 55,654 tonnes (t) as on 13 October 2026, with a further 85,567 t expected to arrive by the end of November. A significant portion of these imports is being undertaken under long-term agreements between Indian companies and their parent entities in South Korea and Japan.

Export volumes: India’s bulk HRC exports stood at 45,230 t as of 13 October 2026. Another 3,000 tonnes are expected to be shipped by next week.
Outlook
HRC and CRC prices are expected to remain firm, with a slight upward bias in the near term, supported by expectations of improved demand following the festive season and relatively slower supply from some major domestic steel mills. Although buying activity may remain moderate during the festive period, the anticipated improvement in demand is likely to support prices.
Leave a Reply