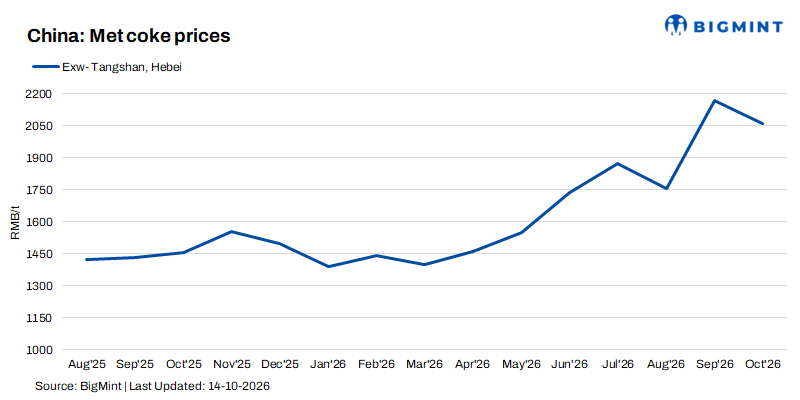
- China’s met coke prices have fallen RMB 200-220/t since 1 October 1
- Rising coking coal costs may limit next price cut to RMB 50-55/t
China’s second round of metallurgical coke price cuts took effect nationwide on October 12, bringing cumulative reductions to Yuan 200-220/tonne ($30-33/t) since October 1. A third round is expected amid persistent headwinds in the steel market, though resistance from coke producers may intensify.
Mysteel Coke Index (MCI) CDQ, which tracks China’s national dry-quenched quasi-first-grade met coke prices, dropped Yuan 107.7/t from the last session to Yuan 2,107.9/t on Monday, while the MCI CWQ for wet-quenched quasi-first-grade met coke also lost Yuan 89.1/t to Yuan 1,956.2/t, both including VAT.
On Monday, two leading Chinese steel groups — Hebei Iron and Steel Group (HBIS) and Rizhao Steel Holding Group — announced cuts of Yuan 100/t and Yuan 110/t, respectively, to their wet- and dry-quenched met coke purchasing prices, effective the same day, pushing the second round of price reduction, originally proposed by some northern mills on October 9, to materialize across the country.
Following the latest adjustments, prices set by the HBIS came in at Yuan 2,130/t for stamp-charged wet-quenched first-grade met coke (CSR≥65%) and Yuan 2,545/t for top-charged dry-quenched first-grade cargoes, on a DDP basis, inclusive of VAT, Mysteel learned.
Rizhao Steel’s prices were also revised lower to Yuan 1,945/t and Yuan 2,245/t for wet- and dry-quenched quasi-first-grade met coke (CSR≥60%), respectively, while the price of second-grade product (CSR≥58%) was pegged at Yuan 1,885/t. All three prices are for stamp-charged coke on a DDP basis, inclusive of VAT.
In parallel, the prevailing offers for dry-quenched quasi-first-grade met coke in Lvliang, North China’s Shanxi province, fell to Yuan 2,070-2,080/t on October 12, while those for dry-quenched first-grade material stood at Yuan 2,180-2,190/t, both on an EXW basis, inclusive of VAT, Mysteel learned from sources.
Sources shared that operators of top-charged coke ovens in Shanxi province were generally incurring losses of Yuan 80-100/t following the latest price cuts, while stamp-charged coke producers were making marginal profits.
Meanwhile, coking coal prices have staged a modest recovery recently, suggesting that cost pressures on coke producers have yet to ease. Combined with the latest decline in coke prices, this is expected to strengthen resistance to a third round of cuts. As a result, the next reduction could be capped at Yuan 50-55/t and become the final round in the current phase, Mysteel noted.
In the steel market, downstream restocking picked up modestly after the holiday, but the recovery in demand proved short-lived. Trading of higher-priced materials remains subdued, suggesting that a sustained rebound in steel prices is still elusive, Mysteel observed.
The coke futures, however, extended their rally on Monday. On the Dalian Commodity Exchange (DCE), the most-traded coke contract for next January delivery closed the daytime trading session at Yuan 2,022.5/t, up 1.53% from the previous session.
The portside met coke market edged down yesterday, as traders lowered offers amid falling coke prices at production hubs. Mysteel assessed wet-quenched quasi-first-grade coke (CSR 60%) and first-grade coke (CSR 65%) at Yuan 1,880/t and Yuan 1,980/t ex-stock Rizhao port, respectively, both down Yuan 50/t from the previous session and including VAT. The price of dry-quenched quasi-first-grade coke likewise fell by Yuan 40/t to Yuan 2,000/t.
Note: The article is published as part of a content sharing agreement between Mysteel Global and BigMint.
Leave a Reply