- Meghalaya plant closures tighten supplies
- BIS licences expire for 2 Bhutanese suppliers
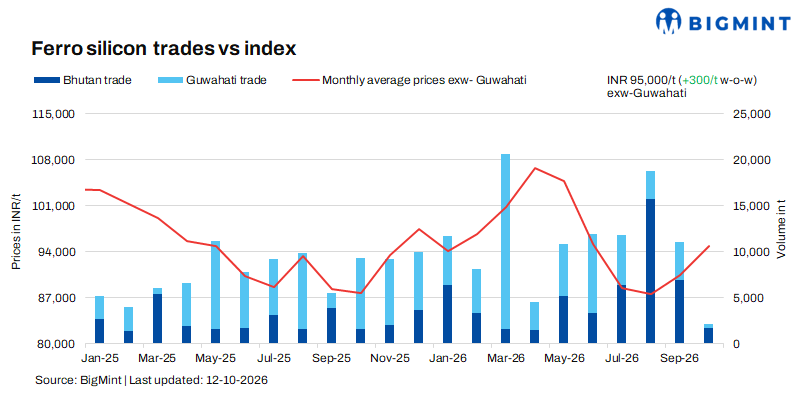
Indian ferro silicon (Si:70%) prices increased slightly by INR 300/t ($3/t) w-o-w to INR 95,000/t ($999/t) exw-Guwahati. In Bhutan, prices edged up by INR 600/t ($6/t) w-o-w to INR 94,600/t ($994/t) exw. Prices remained supported amid tight supplies in the Northeastern region and firm offers in Bhutan.
Last week, deals were reported for Bhutan for only around 1,200 t traded within a price range of INR 93,500-94,500/t ($983-993/t) exw.
Market updates (6-12 October)
Supply constraints keep prices supported: Indian ferro silicon supplies remained tight last week as plants in Meghalaya continued to remain closed, limiting domestic availability. Sellers in Arunachal Pradesh were also largely sold out for the month, leaving Bhutan as the primary source for reported trades. However, overall buying activity stayed cautious as buyers preferred to purchase on immediate basis only.
In Bhutan, offers remained firm amid limited availability, supported by the expiry of BIS licences for two plants and reported shortages of coke and charcoal. These factors constrained supply and limited sellers’ flexibility to offer material at lower prices. With domestic production yet to recover and availability from Arunachal Pradesh largely committed, market participants continued to rely on Bhutanese supplies. Going forward, price trends will depend on production resumption in Meghalaya, raw material availability and the status of BIS licences in Bhutan.
Firm costs support Chinese prices: China’s ferro silicon prices stood at RMB 6,350/t ($849/t) on 12 October. Firm input costs continue to support prices, while normal production kept supply steady. However, weak downstream demand, limited steel mill tenders and need-based procurement continued to restrict buying momentum, keeping the market balanced and trading subdued.
ZCE futures update: Ferro silicon futures on the Zhengzhou Commodity Exchange (ZCE) for December deliveries stood at RMB 5,970/t ($892/t) on 12 October.

Outlook
Indian ferro silicon prices are expected to remain firm in the coming week, supported by tight domestic supplies, firm Bhutanese offers and raw material shortages. Continued plant closures in Meghalaya and limited availability from Arunachal Pradesh are likely to sustain supply-side pressure. However, cautious buying could limit price increases. Market direction will depend on production resumption in Meghalaya, raw material availability and the status of BIS licences in Bhutan.
Leave a Reply