- Sponge iron prices decrease by INR 200/t d-o-d
- Falling finished steel prices keep buyers cautious
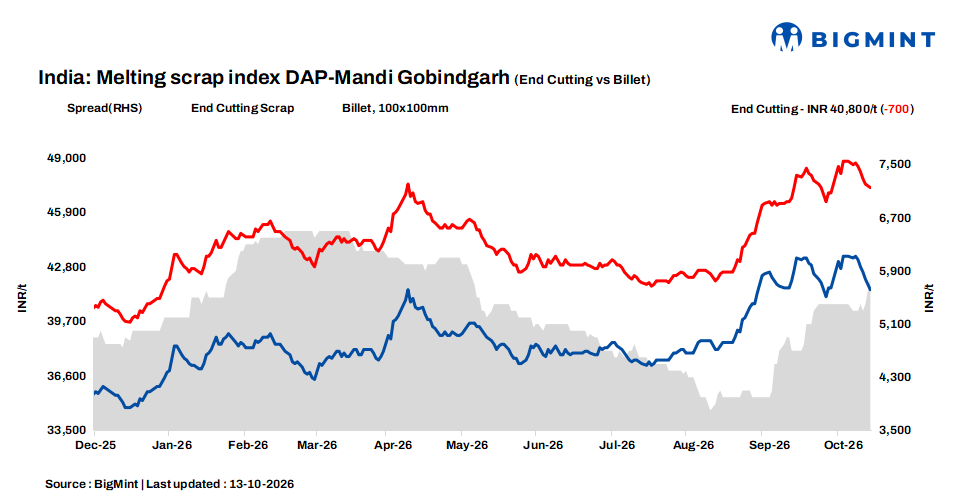
BigMint’s domestic end-cutting scrap index, tracking the Mandi Gobindgarh market, moved down by INR 700/t d-o-d to INR 40,800/t DAP on 13 October 2026. Mandi Gobindgarh continued to witness a soft and cautious market trend, with overall sentiment remaining weak. Major buyers stayed largely absent from active procurement, while mills adopted a highly selective approach, limiting scrap purchases to cover immediate, need-based requirements.
Scrap demand remained subdued due to elevated arrivals from neighbouring states, which kept local suppliers under pressure to clear material. At the same time, sluggish finished steel offtake further weighed on market sentiment, as rolling mills and re-rollers remained uncertain about downstream consumption and price sustainability.
With buyers anticipating further softening in finished steel prices, procurement activity was restricted and negotiation margins widened. The combination of ample scrap availability, weak demand, and cautious buyer sentiment continued to limit any meaningful price support, keeping the Mandi secondary steel market range-bound with a negative bias.
Raw material
Sponge iron prices in Mandi declined by INR 200/t d-o-d to INR 33,800/t DAP, reflecting weak procurement sentiment among local mills. Meanwhile, steel-grade pig iron prices in Ludhiana remained stable d-o-d at INR 44,000/t DAP.
Steel market
Steel ingot prices in Mandi fell sharply by INR 700/t d-o-d to INR 46,500/t DAP. Other markets also recorded declines of around INR 200-800/t in semi-finished steel prices, underscoring a cautious and sluggish market sentiment amid weak demand and limited buyer participation.
Rebar (Fe500) prices in the region dropped by INR 500/t d-o-d to INR 52,200/t ex-works, while HR strip (patra) prices witnessed a significant decline of INR 1,000/t to INR 50,500/t ex-works. The broad-based fall across semi-finished and finished products indicates continued pressure on downstream demand and a cautious buying approach across the secondary steel value chain.
Upcoming scrap auctions

Price highlights
End-cutting to billet spread: In Mandi, the spread between end-cutting scrap and billets stood in the range of INR 5,500-6,000/t.
Domestic vs imported scrap: Imported melting scrap prices at Nhava Sheva Port were assessed at $371-$373/t, approximately INR 37,730/t (inclusive of freight). HMS (80:20) prices in Mumbai dipped by INR 200/t to INR 36,700/t DAP. Indicative prices of shredded from Europe stood at $415/t CFR Nhava Sheva. A giant steel maker booked around 2,200 t HMS(90:10) scrap at INR 37,750 DAP Mumbai.
Raipur sponge iron-billet spread: The conversion spread (margin) between pellet-based DRI (P-DRI) and steel billets in Raipur stood at INR 15,950/t.

To see BigMint’s melting scrap assessment, pricing methodology and specification documents, click here
To provide feedback on this index or if you would like to contribute by becoming a data partner, please contact – support@bigmint.co
Leave a Reply