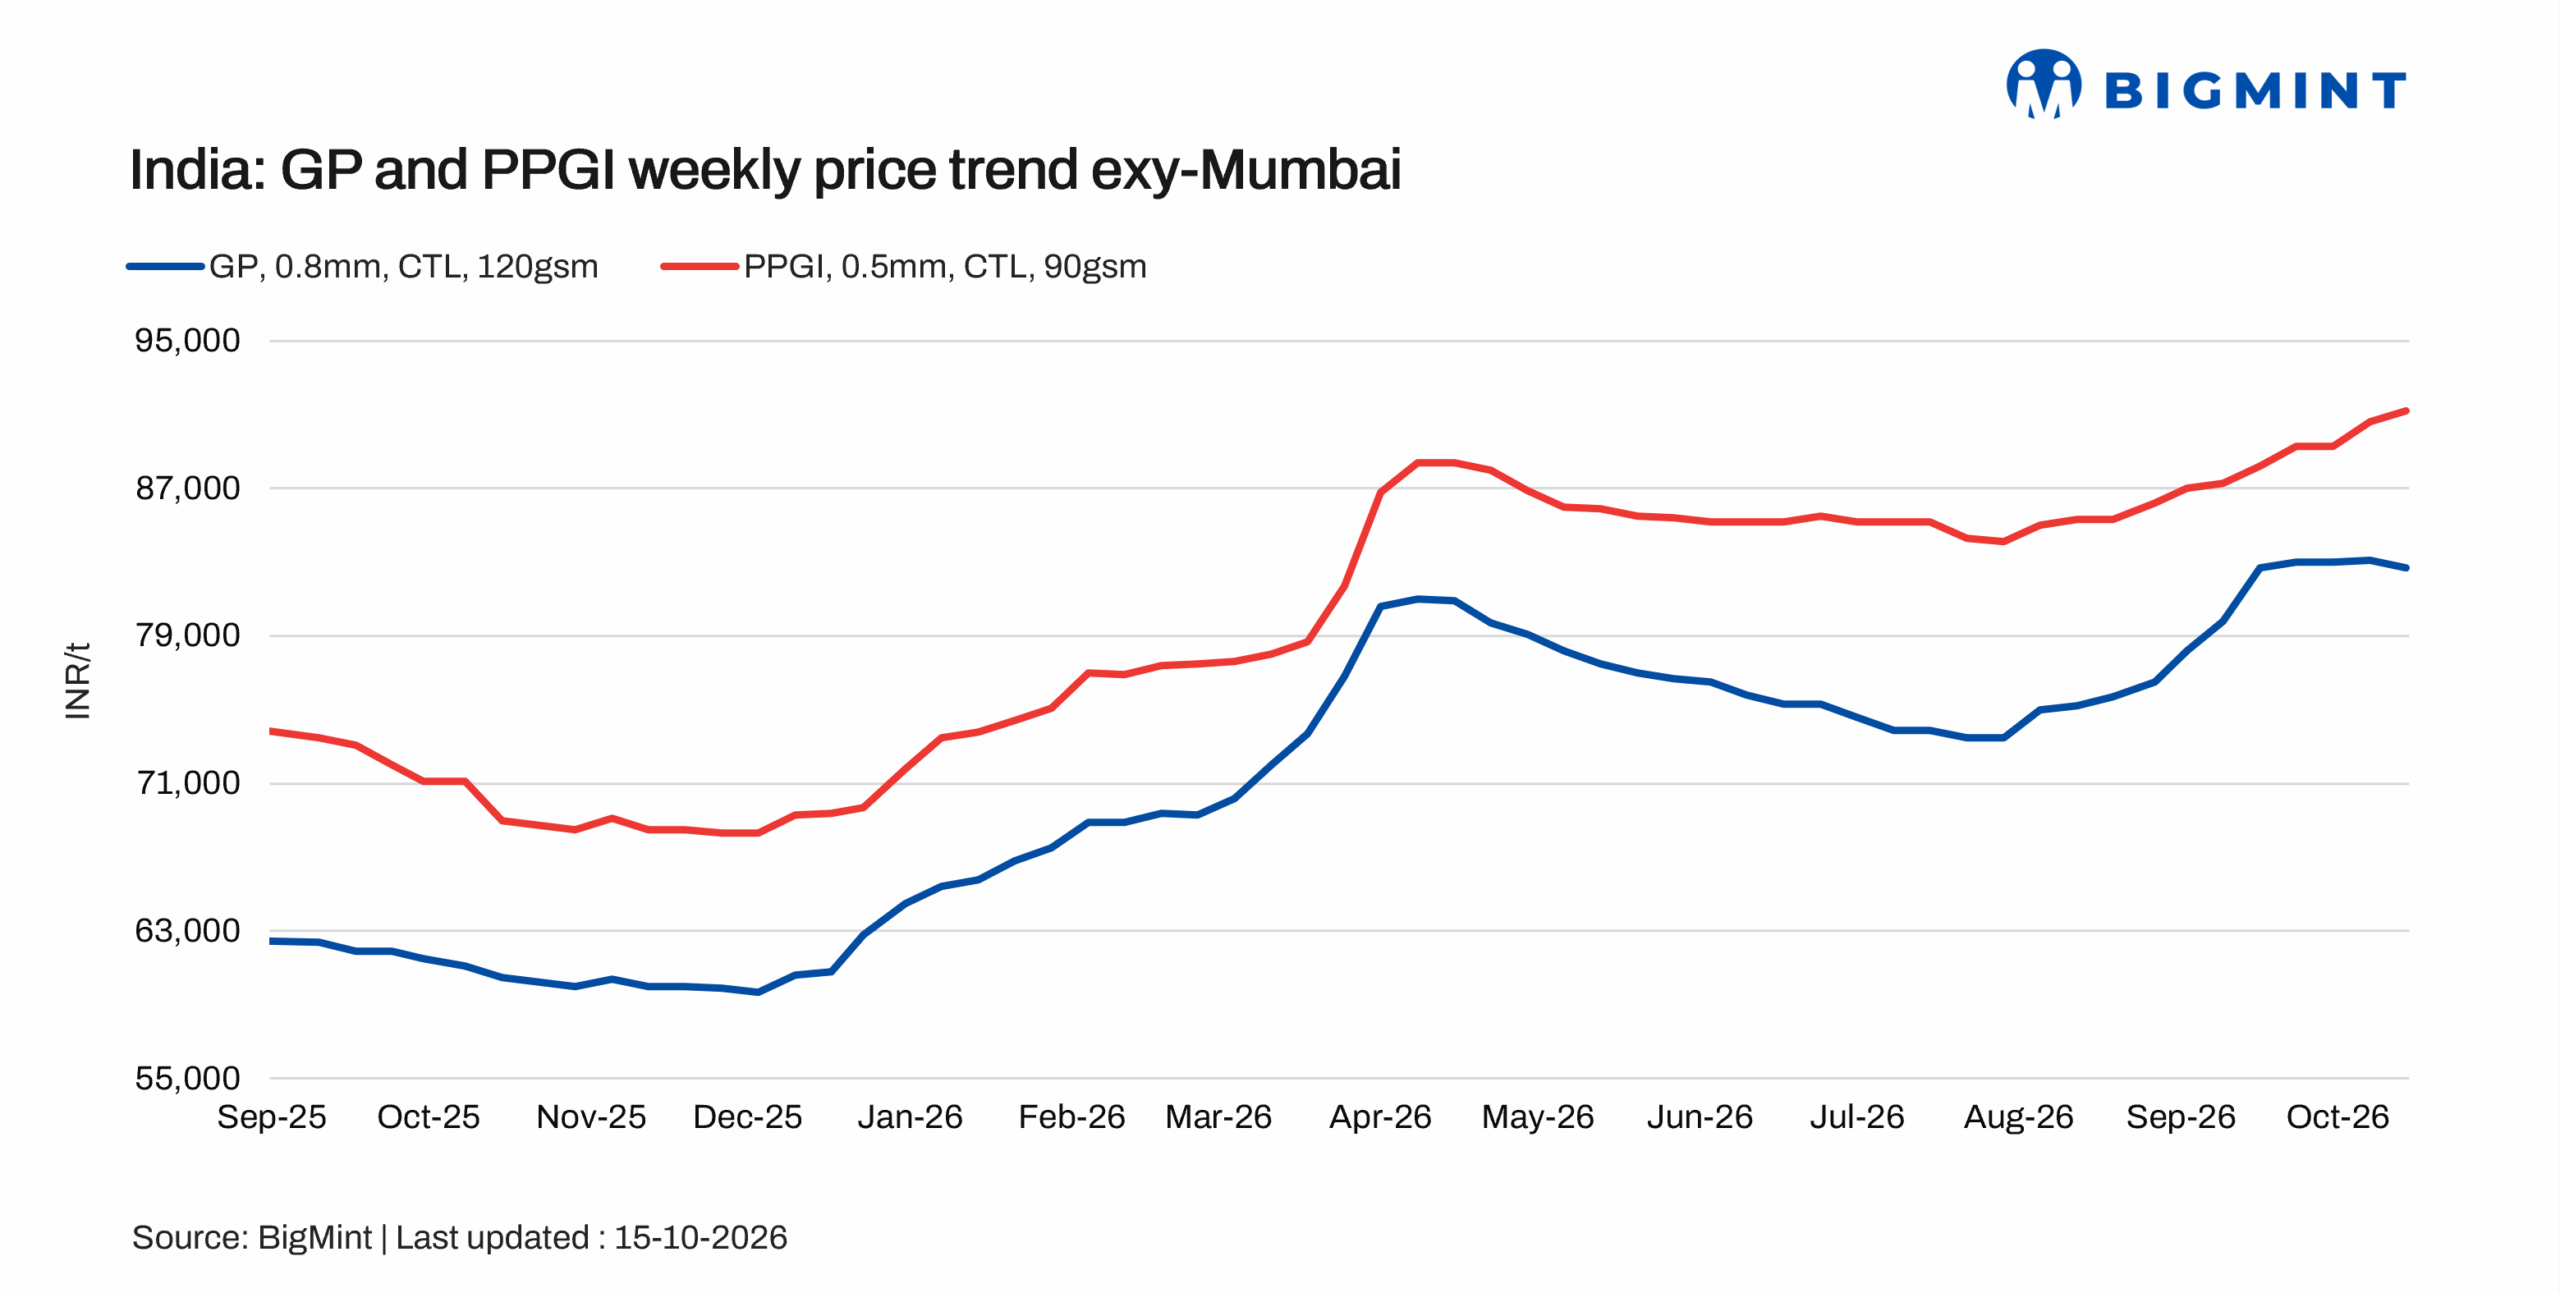
- GP prices soften as sellers focus on liquidating stocks before festive season
- Tighter availability supports PPGI prices, with inventories at 15-20 days
India’s trade-level coated flat steel prices showed divergent movements w-o-w as per BigMint’s assessment on 15 October 2026, with the festive slowdown weighing on galvanised plain (GP) coil prices, which declined by INR 200-400/t across major markets. However, pre-painted galvanised iron (PPGI) and bare galvalume (BGL) prices increased w-o-w.
The slowdown in buying activity during the festive season prompted sellers to liquidate existing inventories to manage cash flows. Buyers continued to adopt a cautious approach, restricting purchases largely to immediate requirements.

Price updates
BigMint’s benchmark assessment for galvanised plain (GP) coil (0.8 mm/CTL, 120 GSM, IS 277) prices declined by INR 400/t w-o-w to INR 82,700/t ex-Mumbai as of 15 October 2026, from INR 83,100/t on 8 October 2026.
Pre-painted galvanised iron (PPGI) (0.5 mm/CTL, 90 GSM, IS 14246) was assessed at INR 91,200/t ex-Mumbai as of 15 October 2026, increasing by INR 600/t w-o-w from INR 90,600/t on 8 October 2026.
Meanwhile, bare galvalume (BGL) (0.5 mm/CTL, 1220 mm, AZ150) was assessed at INR 93,900/t ex-Mumbai as of 15 October 2026, up by INR 200/t w-o-w from INR 93,700/t on 8 October 2026.
Raw material prices

India’s zinc ingot (99.995%) prices decreased by INR 1,000/t w-o-w to INR 436,000/t ex-Delhi as of 14 October 2026, down from INR 437,000/t on 7 October 2026.
Meanwhile, BigMint’s bi-weekly benchmark assessment for hot-rolled coil (HRC) (2.5-8 mm/CTL, IS 2062, Grade E250 BR) decreased by INR 700/t w-o-w to INR 64,000/t ex-Mumbai as of 13 October 2026, from INR 64,700/t in the previous assessment on 6 October 2026.
Cold-rolled coil (CRC) (0.90 mm/CTL, IS 513, CR1) prices also declined by INR 1,000/t w-o-w to INR 73,800/t ex-Mumbai as of 13 October 2026, down from INR 74,800/t in the previous assessment on 6 October 2026.
Market updates
India’s coated flat steel market witnessed varied price trends across products, with demand remaining weak in the GP segment, while PPGI prices continued to rise, primarily due to increased competition among market participants and relatively limited material availability.
On the supply side, GP inventory levels are estimated to cover around 20-25 days of demand, while PPGI inventory is lower at around 15-20 days. The relatively tighter availability of PPGI material has provided some support to prices, although market conditions continue to vary across regions.
Demand for GP was subdued, with buyers largely restricting purchases to immediate requirements. In the PPGI segment, price movements were driven more by competitive market conditions and limited availability than by a significant improvement in underlying demand. Regional market sentiment remained broadly unchanged, with buying activity continuing to reflect cautious procurement patterns.
Outlook
GP prices may remain under pressure in the near term as festive-season demand remains weak and sellers continue to prioritise inventory liquidation. In contrast, PPGI prices may retain an upward bias due to relatively tighter availability and competitive market dynamics. However, the decline in HRC and CRC benchmark prices, along with lower zinc ingot prices, could moderate cost-side support for coated products. Further price movements will largely depend on mill offers, post-festive buying activity and the pace of inventory absorption across markets.
Leave a Reply