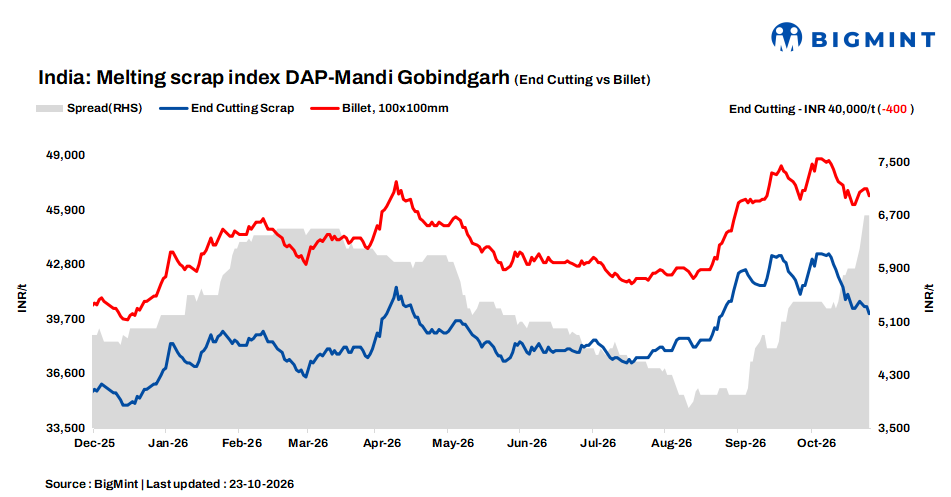
- Cautious mill procurement and adequate scrap availability weigh on prices
- Finished steel markets remain mixed amid subdued buying activity
BigMint’s domestic end-cutting scrap index, tracking the Mandi Gobindgarh market, declined by INR 400/tonne (t) d-o-d to INR 40,000/t DAP on 23 October 2026.Prices across other scrap categories slipped INR 100-200/t w-o-w, weighed down by restricted procurement activity.
Mandi Gobindgarh’s scrap market witnessed a downtrend during the week, with prices declining by INR 100-400/t amid sustained pressure on suppliers. A steady inflow of scrap, coupled with restrained buying by major mills, kept the market under pressure. The weakness was further compounded by sluggish demand in the finished steel segment, which continued to strain liquidity across the region’s secondary steel ecosystem.
Participants in Mandi remained cautious, with mills preferring limited and need-based procurement amid uncertain finished steel offtake. Suppliers, facing adequate material availability and slower conversions, were more flexible on pricing to clear inventories. Overall, the market sentiment stayed weak-to-neutral, with buyers holding a wait-and-watch approach and expecting prices to remain range-bound unless finished steel demand improves.
Alternative raw material prices
Sponge iron (CDRI) prices in Mandi Gobindgarh eased by INR 100/t d-o-d to INR 34,000/t DAP. However, on a weekly basis, prices rose by INR 150/t amid slow buying activity in the market.
Steel-grade pig iron prices in Ludhiana softened by INR 300/t d-o-d to INR 43,200/t DAP. Prices also decreased by INR 325/t w-o-w, weighed down by limited demand from downstream buyers.

Steel market
Ingot prices in Mandi Gobindgarh fell by INR 300/t d-o-d to INR 46,700/t DAP. Other key production hubs also recorded declines of INR 200-800/t during the day’s trading session. On a weekly basis, ingot prices in the region increased by INR 280/t, although demand remained slow to moderate.
Rebar (Fe500) prices held steady d-o-d at INR 52,300/t ex-works, with no change observed on a weekly basis as well. Meanwhile, hot-rolled (HR) strip prices declined by INR 500/t d-o-d to INR 50,500/t ex-works, and were down INR 120/t w-o-w amid muted market activity.
Upcoming scrap auctions

Price highlights
End-cutting to billet spread: In Mandi, the spread between end-cutting scrap and billets stood in the range of INR 6,500-6,800/t.
Domestic vs imported scrap: Imported melting scrap prices at Nhava Sheva Port were assessed at $360-$365/t, approximately INR 36,750/t (inclusive of freight). Mumbai HMS (80:20) prices eased by INR 100/t day-on-day to INR 36,000/t DAP, as buyers adopted a cautious stance amid limited procurement activity. The subdued sentiment spilled over into the semi-finished steel segment, with prices declining INR 400/t d-o-d on a slow market trend, indicating persistent weakness in downstream demand and trading momentum. Indicative prices of shredded from Europe stood at $403-$405/t CFR Nhava Sheva.
Raipur sponge iron-billet spread: The conversion spread (margin) between pellet-based DRI (P-DRI) and steel billets in Raipur stood at INR 16,750/t. Scrap and pig iron prices in Raipur held steady d-o-d amid need-based procurement activity.

To see BigMint’s melting scrap assessment, pricing methodology and specification documents, click here
To provide feedback on this index or if you would like to contribute by becoming a data partner, please contact – support@bigmint.co
Leave a Reply