- Scrap prices rise amid moderate buying interest
- Semis and finished steel prices gain INR 1,000-1,300/t
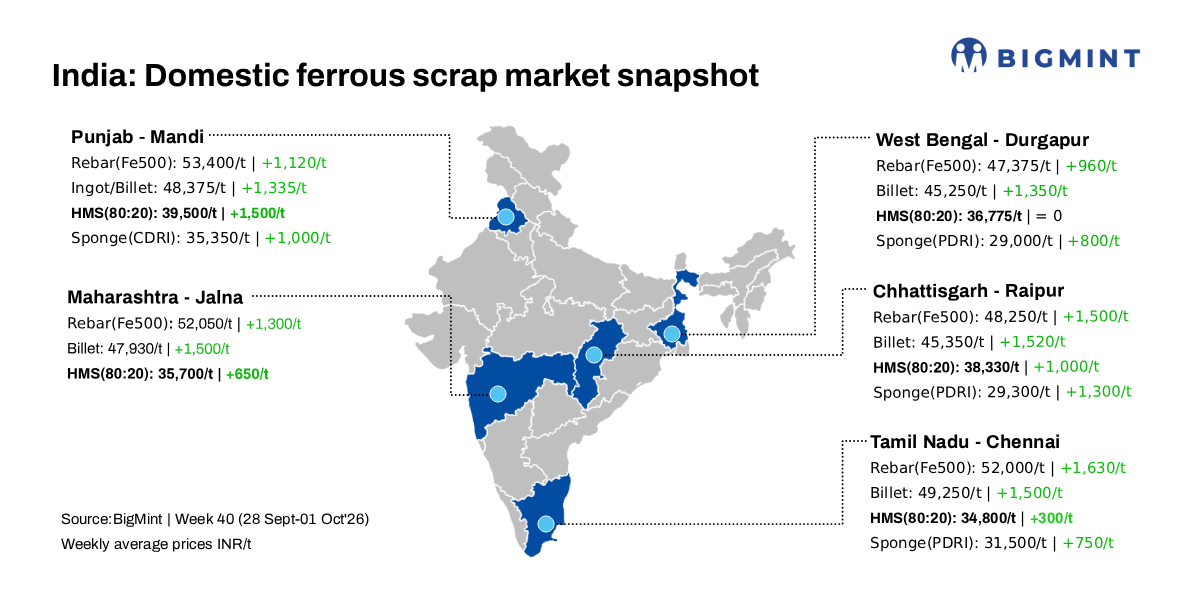
BigMint’s domestic end-cutting scrap index, tracking the Mandi Gobindgarh market, increased by INR 700/tonne (t) day-on-day to INR 43,400/t DAP on 1 October 2026. The scrap index increased by INR 1,300/t week-on-week, while other scrap grades witnessed a sharp rise of INR 1,300-1,500/t over the same period. The increase followed a recovery in the secondary steel market, where scrap, semi-finished and finished steel prices rose by INR 500-700/t across key products.
The price recovery was supported by moderate buying interest and a brief pickup in spot enquiries. However, cautious procurement and uncertainty over the sustainability of the gains continued to limit market activity.
A mill owner told BigMint, “The move indicates price discovery at higher levels, but sustainability will depend on whether spot enquiries convert into follow-on business over the next few sessions.”

Alternative raw materials
Sponge iron (CDRI) prices in Mandi Gobindgarh increased by INR 600/t d-o-d to INR 35,700/t DAP, despite moderate demand. Good scrap availability encouraged mill owners to procure scrap, particularly amid pressure on conversion margins.On a weekly basis, sponge iron prices increased by INR 980/t in the region.
Meanwhile, steel-grade pig iron prices in Ludhiana remained stable at INR 44,500/t DAP, indicating steady market conditions. Pig iron prices rose by INR 700/t week-on-week.
Steel market
In Mandi Gobindgarh, ingot prices rose by INR 600/t d-o-d to INR 48,800/t DAP, supported by positive market sentiment and a brief increase in spot enquiries from re-rollers and small finished steel manufacturers. However, overall buying activity remained moderate. Semi-finished steel prices in Mandi jumped by INR 1,330/t on a weekly basis.
Rebar prices increased by INR 500/t d-o-d to INR 53,700/t ex-works, while HR strip (patra) prices advanced by the same level to INR 53,800/t ex-works.
In Mandi, rebar prices rose by INR 1,120/t week-on-week, while patra prices climbed by INR 2,150/t over the same period
A mill owner informed BigMint: “Patra demand in Mandi is comparatively stronger than in the rebar segment, as several mills have cut production in response to sluggish end-user demand.
Price highlights
End-cutting to billet spread: In Mandi, the spread between end-cutting scrap and billets stood in the range of INR 5,200-5,600/t.
Domestic vs imported scrap: Imported melting scrap prices at Nhava Sheva Port were assessed at $370-$375/t, approximately INR 38,200/t (inclusive of freight). HMS (80:20) prices in Mumbai moved up by INR 300/t to INR 37,000/t DAP. Indicative prices of shredded from Europe stood at $414-$416/t CFR Nhava Sheva.
Raipur sponge iron-billet spread: The conversion spread (margin) between pellet-based DRI (P-DRI) and steel billets in Raipur stood at INR 16,200/t.

To see BigMint’s melting scrap assessment, pricing methodology and specification documents, click here
To provide feedback on this index or if you would like to contribute by becoming a data partner, please contact – support@bigmint.co
Leave a Reply