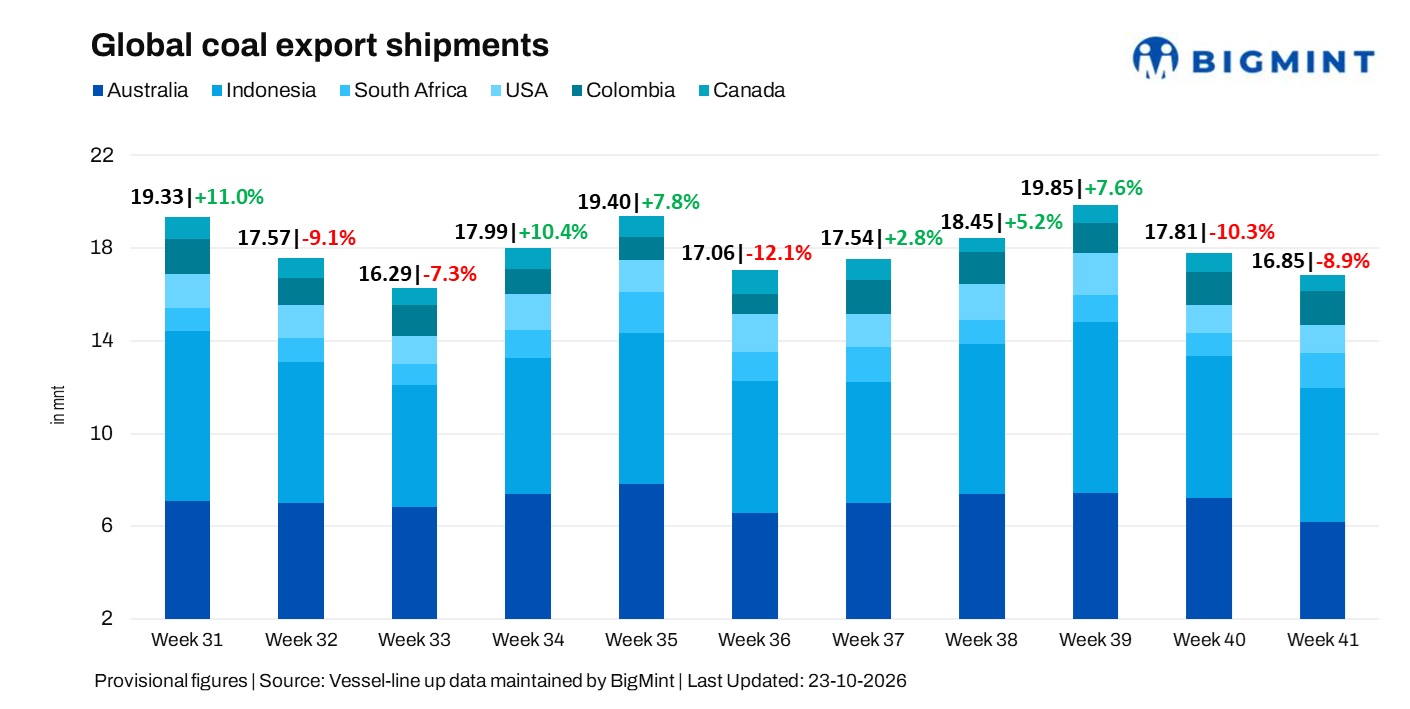
- US shipments gain, while Australian, Indonesian and South African flows subdued
- Pacific coal exports weaken as major suppliers record softer shipments
Global seaborne coal exports across six major suppliers fell 8.9% w-o-w to 16.85 million tonnes (mnt) in week 42 (10-16 October 2026), as softer shipments from Australia, Indonesia and Colombia weighed on overall volumes. South African exports also eased, while the US recorded stronger shipments, providing only limited support to the broader market.
Australia remained the largest exporter at 6.19 mnt, followed by Indonesia at 5.76 mnt. However, weaker flows from both Pacific suppliers, alongside softer Colombian shipments, overshadowed the US performance. The contrasting trends reflected uneven demand across key markets, supply-side constraints and differences in loading activity.
Country-wise exports

Port-wise exports
Australia, Indonesia dominate Pacific coal flows
- Australia exported 6.19 mnt, led by Newcastle at 2.83 mnt, Gladstone at 1.39 mnt and DBCT at 1.08 mnt. Japan (1.74 mnt) and China (1.23 mnt) were the leading reported destinations, while Yancoal (0.50 mnt) and Glencore (0.43 mnt) led shipper activity.
- Indonesia exported 5.76 mnt, with Bunati (0.88 mnt), Taboneo (0.75 mnt) and Palembang (0.69 mnt) as key ports. India (1.66 mnt) and China (1.07 mnt) were the leading destinations, while Borneo Indobara (0.72 mnt) and Jhonlin Group (0.43 mnt) led shipper activity.
- Canada exported 0.71 mnt, led by Roberts Bank at 0.39 mnt and Vancouver at 0.24 mnt. Japan was the leading reported destination at 0.56 mnt, while Elk Valley Resources accounted for 0.24 mnt.
Colombia, South Africa, US shape Atlantic coal flows
- Colombia exported 1.47 mnt, with Puerto Bolivar accounting for 0.58 mnt and Puerto Nuevo 0.40 mnt. Turkey (0.51 mnt) and Spain (0.17 mnt) were the leading reported destinations, while Cerrejon Mines (0.58 mnt) and Prodeco Group (0.51 mnt) led shipper activity.
- South Africa exported 1.53 mnt entirely through Richards Bay, with India accounting for 0.82 mnt of reported shipments. Rail performance and terminal operations remained critical to export flows.
- US exports stood at 1.20 mnt, with Norfolk contributing 0.53 mnt and Baltimore 0.41 mnt. India was the leading reported destination at 0.50 mnt.
India-bound coal freights diverge
India-bound coal freight sentiment remained mixed across key routes. Australian coal exports softened, but demand for Australian cargoes continued to provide some support to Panamax freight rates. Meanwhile, Indonesian routes faced pressure amid weaker market sentiment and subdued fixing activity.
The divergence highlights how freight rates can move differently from export volumes, depending on vessel availability, cargo enquiries and shipowners’ rate expectations. While Australian-linked Panamax routes found some support, Indonesian Supramax routes remained more vulnerable to limited fresh demand.
Outlook
Global coal exports may remain under pressure if buying interest across key Asian and Atlantic markets stays subdued. Australian and Indonesian loading activity, Chinese coal demand and India’s import requirements will be important indicators for Pacific flows, while Richards Bay logistics and Colombian shipment activity will shape the outlook for Atlantic suppliers.
In freight, Australian Panamax routes may find some support from cargo demand, while Indonesian Supramax routes could remain under pressure amid limited enquiries. Vessel availability, bunker costs and fixing activity will shape the near-term outlook.
Leave a Reply