- Pacific rates ease despite stronger demand, typhoon-related vessel constraints
- Atlantic freights weaken despite healthy cargo demand, fresh fixtures
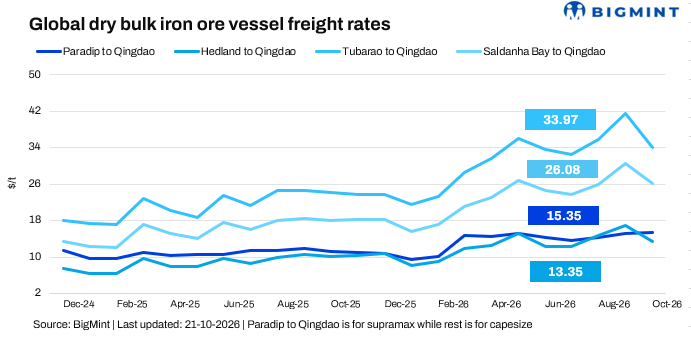
China-bound iron ore freights across all four key routes tracked by BigMint declined in the week ending 20 October 2026 amid lower bids. Pacific rates softened despite improving iron ore demand and expectations of tighter prompt tonnage amid Typhoon Champi, while Atlantic rates declined despite healthy tonnage demand and fresh fixtures from Brazil and South Africa.
The Pacific market remained under pressure as freight bids stayed below owners’ offers, despite rising iron ore enquiries and expectations of weather-related vessel delays. In the Atlantic, rates on the Brazil-China and South Africa-China routes declined amid ample vessel availability, even as fresh cargo enquiries and fixtures supported activity. The Paradip-China Supramax route also fell, hitting a one-month low, reflecting subdued market momentum.
Route-wise sentiment

Dry bulk freight sentiment remained weak, even as Capesize spot markets witnessed improved Pacific activity and weather-related tonnage concerns. Forward freight curves softened across vessel segments, signalling cautious market expectations despite the Capesize spot recovery. Meanwhile, volatile oil prices and ongoing geopolitical tensions in the Middle East added uncertainty to the broader shipping outlook.
Outlook
Dry bulk iron ore freight rates may remain under pressure as weaker bids and available tonnage continue to weigh on market sentiment. Pacific rates could find support from weather-related vessel delays and sustained Australian iron ore demand, while the Atlantic market will depend on fresh Brazilian and South African cargo enquiries to absorb available tonnage.
Leave a Reply