- China holiday slowdown adds pressure to Pacific Capesize rates
- Expanding tonnage and thin Brazil enquiry pressure Atlantic rates
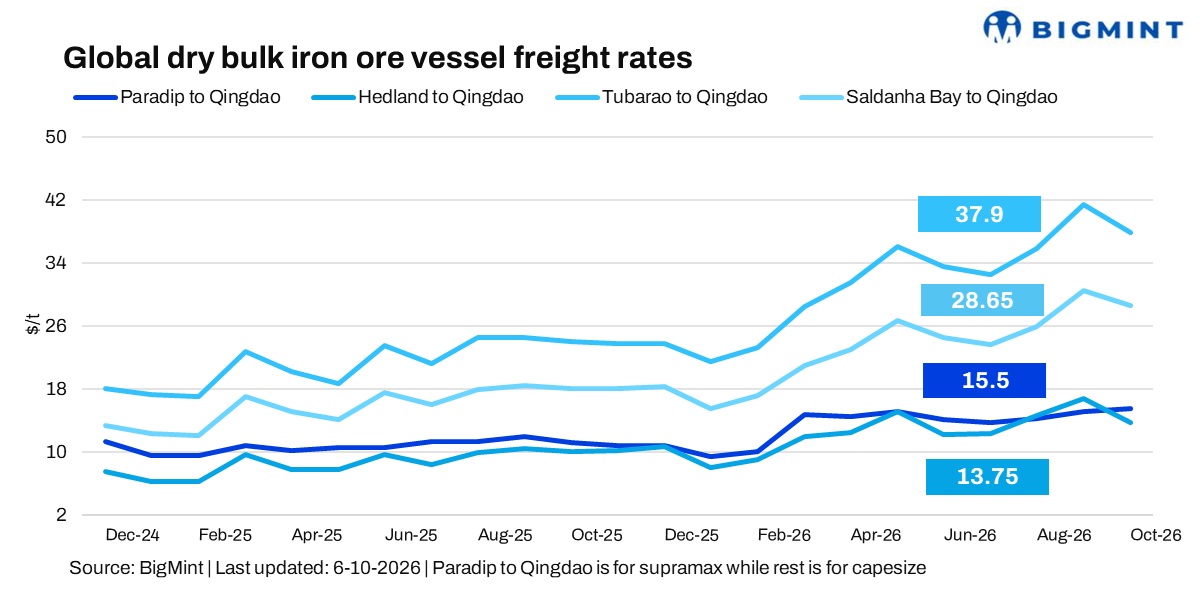
Dry bulk iron ore freight markets came under renewed pressure in the week ended 6 October 2026, with Capesize rates weakening across both Pacific and Atlantic routes. The Pacific saw sharper pressure as vessel availability remained comfortable and Australia-China fixing slowed ahead of China’s National Day holiday. In the Atlantic, limited Brazil cargo flow and a growing tonnage list kept owners on the defensive.
The Supramax market was more resilient, with steady cargo demand and tighter prompt availability helping sentiment hold firmer despite limited fresh business.
“No cargoes today for Paradip-China,” a shipbroker said, pointing to the subdued start on the India-China corridor.
Route-wise sentiment

The Pacific remained the weakest spot in the Capesize market, as a growing pool of available vessels competed for a thinner cargo book. Softer iron ore demand and elevated inventories ahead of the Chinese holiday added to the pressure, while owners continued to test the market for better levels.
“The Pacific is seeing a clear imbalance between tonnage and demand, with softer iron ore buying adding further pressure to freight,” a market source said.
Atlantic sentiment also turned softer, with limited Brazil cargo flow and expanding tonnage lists weighing on Brazil-China business. Some owners continued to hold their offers, while others looked towards the North Atlantic for November cargoes in search of better returns.
South Africa-China activity faced pressure as Chinese buying remained subdued and weather-related disruptions eased, allowing operations to normalise and removing some earlier support to freight.
Despite the weakness in spot markets, FFA levels showed some improvement, offering a more constructive signal for the forward market. However, a sustained recovery will depend on fresh cargo stems and a pickup in Chinese buying after the holiday.
Outlook
The market is likely to remain under pressure in the near term, with Pacific Capesize rates particularly vulnerable to comfortable tonnage and subdued cargo flow. Atlantic sentiment may remain soft while Brazil enquiry stays limited. Post-holiday Chinese buying, fresh Australia/Brazil stems and improving FFA sentiment will be key to determining whether the market can regain momentum.
Leave a Reply