- Imported PE prices decline as domestic demand remains selective
- Crude retreats amid potential easing of Russian tanker sanctions
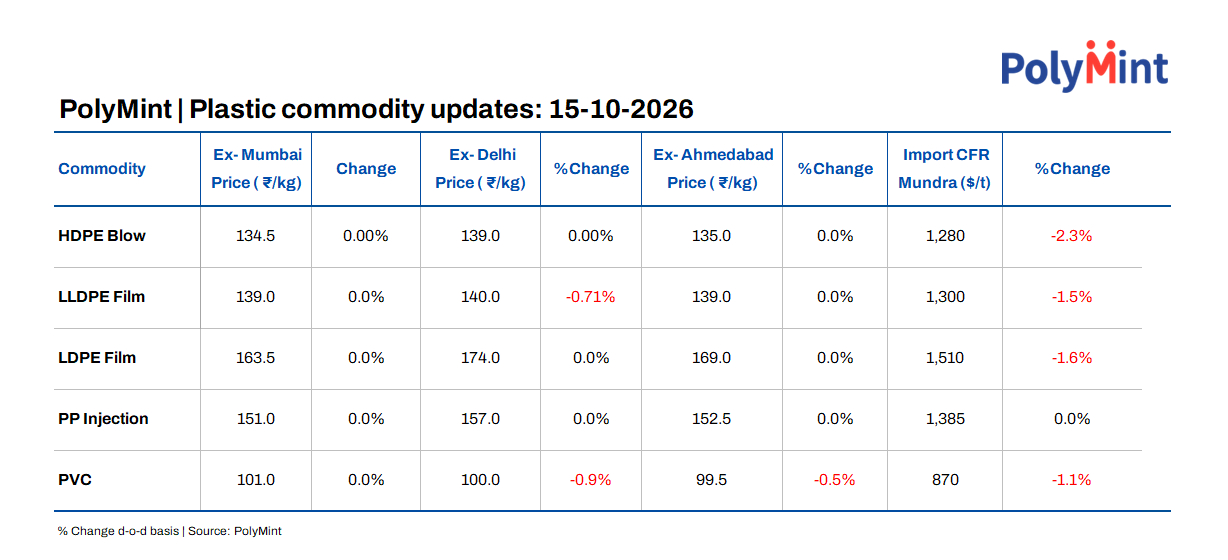
India’s polymer market showed mixed trends d-o-d on 15 October, with Linear Low-Density Polyethylene (LLDPE) film declining by INR 1/kg in Delhi. Import prices for High-Density Polyethylene (HDPE) blow moulding, LLDPE film, and Low-Density Polyethylene (LDPE) film fell by 1.5-2.3% at CFR Mundra, while Polyvinyl Chloride (PVC) imports eased 1.1%.
At CFR Mundra, HDPE blow moulding fell 2.3% to $1,280/t, LLDPE film declined 1.5% to $1,300/t, and LDPE film eased 1.6% to $1,510/t. PP injection remained at $1,385/t, while PVC declined 1.1% to $870/t.
Brent crude fell 1.83% to $104.12/barrel, and West Texas Intermediate (WTI) declined 0.25% to $94.92/barrel. Naphtha slipped 0.94% to $996/t, while natural gas rose 2.02% to $3.26/MMBtu. The rupee weakened 0.10% against the US dollar to INR 95.24.
Domestic market overview
Domestic polymer prices remained largely stable across Mumbai, Delhi, and Ahmedabad. HDPE blow moulding stood at INR 134.50/kg in Mumbai, INR 139/kg in Delhi, and INR 135/kg in Ahmedabad. LLDPE film was assessed at INR 139/kg in Mumbai and Ahmedabad and INR 140/kg in Delhi. LDPE film remained at INR 163.50/kg in Mumbai, INR 174/kg in Delhi and INR 169/kg in Ahmedabad.
PP injection prices held at INR 151/kg in Mumbai, INR 157/kg in Delhi and INR 152.50/kg in Ahmedabad. PVC stood at INR 101/kg in Mumbai, INR 100/kg in Delhi and INR 99.50/kg in Ahmedabad.
Acrylonitrile butadiene styrene (ABS) prices remained firm amid limited imports and tight domestic supply. Delhi polystyrene (PS) buying improved despite recent price increases, although purchases remained need-based. China’s price rally could lift South Asian offers, but Indian buyers’ resistance may limit domestic increases.

Other updates
Oil prices fall as US considers easing Russian tanker sanctions
Oil prices declined on 15 October as the US considered easing restrictions on some Russian tankers, potentially improving diesel supply flexibility and lowering freight costs. Brent fell 2.2% to $103.78/barrel and WTI declined 1.4% to $93.75/barrel during early trading. However, renewed shipping attacks and Ukrainian strikes on Russian energy infrastructure limited the decline.
LG Chem restarts Yeosu cracker after six-month shutdown
LG Chem restarted its No. 2 naphtha cracking centre at South Korea’s Yeosu complex on 12 October, restoring annual ethylene capacity of 800,000 t/year and propylene capacity of 400,000 t/year. The plant had been offline since March due to naphtha supply disruptions. The restart could ease short-term regional supply constraints, although high feedstock costs, weak demand and Asian petrochemical overcapacity may limit profitability.
Strait of Hormuz disruptions threaten import economics
Commodity vessel traffic through the Strait of Hormuz remained severely disrupted amid tanker attacks and stalled US-Iran negotiations. Five commodity vessels transited the strait on Saturday, while no transits were recorded on Sunday, compared with 31 during the previous weekend. Continued disruption could increase freight costs and uncertainty over feedstock availability for Indian polymer importers.
Leave a Reply