- Pre-holiday restocking winds down, keeping buying activity measured
- Tight steelmaking margins keep Chinese mills cautious on fresh purchases
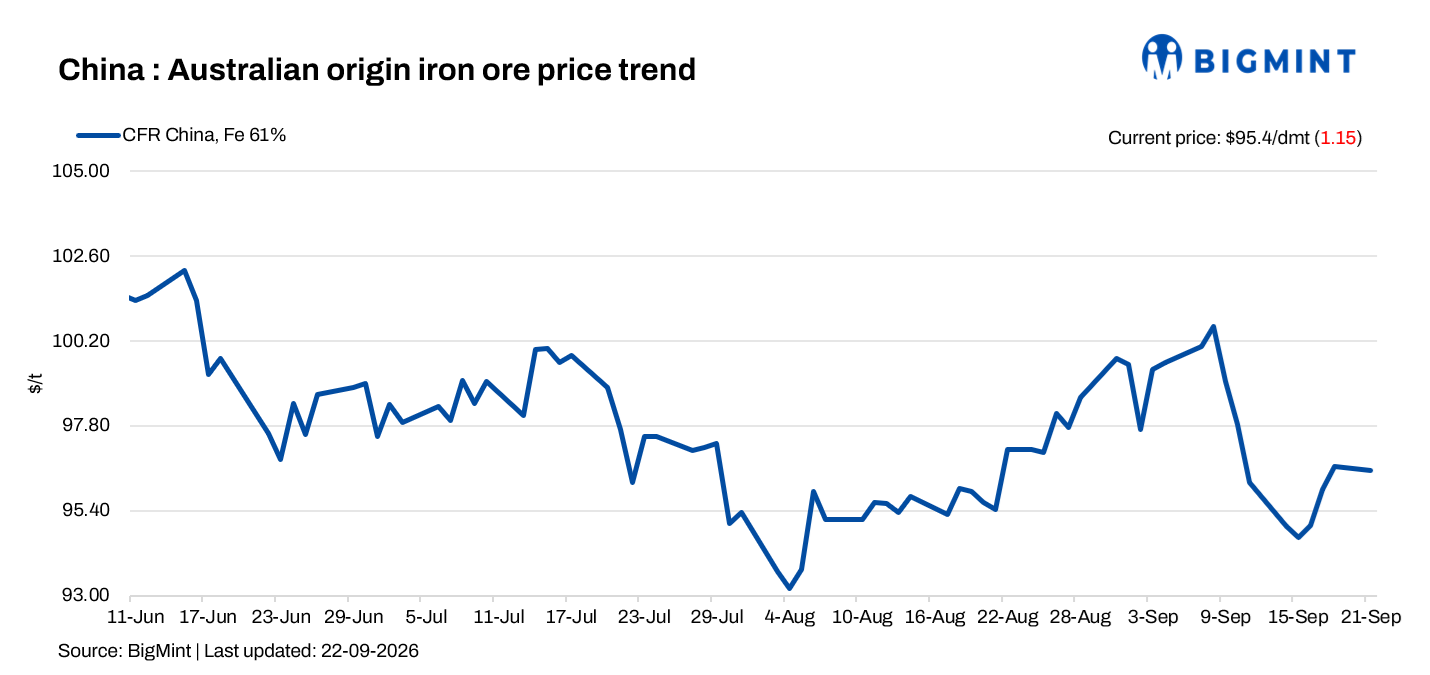
Iron ore fines (Fe 61%) spot prices fell by $2/dmt to a one-week low of $95/dmt CFR China on 22 September 2026 from 21 September, reaching the same level last seen on 17 September. Prices declined as Chinese steelmakers gradually completed pre-holiday procurement ahead of the Mid-Autumn Festival and National Day holidays (1-7 October). With a significant portion of holiday requirements already covered, fresh buying remained selective, although mills continued to procure against immediate needs.
The moderation in restocking was also reflected in China’s port market, where prices eased after four consecutive days of gains. Market activity remained steady but lacked the urgency seen during the earlier restocking phase. Demand for high-grade ore was relatively measured, as higher raw material costs continued to keep mills cautious amid tight steelmaking margins.
Overall, buyers maintained a wait-and-watch approach while covering essential requirements. Narrower import margins and subdued steelmaking profitability limited aggressive procurement, but the market did not see a sharp deterioration in demand. With holiday restocking largely nearing completion, price movements are likely to take cues from post-holiday mill buying and changes in steelmaking margins.
DCE iron ore futures remain range-bound
January 2027 iron ore futures on the Dalian Commodity Exchange (DCE) remained largely stable at RMB 715.5/t ($106.7/t) on 22 September, compared to RMB 716/t ($106.9/t) on 21 September. This had limited impact on the market, with trading expected to slow as market fundamentals are still bearish.
Leave a Reply