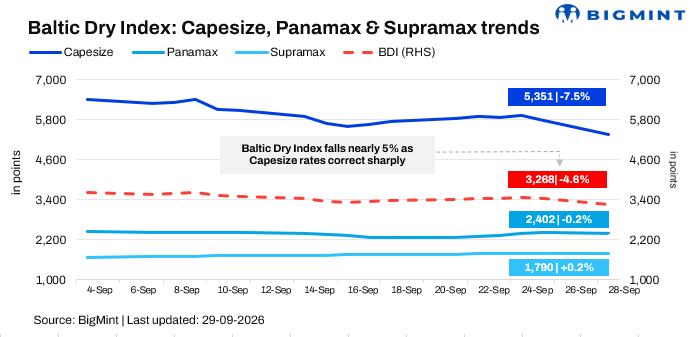
- Capesize index drops sharply by nearly 7.5%, driving decline
- Panamax slips marginally, while Supramax edges higher
The Baltic Dry Index (BDI) fell sharply by 158 points, or 4.61%, to 3,268 on 28 September, from 3,426 on 25 September. The decline was led by a sharp correction in the Capesize segment, while Panamax also edged lower. Supramax posted a marginal gain, providing limited support to the overall index.
Baltic Dry Index slipped amid Capesize rates weighing heavily on the broader market. The decline in the larger-vessel segment came amid softer iron ore prices and ample global supply, while weaker wheat prices also contributed to pressure on Panamax rates. The smaller-vessel segment remained comparatively resilient, supported by relatively steady cargo activity.
Segment-wise performance
- Capesize declines sharply: The Baltic Capesize Index (BCI) fell 433 points, or 7.49%, to 5,351 on 28 September, from 5,784 on 25 September. The sharp correction reflected weaker sentiment in the Capesize market, with lower iron ore prices amid ample global supply weighing on cargo and freight activity.
- Panamax edges lower: The Baltic Panamax Index (BPI) declined 5 points, or 0.21%, to 2,402, from 2,407 on 25 September. The marginal decline was partly linked to softer wheat prices, although steady coal and grain demand provided some underlying support.
- Supramax edges higher: The Baltic Supramax Index (BSI) increased 4 points, or 0.22%, to 1,790, from 1,786 on 25 September. The marginal gain indicated relatively firmer conditions in the smaller-vessel segment compared with the larger tonnage markets.
Outlook
The BDI could remain under pressure in the near term following the sharp Capesize correction. Capesize performance is likely to remain the key driver, with iron ore prices, cargo availability and fixing activity closely watched. Panamax and Supramax markets may offer some stability if coal, grain and minor-bulk demand remains steady, but continued weakness in Capesize could weigh on the broader index.
Leave a Reply