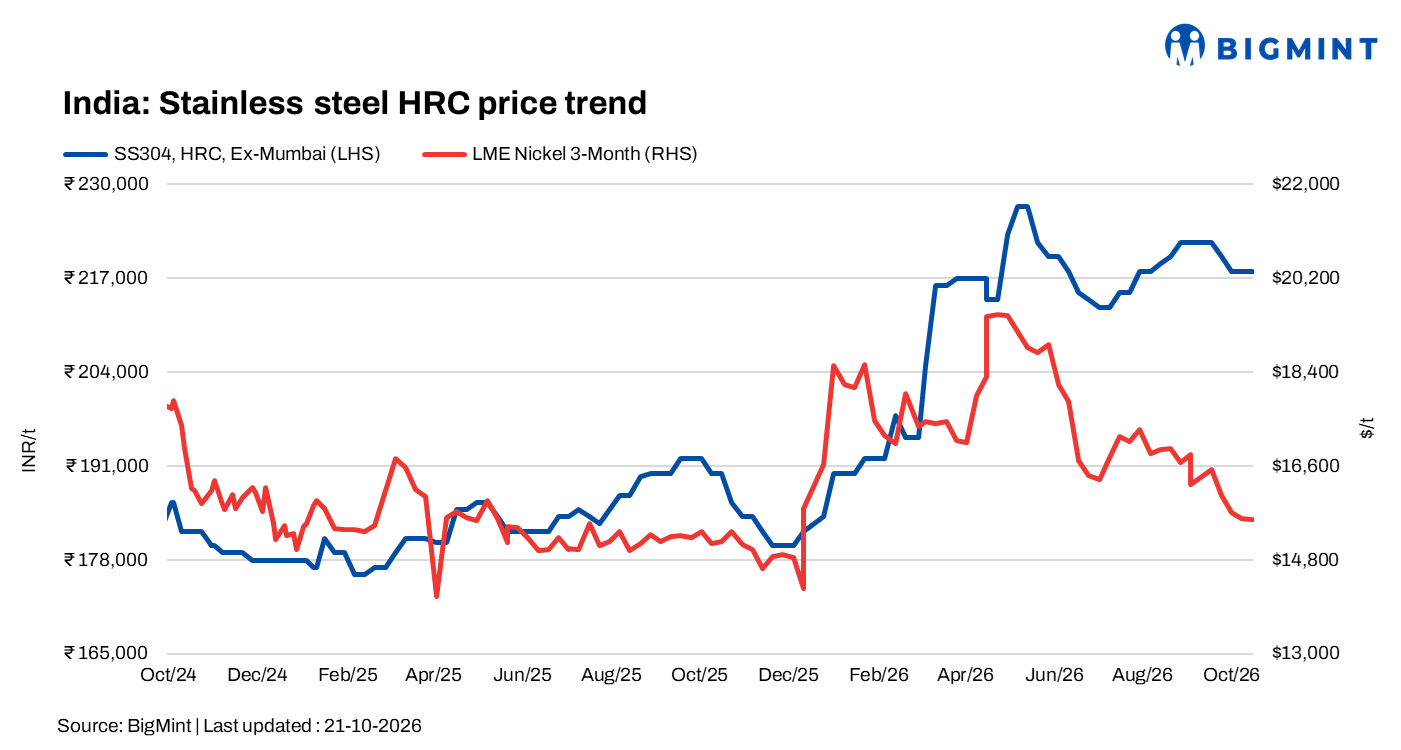
- Flats prices remain largely stable; 316-grade HR coil, black bar prices decline
- Pre-Diwali purchases support flats trade, longs demand remains subdued
India’s stainless steel market remained subdued in the week ended 21 October 2026, as festive-season disruptions, liquidity constraints and cautious procurement limited trading activity. While pre-Diwali requirements provided some support to flat-product demand, buying remained largely need-based. Long products continued to face weaker demand amid limited export opportunities and subdued downstream consumption.
Prices showed a mixed trend, with 304-grade products holding steady, while 316-grade hot-rolled (HR) coil and black bar prices declined by INR 5,000/t each. Meanwhile, softer stainless steel scrap prices ahead of Diwali reflected cautious raw material procurement and limited buying interest.
Finished flats
India’s stainless steel flat-products market recorded relatively steady, need-based demand ahead of Diwali. However, overall trading remained limited as buyers prioritised immediate requirements and avoided building inventories amid liquidity constraints.
BigMint’s weekly assessment of 304-grade HR coil prices remained unchanged week on week (w-o-w) at INR 218,000/t ex-works Mumbai. In contrast, 316-grade HR coil prices declined by INR 5,000/t to INR 445,000/t.
Import offers from Southeast Asia were heard at $1,970-1,980/t for 304 HR coil and $2,100-2,120/t for 304 cold-rolled (CR) coil. Competitive import offers continued to influence domestic purchasing decisions, limiting the scope for a significant price recovery despite relatively resilient demand for flats.
The market remained divided between buyers covering immediate requirements ahead of the festive period and those postponing purchases until trading activity normalises after Diwali. Consequently, demand support was insufficient to trigger a broad-based price movement.
Finished longs
The stainless steel long-products market remained subdued during the week, with weak downstream demand and limited export opportunities weighing on procurement.
BigMint’s weekly assessment of 304-grade black bar prices remained unchanged at INR 200,000/t ex-works Mumbai. Meanwhile, 316-grade black bar prices fell by INR 5,000/t w-o-w to INR 365,000/t.
Export offers for 304-grade black bar were heard at around $2,190-2,200/t FOB Nhava Sheva, while 304-grade bright bar offers stood at $2,330-2,370/t FOB.
Buying interest remained limited as consumers continued to purchase cautiously amid the festive slowdown. Unlike flats, which received some support from pre-Diwali requirements, long products lacked a comparable demand trigger. Limited export opportunities further constrained market activity, keeping the near-term outlook subdued.
Raw material trend
Stainless steel scrap prices weakened ahead of Diwali amid subdued finished-steel demand and lower nickel prices. Indian imported 304 and 316-grade scrap offers, along with domestic 304-grade scrap prices in Mumbai, declined during the week ended 16 October.
Buying activity remained cautious as mills prioritised immediate requirements over inventory building. Some western Indian mills also shifted towards nickel pig iron (NPI) and billets, indicating a preference for alternative raw material options amid changing input economics and weak finished-product offtake.

Global market
China’s stainless steel exports reached 454,600 t in September 2026, the highest monthly volume recorded so far this year, according to data from the General Administration of Customs of China. Shipments increased by 2% m-o-m and 8.6% y-o-y.
However, cumulative exports during January-September totalled approximately 3.35 million tonnes, down 11.4% y-o-y. China’s stainless steel imports during the same period reached 1.14 million tonnes, marginally higher by 0.2% y-o-y.
India remained a significant destination for Chinese stainless steel. September shipments to India stood at approximately 65,000 t, down 9.4% m-o-m but up 367% y-o-y. Cumulative shipments to India rose by 172.9% y-o-y to around 359,000 t during January-September.
The sharp y-o-y increase in Chinese shipments highlights the growing importance of import competition in India’s stainless steel market. Competitive overseas offers are likely to remain a key consideration for domestic buyers, particularly when demand is insufficient to absorb material at higher prices.
Outlook
India’s stainless steel market is expected to remain cautious in the near term, with festive-related disruptions and liquidity constraints likely to limit trading activity around Diwali. Price movements will also depend on changes in nickel and stainless steel scrap prices, import offers and post-festival restocking. A sustained recovery will require stronger end-user demand and improved buying activity, rather than seasonal purchases alone.
Leave a Reply