- Limited high-grade ore availability supports concentrate prices
- Weak Odisha demand and logistical constraints limit trading activity
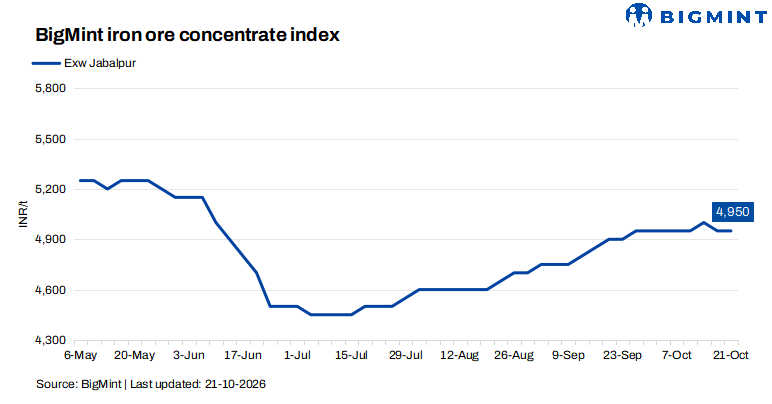
India’s iron ore concentrate prices remained largely stable during the week ended 21 October 2026, supported by limited availability of high-grade iron ore and steady domestic pellet prices. However, demand from Odisha softened slightly amid subdued downstream market conditions, while logistical disruptions and delayed order execution continued to restrict fresh trading activity. Market participants remained cautious ahead of Odisha Mining Corporation’s (OMC) upcoming iron ore e-auction scheduled for 22 October, with the outcome expected to influence offer and bidding strategies in the near term.
BigMint’s bi-weekly assessment for Fe 62% iron ore concentrate remained steady at INR 4,950/t ($52/t) ex-works on 21 October 2026 against the last assessment on 17 October. Seller indications ranged from INR 4,700/t ($49/t) to INR 5,200/t ($55/t).
Prices continued to draw support from limited high-grade ore availability, prompting market participants to prefer beneficiated material to meet quality requirements. Stable pellet prices also provided a degree of support to concentrate demand. However, slightly weaker buying interest in Odisha and subdued downstream steel demand limited the scope for a significant price increase.
Extended monsoon conditions and the festive season have disrupted normal operations, leaving several sellers occupied with executing previously committed orders rather than pursuing fresh business. Some suppliers are also facing raw material shortages, further restricting their ability to fulfil pending commitments and offer additional volumes.
A Jabalpur-based seller told BigMint that “material lifting had remained disrupted for five days due to Durga Puja holidays, with nearly 50% of the material still awaiting clearance. Limited rake availability has added to the backlog, delaying dispatches and constraining near-term trading activity. The seller also noted that bookings generally improve during the Diwali period.”
Meanwhile, the Madhya Pradesh government has made Radio Frequency Identification (RFID) tags mandatory for vehicles transporting minerals, with vehicle owners given one month to comply. The initiative aims to strengthen transportation monitoring, track vehicle movements and curb unauthorised mineral movement and royalty evasion. The impact on dispatch efficiency will depend on the implementation of the system.
Market participants are closely tracking OMC’s iron ore e-auction scheduled for 22 October 2026, as the revised base prices are likely to influence subsequent selling offers and bidding strategies. OMC has reduced base prices by around INR 150/t for fines and INR 50–450/t for calibrated lump ore (CLO), offering 1.43 million tonnes (mnt) of fines and 0.731 mnt of CLO.
The price reductions reflect weakening steel market conditions in eastern India, alongside pressure from lower sponge iron and billet prices. The previous auction also reportedly saw around 40% of the offered material remain unsold, reinforcing concerns over demand absorption and price discovery. The upcoming auction will therefore provide a key indication of procurement appetite and the extent to which sellers may need to adjust their offers.
Rationale
- One (1) trades were recorded in this publishing window, which is taken into consideration. Therefore, this category received a 50% weightage.
- Eight (8) offers and indicative prices were heard, of which five (5) were taken into consideration as T2 trades, receiving 50% weightage.
Factors influencing market dynamics
- Raipur pellet offers remain firm: Raipur pellet offers for Fe 63% pellets remained unchanged at INR 11,800/t ($125/t) DAP Raipur on 21 October 2026, with firm seller offers providing support to concentrate prices. However, cost effective landed offers from Odisha has impacted counter offers.
- Odisha iron ore prices remain under pressure: BigMint’s assessment for Fe 62% fines declined marginally by INR 50/t to INR 5,500/t ex-mines in the week ending 10 October 2026. Improved dispatches and ore availability, combined with lower pellet and sponge iron prices, continued to weigh on sentiment.
Outlook
Iron ore concentrate prices are expected to remain largely stable to marginally weaker in the coming week, as limited high-grade ore availability and steady pellet prices continue to provide underlying support. However, softer demand in Odisha, lower OMC auction base prices and cautious procurement may limit further upside. The 22 October auction outcome, along with post-festive demand and improvements in rake availability, will be key to determining the near-term price direction.
Leave a Reply