- Production curbs offer limited price support
- Buyers remain on sidelines amid declining steel realisations
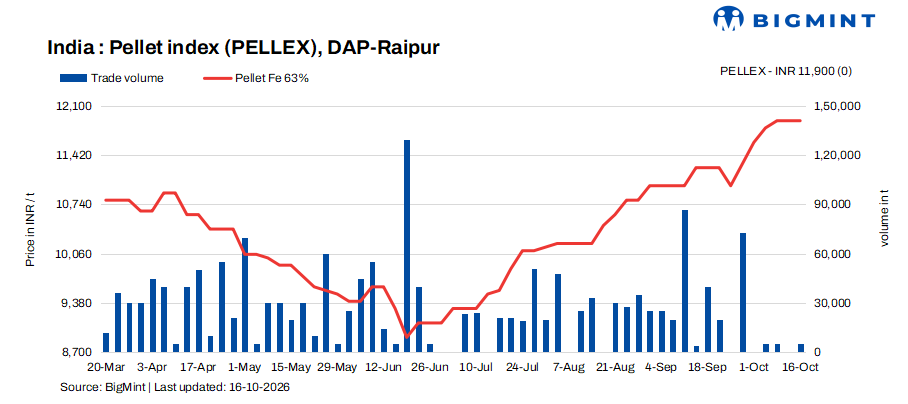
PELLEX, BigMint’s bi-weekly domestic pellet (Fe 63% ± 0.5%) index for Raipur, remained unchanged at INR 11,900/t ($125/t) DAP Raipur on 16 October 2026 compared with the previous assessment on 13 October. Despite firm offers from pellet manufacturers, market sentiment remained under significant pressure as steep declines in sponge iron and billet prices widened the gap between seller expectations and buyers’ price acceptability.
Market participants reported a growing disconnect between quoted pellet prices and actual market conditions. While sellers continued to maintain higher offers, buyers remained reluctant to book material at prevailing levels, anticipating a potential correction in line with the weakening downstream steel market.
Trading activity remained largely muted, with procurement restricted as participants preferred to wait for clearer price signals before committing to fresh purchases. Although sellers continued to quote firm prices, market feedback indicated that some were willing to negotiate discounts of around INR 300-400/t ($3-4/t) to secure deals, highlighting the underlying pressure on realisations.
Rationale
- PELLEX has been derived using data points, i.e., trades, offers, and bids. To download the detailed methodology, click here.
- One (1) deals were recorded in this publishing window and was taken for calculation. Thus, the T1 trade category was accorded a weightage of 50%.
- Thirteen (13) firm offers, bids, and indicative prices were heard, of which ten (10) were taken for price calculation and given the balance 50% weightage.
Price movements and offers
Major pellet manufacturers in Chhattisgarh largely maintained their offers for Fe 62.5/63% (± 0.5%) grade pellets in line with the previous assessment. However, the firm quoted prices was not reflected in corresponding buying interest, as consumers continued to resist elevated offers amid deteriorating downstream economics.
Market sentiment remained distinctly bearish, with participants pointing to a widening gap between offer prices and buyers’ willingness to pay. While concerns over supply availability and production constraints supported sellers’ pricing stance, buyers indicated that prevailing rates were difficult to justify given the sharp correction in sponge iron and finished steel prices. Consequently, firm offers failed to translate into meaningful trading activity, with market participants increasingly anticipating downward price adjustments.
Market scenario
The Raipur pellet market remained under pressure from weak downstream demand, cautious procurement and growing expectations of a price correction. Market participants described a disconnect between quoted prices and actual transaction levels, with sellers reportedly willing to negotiate discounts of INR 300-400/t from initial offers in select cases. This indicated that headline prices were being maintained despite limited buying interest and mounting pressure to liquidate material.
Although concerns over an artificial supply squeeze were reported in the market, participants indicated that sufficient material was available, with no significant improvement in buying interest at prevailing price levels. The reluctance to procure was primarily driven by expectations of further weakness in sponge iron and finished steel prices, prompting buyers to defer purchases rather than lock in material at current rates.
Meanwhile, power shortages in the region were reportedly affecting plant operations, preventing some producers from running at full capacity. While these operational constraints could offer some support to pellet prices by limiting production, they have yet to offset the negative impact of weak downstream demand. The market therefore remained caught between sellers’ attempts to defend price levels and buyers’ growing resistance to high offers.

Key market drivers
- Sponge iron prices fall by INR 1,050/t ($11/t) w-o-w: Sponge PDRI prices stood at INR 27,800/t ($293/t) exw Raipur, softening by INR 1,050/t ($11/t) w-o-w on 16 October against 9 October. Buying activity remained subdued as the festive season, weak finished steel demand and limited immediate consumption discouraged fresh procurement. Thin enquiry levels forced sellers to lower offers to clear inventories, reinforcing expectations of further weakness in the near term. The correction in sponge iron prices added to the pressure on pellet market sentiment, as buyers remained unwilling to absorb high input costs amid declining downstream realizations.
- Billet prices drop by INR 1,300/t ($14/t) w-o-w: BigMint’s billet index in Raipur declined by INR 1,300/t ($14/t) to INR 43,800/t ($461/t) exw on on 16 October against 9 October. Weak downstream demand, limited enquiries and uncertainty over a near-term recovery continued to weigh on the market. Buyers largely adopted a wait-and-watch approach despite lower offers, while sellers made selective price adjustments to stimulate bookings. The sharp correction in billet prices further weakened confidence across the steel value chain, strengthening buyers’ expectations that pellet prices may eventually align with softer downstream market conditions.
Outlook
Leave a Reply