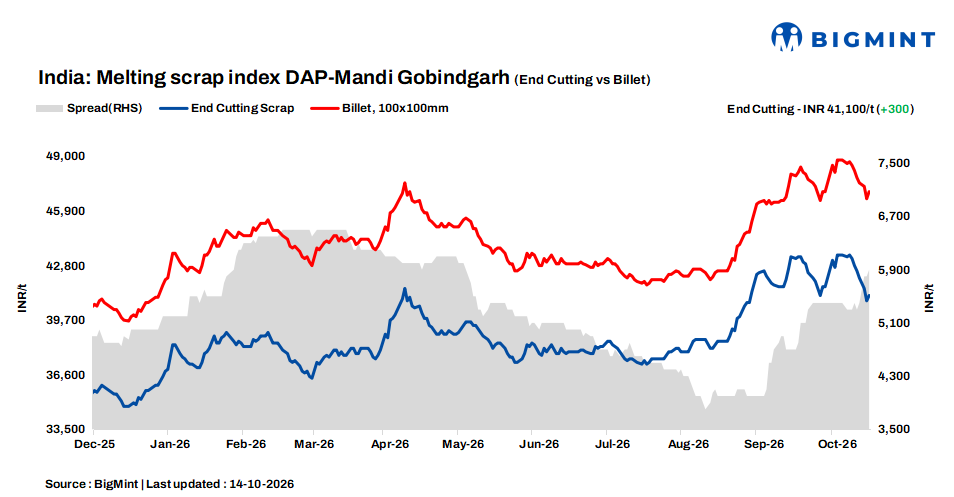
- Scrap demand recovered marginally following a week-long slowdown
- Semis, finished steel prices increase by INR 300-500/t d-o-d
BigMint’s domestic end-cutting scrap index, tracking the Mandi Gobindgarh market, advanced by INR 300/tonne (t) d-o-d to INR 41,100/t DAP on 14 October 2026. Regional scrap prices rose by INR 300-450/t d-o-d, underpinned by firmer semi-finished steel prices and a minor improvement in mill-side buying interest.
Mandi Gobindgarh, a key secondary steel hub, witnessed a modest improvement in demand today. Buying interest improved slightly across both raw material and finished steel segments after an extended lull, supporting firmer price trends. Scrap procurement activity gained momentum, while semi-finished and finished steel prices rose by INR 300-500/t d-o-d. The improvement points to a short-term recovery in market sentiment and better order inflows from downstream buyers.
A mill owner informed BigMint, “In Mandi Gobindgarh, scrap and finished steel prices rebounded after a six-day decline, but buyers remained cautious about the market outlook. While several mills anticipate another round of price hikes in the near term, buyers expect scrap prices to remain range-bound, with the possibility of a minor correction amid uncertainty over future market trends.”
Alternative raw material prices
Sponge iron (CDRI) prices in Mandi Gobindgarh increased by INR 200/t d-o-d to 34,000/t DAP, while steel-grade pig iron prices in Ludhiana remained stable d-o-d at INR 44,000/t DAP.
Steel market
In the steel segment, Mandi Gobindgarh ingot prices increased by INR 500/t d-o-d to INR 47,000/t DAP, supported by moderate buying activity during the session. The upward momentum was not limited to Gobindgarh, as ingot prices at other key hubs also strengthened by INR 200-1,000/t, indicating a broader improvement in market sentiment.
In the finished steel segment, rebar ex-works prices rose by INR 300/t to INR 52,500/t on steady downstream demand. HR strip (patra) prices followed a similar trend, gaining INR 500/t day-on-day to INR 51,000/t ex-works. The simultaneous increase across semi-finished and finished products suggests improving demand visibility and a firmer near-term price outlook.
Price highlights
End-cutting to billet spread: In Mandi, the spread between end-cutting scrap and billets stood in the range of INR 5,800-6,200/t.
Domestic vs imported scrap: Imported melting scrap prices at Nhava Sheva Port were assessed at $371-$372/t, approximately INR 37,700/t (inclusive of freight). HMS (80:20) prices in Mumbai remained stable d-o-d at INR 36,700/t DAP. Indicative prices of shredded from Europe stood at $415/t CFR Nhava Sheva.
Raipur sponge iron-billet spread: The conversion spread (margin) between pellet-based DRI (P-DRI) and steel billets in Raipur stood at INR 16,350/t.

To see BigMint’s melting scrap assessment, pricing methodology and specification documents, click here
To provide feedback on this index or if you would like to contribute by becoming a data partner, please contact – support@bigmint.co
Leave a Reply