-
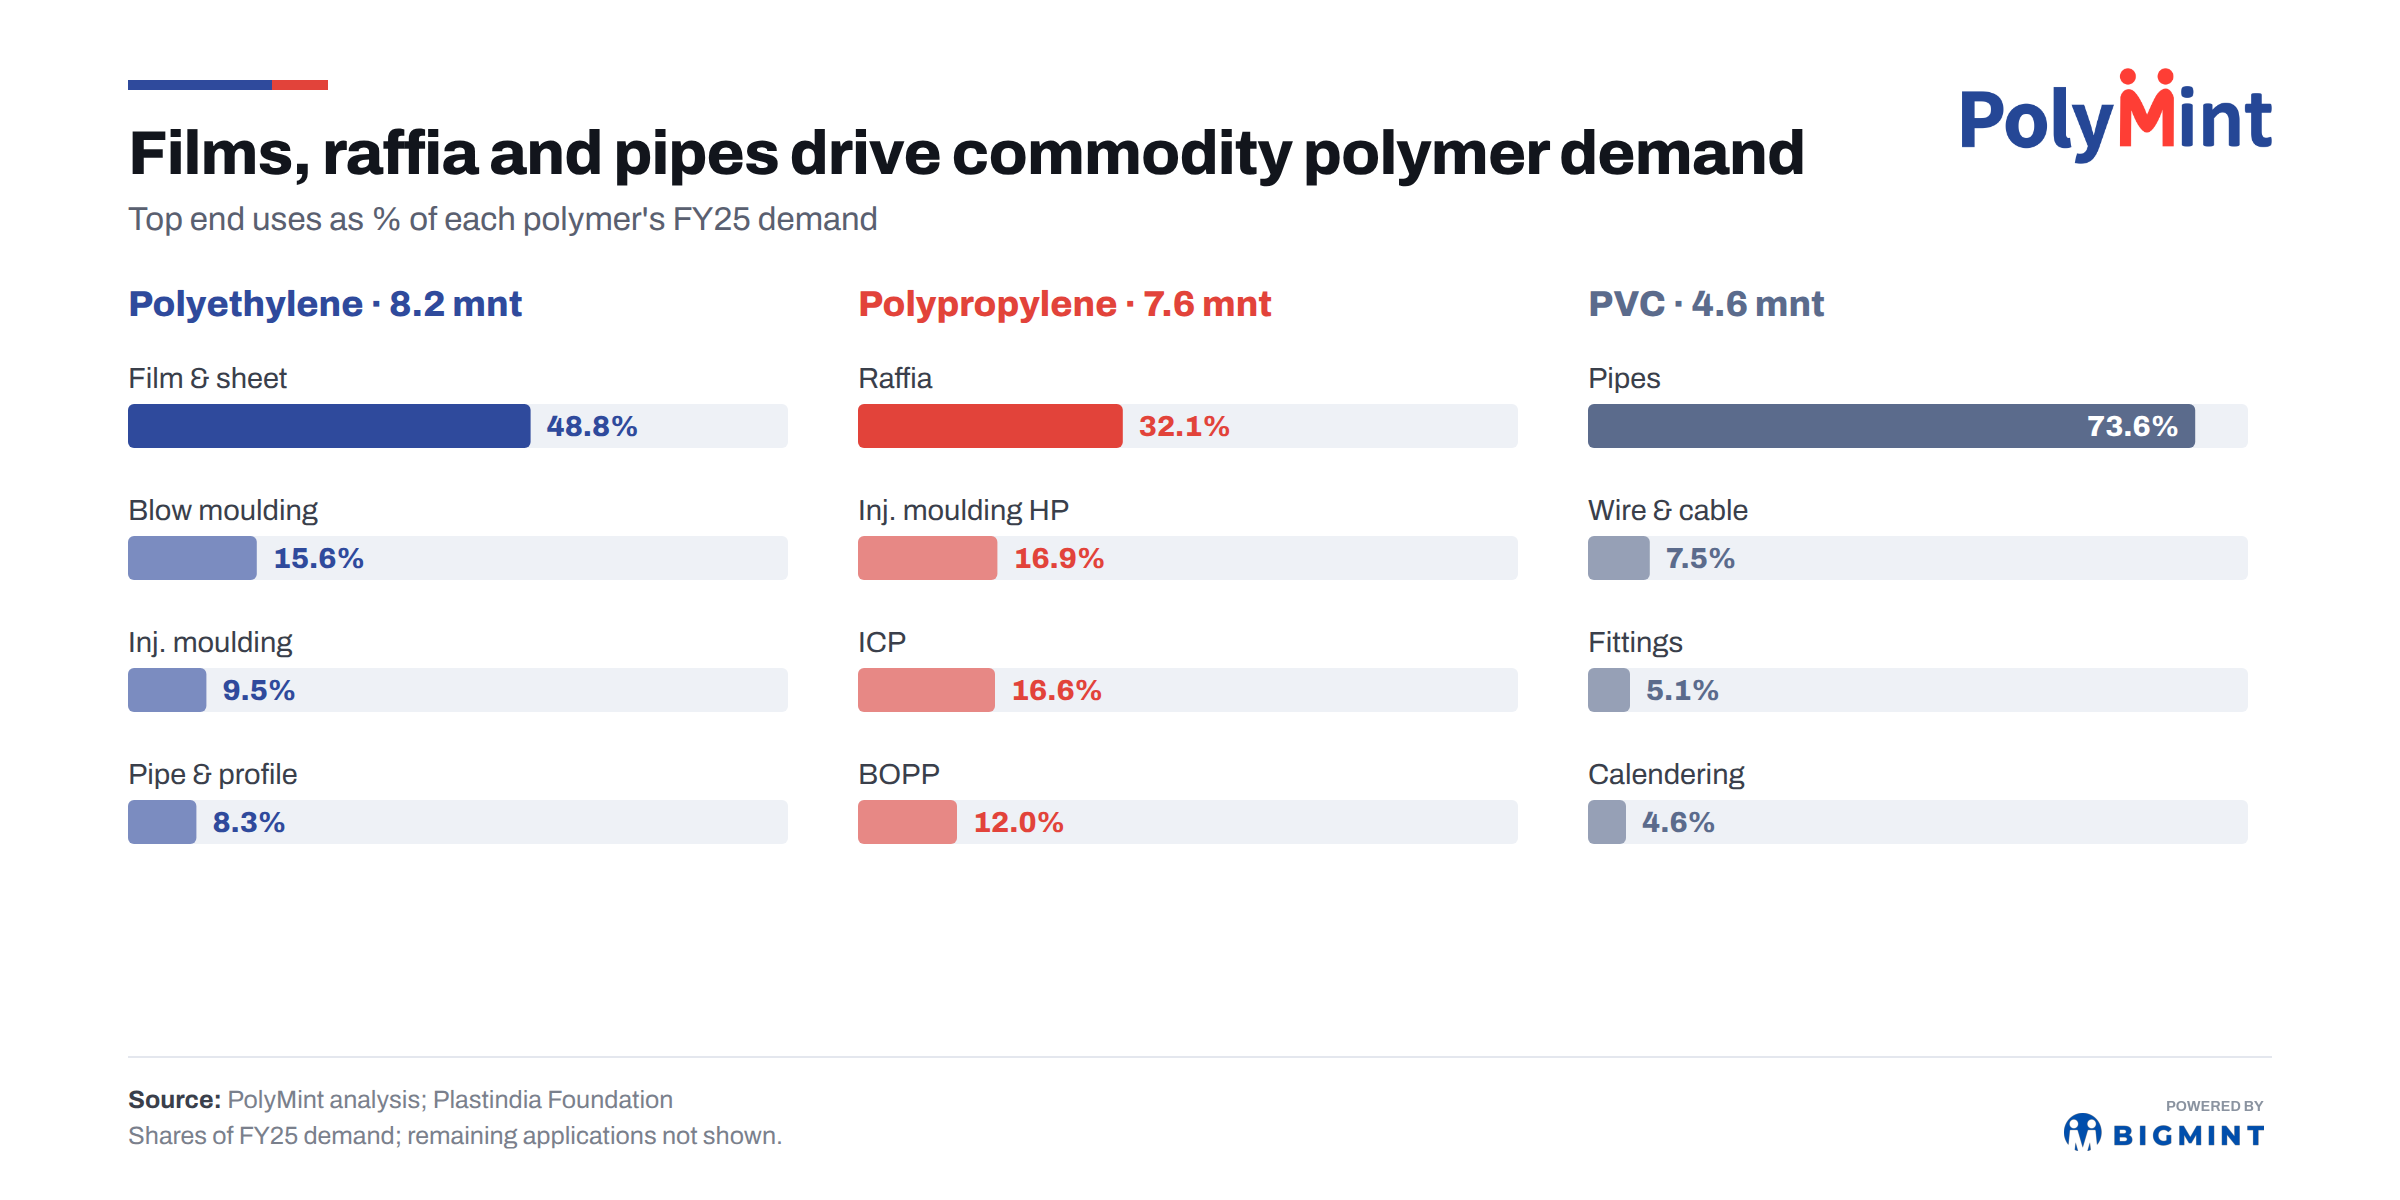
PE film & sheet leads demand at 49%; PP raffia 32%, PVC pipes 74%
-
PVC profiles and wire & cable lead growth at 23% each; PE pipes fall 20%
Three applications shape India’s commodity polymer market. Film and sheet consumes 49% of the country’s 8.2 million tonnes (mnt) of polyethylene (PE) demand, raffia takes 32% of 7.6 mnt of polypropylene (PP) and pipes absorb 74% of the 4.6 mnt polyvinyl chloride (PVC) market, according to Plastindia Foundation data for FY25.
This concentration means that a slowdown in packaging, agriculture or infrastructure moves resin demand quickly, and explains why PE, PP and PVC prices react so strongly to these sectors.
Where the growth is now
The fastest-growing outlets in FY25 were PVC wire and cable (+23%) and profiles (+24%), PE wire and cable (+14%), and PP impact copolymer and BOPP film (+13% each). PVC pipes grew 8.3% on infrastructure and water supply schemes.
PE film and sheet slipped 2.6% and PE pipes fell 20%, pulling overall PE demand down 2.4% for the year.

India’s plastics industry gathers in Ahmedabad
Which applications will drive resin demand in 2027, and how should producers and converters plan for them?
At PLAST.CONNECT 2026 – West India, PolyMint will bring together industry leaders to discuss polymer market trends, application demand, grades and supply chains.
Panel 1, Raw Materials & Virgin Polymers, moderated by Anish Patel, President, GSPMA, brings producers IOCL and HMEL and distributor Tegral India together to discuss market trends, distribution and quality standards for these grades.
Join us on 22 October at Le Meridien, Ahmedabad and be part of the conversation shaping India’s plastics value chain.
Leave a Reply